
FRANKFURT – A significant shift is rippling through the German housing market, signaling the end of an era defined by relentless price appreciation. For the first time in more than 24 months, the cost of residential property has retreated, marking a pivotal moment that offers both challenges for sellers and newfound, cautious optimism for prospective homebuyers.
According to the latest data from the GREIX (German Real Estate Index), a collaborative analytical effort between the Kiel Institute for the World Economy (IfW) and local expert committees, property values have finally succumbed to the cooling effects of interest rate volatility and shifting economic conditions. This development is not merely a statistical blip but a reflection of a broader, systemic recalibration of the German real estate sector.
Main Facts: A Market in Transition
The latest GREIX report reveals that in the third quarter of 2026, prices for apartments saw a year-on-year decline of 0.2 percent. While this percentage may appear modest, its significance lies in the timeline: it is the first time the market has recorded a negative trajectory compared to the previous year since the second quarter of 2024.
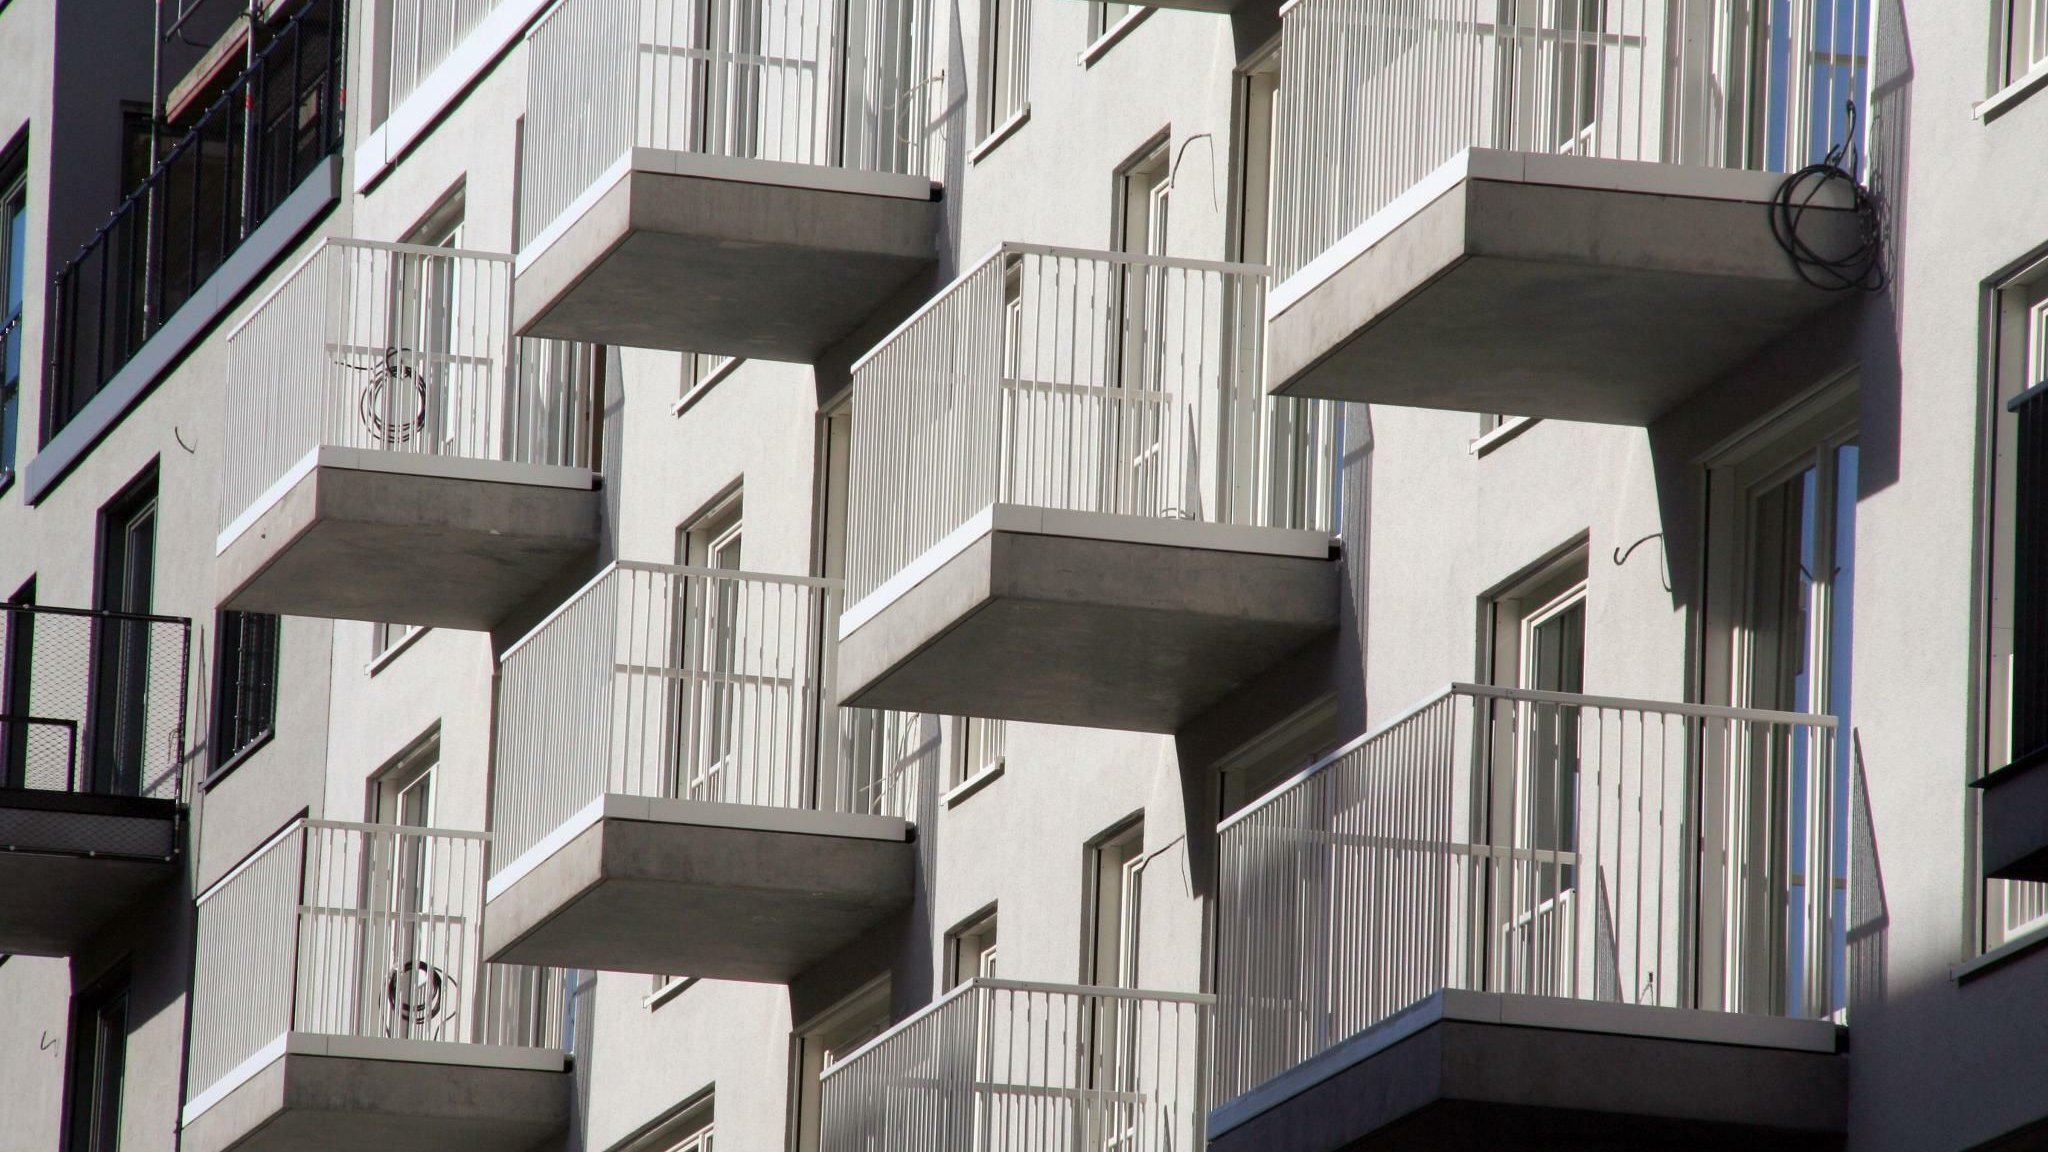
The core metrics of the market have fundamentally altered. Beyond the nominal price dip, the velocity of the market has slowed significantly. Real estate agents report that both apartments and single-family homes are languishing on the market for longer periods, suggesting a mismatch between seller expectations and buyer affordability.
The GREIX index is particularly authoritative because it is built upon actual, notarized sales data rather than listing prices, which often reflect the subjective hopes of sellers rather than the realities of the transaction floor. Consequently, this decline confirms that the "price wall" has finally been breached.
Chronology: The Road to the Pivot
To understand how we arrived at this cooling phase, one must look back at the trajectory of the post-pandemic housing boom.

- 2021–2023: The Apex of Demand: During the height of the low-interest-rate environment, the German real estate market experienced a historic surge. Demand consistently outstripped supply, driving prices to record highs in major metropolitan hubs like Berlin, Munich, and Hamburg.
- 2024: The First Tremors: By the second quarter of 2024, the momentum began to decelerate. While prices remained high, the year-on-year growth rate began to flatten as inflationary pressures and early signs of central bank tightening began to bite.
- 2025: The Stagnation Phase: For most of 2025, the market entered a period of "price discovery," where buyers and sellers struggled to find a common ground amidst rising mortgage costs.
- 2026: The Trend Reversal: The third quarter of 2026 marks the official pivot. With financing costs having plateaued at a high level and household purchasing power under pressure from energy and living costs, the market has finally tilted in favor of buyers.
Supporting Data: Regional Disparities
While the national average indicates a 0.2 percent decline, the reality of the German housing market is highly localized. Germany is not a monolith, and the "national trend" masks significant regional divergence.
The Metropolitan Pressure
In top-tier cities, the correction is most visible. Berlin, which for years saw double-digit growth, is seeing a softening in the central districts. The influx of capital that once drove prices upward has been replaced by a more cautious investor sentiment. Properties that were previously sold within days of hitting the market now face weeks or even months of open houses.
The Periphery vs. The Core
While urban cores are seeing price stabilization or minor dips, the surrounding regions are experiencing a more pronounced cooling. The "commuter belt" strategy—where buyers moved further out to find affordability—is now being tested as the combined cost of commuting and financing becomes prohibitive for many middle-class families.
Transaction Volume
The most striking data point, perhaps more so than the price decline, is the drop in transaction volume. Notarial activity has slowed across the board. This indicates that owners who are not under immediate financial pressure to sell are opting to hold their properties rather than accept a lower offer, while buyers remain sidelined, waiting for more favorable lending conditions.
Official Responses and Expert Analysis
The Kiel Institute’s researchers emphasize that this decline is a necessary correction after years of overheating. Dr. Moritz Schularick, a prominent economist, has frequently noted that the "bubble-like" growth of the previous decade was fueled by unsustainable monetary conditions.
"We are seeing a return to a more rational pricing mechanism," says an analyst from the IfW. "When credit was virtually free, the asset value became detached from rental yields. Now that capital has a price again, we are witnessing the inevitable alignment of property prices with the economic reality of the average household."
However, industry associations remain concerned. The German Property Federation (ZIA) has warned that the decline in prices, coupled with high construction costs, is leading to a dramatic drop in new project starts. Their concern is that the current price correction might solve the affordability issue for existing homes today, but it risks creating a massive housing shortage for tomorrow.
Implications: What This Means for You
The current climate presents a complex set of implications for different market participants.
For Prospective Homebuyers
The news is undeniably positive for those who have been saving for a down payment. The era of "bidding wars" has largely concluded. Buyers now have the luxury of time—they can perform more rigorous building inspections, negotiate on price, and compare multiple properties without the fear of losing out to an all-cash investor. However, the hurdle remains the interest rate environment, which makes the monthly debt service significantly higher than it was three years ago.

For Current Homeowners
For those looking to sell, the message is one of strategic patience. The days of "asking any price" are over. Sellers must now ensure their properties are in top condition and priced realistically based on current comparables. Those who bought at the absolute peak of the market may find themselves in a "negative equity" position if they need to sell urgently.
For Investors
Institutional investors are currently in a "wait-and-see" mode. The yields on residential real estate, when compared to the risk-free return of government bonds, are currently less attractive than they have been in a decade. We expect to see a pivot toward high-efficiency, sustainable properties (ESG-compliant) as investors look for long-term security over short-term capital gains.
The Path Forward: A Balanced Future?
The dip in property prices is unlikely to result in a market crash. The fundamental shortage of housing in Germany, particularly in the rental sector, provides a "floor" for the market. As long as the population in urban centers continues to grow and the rate of new construction remains suppressed by high interest rates and labor costs, the long-term outlook for German real estate remains resilient.
The current 0.2 percent decline should be viewed as a signal of a "soft landing." It is an opportunity for the market to reset, shedding the excesses of the boom years and moving toward a more sustainable equilibrium.
Key Takeaways for 2026/2027:
- Normalization of Prices: Do not expect a return to the rapid growth of 2021. The market is moving toward a period of stagnation or very slow, inflation-adjusted growth.
- Quality is King: Properties with poor energy ratings will likely continue to see sharper price declines due to the upcoming costs of renovations mandated by EU climate directives.
- The Rise of Rental Demand: With fewer people able to buy, the rental market will likely tighten further, keeping rental yields attractive for landlords who are not forced to sell.
In conclusion, the German real estate market has officially exited the period of hyper-growth. While the 0.2 percent drop is the headline, the real story is the return of the buyer’s voice in the negotiation process. Whether this leads to a broader recovery or a prolonged stagnation depends entirely on the trajectory of European Central Bank policies and the federal government’s ability to stimulate new housing supply. For now, the market is breathing, resetting, and waiting for the next catalyst.