
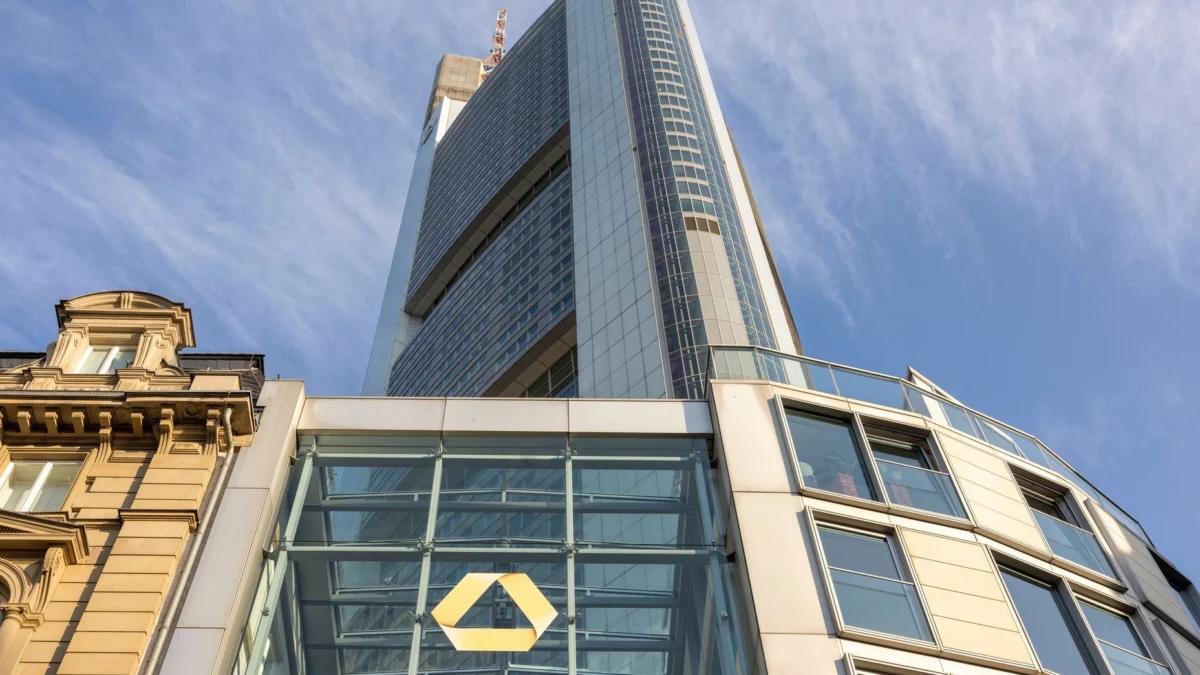
The German banking landscape is currently defined by a singular, high-stakes drama: the aggressive pursuit of Commerzbank by the Italian powerhouse, UniCredit. As Commerzbank navigates the complex path toward a potential integration, it has simultaneously posted strong financial results, illustrating a bank in peak operational form even as its corporate independence hangs in the balance. This convergence of profitability and vulnerability has created a volatile environment for shareholders, employees, and corporate clients alike.
Financial Resilience Amidst Strategic Turmoil
In its latest quarterly report, Commerzbank demonstrated remarkable financial vigor. The Frankfurt-based institution announced that its net profit for the third quarter of 2024 surged by 45 percent to 859 million euros. This robust performance highlights the effectiveness of the bank’s ongoing transformation strategy under CEO Bettina Orlopp. The return on tangible equity (RoTE), a critical metric for gauging the efficiency and profitability of financial institutions, climbed to 11.9 percent—outperforming the 10.6 percent reported by its domestic rival, Deutsche Bank, for the same period.
Despite these impressive figures, the bank narrowly missed the consensus expectations of market analysts, who had projected a profit of 864 million euros. Similarly, revenues of 3.2 billion euros fell slightly short of forecasts. While the bottom line is healthy, the bank’s outlook for the remainder of the year reflects the growing pressure from the competitive environment.
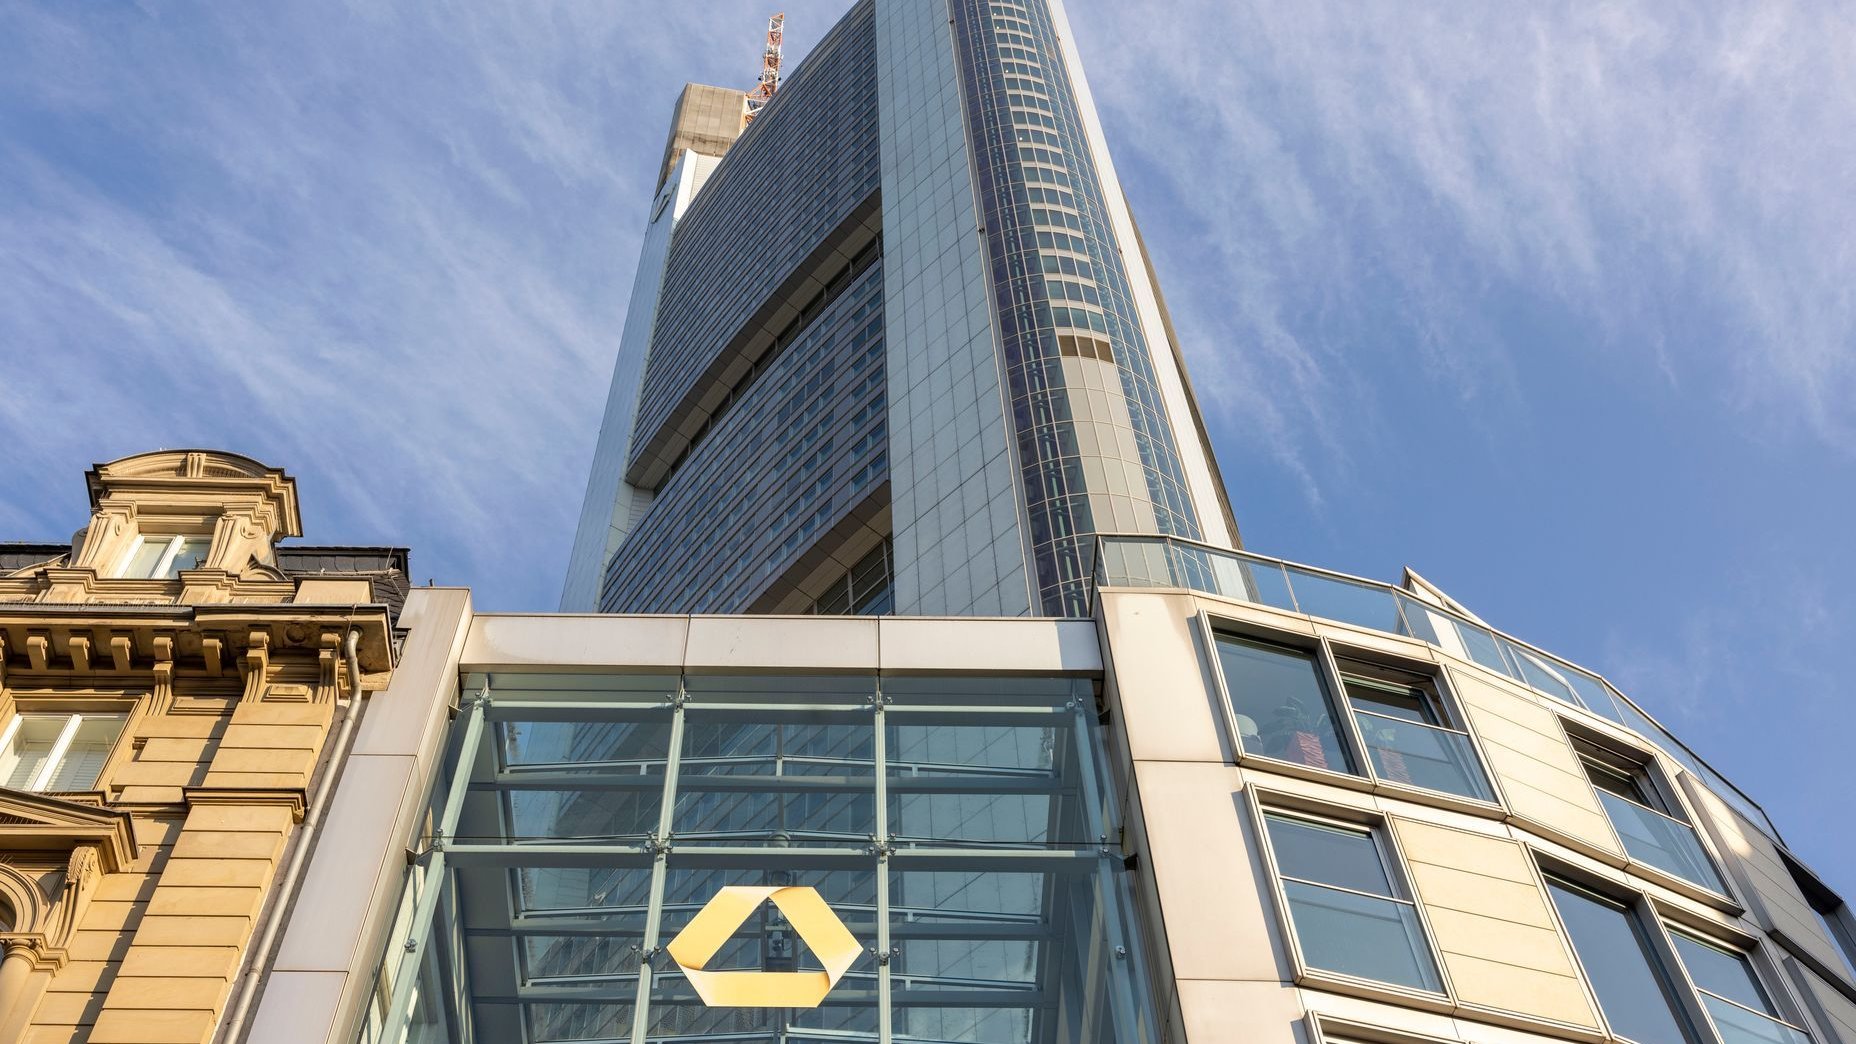
Commerzbank reaffirmed its full-year profit target of at least 3.4 billion euros and projected revenues of approximately 13.2 billion euros. However, it made a tactical adjustment to its interest income forecast, lowering it from 8.6 billion to 8.5 billion euros. The primary driver for this revision is the intensifying competition for customer deposits in Germany. In a market where savers have become increasingly yield-sensitive, banks are forced to offer higher interest rates to retain liquidity, which in turn compresses margins.
A Chronology of the UniCredit Offensive
The current standoff is the culmination of months of strategic maneuvering that began in early 2024. UniCredit, under the leadership of CEO Andrea Orcel, saw an opportunity to consolidate its position in the European market by building a significant stake in its German peer.
- Initial Entry: Throughout 2024, UniCredit quietly accumulated shares in Commerzbank, eventually building a position that now stands at nearly 30 percent.
- The Aggressive Pivot: The relationship shifted from strategic investment to a potential takeover bid. The market was caught off guard by the speed with which UniCredit moved to solidify its influence.
- The Roadmap to Integration: UniCredit has signaled its intent to launch a formal takeover offer, which, if successful, would see its stake rise to nearly 50 percent. Analysts expect this transition to move rapidly, with the potential for completion before the end of the year.
- Leadership Turbulence: Financial circles suggest that once the acquisition is finalized, Orcel intends to overhaul the Commerzbank supervisory board and subsequently replace CEO Bettina Orlopp. The long-term goal is an integration with UniCredit’s German subsidiary, Hypovereinsbank (HVB), within the next two to three years.
The Shrinking "Investment Case"
The prospect of a forced marriage between two of Germany’s largest financial players has not been met with universal approval. In fact, many long-term shareholders—including major institutional players like Union Investment, Deka, and DWS—have significantly reduced their stakes.

The sentiment among these investors is increasingly skeptical. The consensus view, often summarized by the phrase "the investment case is broken," stems from the belief that the potential synergies of a merger with UniCredit are outweighed by the risks of organizational friction, culture clashes, and the potential loss of market share. For minority shareholders, the future under an integrated UniCredit-Commerzbank entity appears less attractive than the prospect of a standalone, highly profitable Commerzbank.
Corporate Clients: Searching for Alternatives
Perhaps the most significant threat to the value of a merged entity lies in the reactions of corporate clients. German businesses, which rely heavily on the dual-banking system provided by Commerzbank and HVB, are expressing deep unease regarding the prospect of reduced competition.
According to a recent survey conducted by Finance Magazin among 334 financial decision-makers, 75 percent of respondents view the potential takeover negatively. The core concern is "concentration risk." Many companies currently use both Commerzbank and HVB as separate, independent providers for their financing needs. If these two banks merge, these companies risk becoming too dependent on a single institution.

The survey findings are alarming for the proponents of the merger: 64 percent of those polled are already rethinking their banking pool or have begun scouting for additional lenders to diversify their credit lines. One CFO noted, "Due to our previous experiences with UniCredit, we are reducing our business with both banks so that 1+1 once again equals 1." This "flight to safety" is a clear signal that the merger could lead to a significant exodus of institutional capital and lending business.
The Battle for Talent and Market Share
While the boardroom drama unfolds, the competitive landscape in the German banking sector is shifting. Domestic rivals, including Deutsche Bank, the DZ Bank, and various state-owned Landesbanken, view the current instability at Commerzbank as a historic opportunity.
Deutsche Bank CEO Christian Sewing recently noted that the intensity of client discussions has risen sharply in the last three to four months. "People are looking for a German bank with an international network," Sewing remarked, positioning his institution as the natural alternative for clients fleeing the uncertainty of a UniCredit-owned Commerzbank.

This is not limited to client acquisition; it is also a battle for human capital. Employees within Commerzbank have reported a deteriorating work environment, characterized by uncertainty regarding future roles and corporate strategy. There have already been reports of significant resignations, and there is a pervasive fear among the staff that the next major turnover period will lead to a "mass departure."
Official Responses: A Plea for Trust
Faced with mounting pressure from both the market and his own potential future employees, UniCredit CEO Andrea Orcel has taken a conciliatory tone. In a personal statement released last week, he addressed the German business community directly, pleading for trust and patience.
"I personally stand for fulfilling these promises and ensuring that our words are followed by concrete actions," Orcel stated. He emphasized that the intention behind the acquisition is to strengthen, not diminish, the support provided to German corporate clients. He promised to expand resources and maintain the service levels that both HVB and Commerzbank clients have come to expect.

However, for many within the Commerzbank corridors, these promises are seen as damage control. The skepticism is rooted in the "confrontational" nature of the takeover process thus far. Management at the target bank has signaled that while they are open to value creation, they remain wary of a top-down integration that ignores the unique requirements of the German "Mittelstand" (small and medium-sized enterprises).
Implications for the Future
The situation remains a high-stakes chess game with significant implications for the European banking union. If the acquisition proceeds as planned, it will mark one of the most significant cross-border banking mergers in recent history.
1. The Operational Risk
The primary challenge for UniCredit will be to retain the confidence of the German corporate sector. If a significant percentage of clients do indeed leave to join other banks, the value of the acquisition will be severely diminished, as the merged entity would be buying a shrinking business.

2. The Cultural Clash
The integration of a major German lender into an Italian banking group presents immense organizational challenges. Differences in management styles, labor laws, and corporate governance will require a level of diplomacy that has, to date, been absent from the transaction.
3. The Regulatory Landscape
The European Central Bank and German regulators are watching closely. The stability of the German financial system is a matter of national interest, and any move that threatens the credit supply to German companies will face intense regulatory scrutiny.
4. The Human Factor
The success of the future entity will depend on its ability to retain its workforce. If the "brain drain" continues, the technical and relationship-based expertise that makes Commerzbank a pillar of the German economy will be lost. As one long-term employee succinctly put it: "I believe something needs to happen quickly, otherwise many employees will vote with their feet. Then it will really blow up at the next resignation deadline."

Conclusion: A Turning Point for European Banking
The events surrounding Commerzbank represent a critical juncture for the European banking sector. While the logic of consolidation—gaining scale, efficiency, and market reach—is compelling on paper, the execution is proving to be a logistical and psychological minefield.
Commerzbank’s strong Q3 results serve as a reminder of the bank’s inherent strength and its value as a standalone entity. However, the shadow of UniCredit’s 30 percent stake looms large, acting as both an accelerant for change and a catalyst for instability. Whether the coming months bring a collaborative transition or a protracted, confrontational struggle remains to be seen. What is certain, however, is that the outcome of this saga will set a precedent for future cross-border banking mergers in Europe for years to come. The industry is not just watching a takeover; it is witnessing a test of whether a truly integrated European banking market is compatible with the deeply rooted national interests of its constituent economies.