As French bond yields hit levels not seen in two decades, financial markets are bracing for a potential paradigm shift. With debt soaring and political gridlock hampering reform, investors are asking: Is France the new epicenter of a Eurozone crisis, or simply a wake-up call for fiscal discipline?
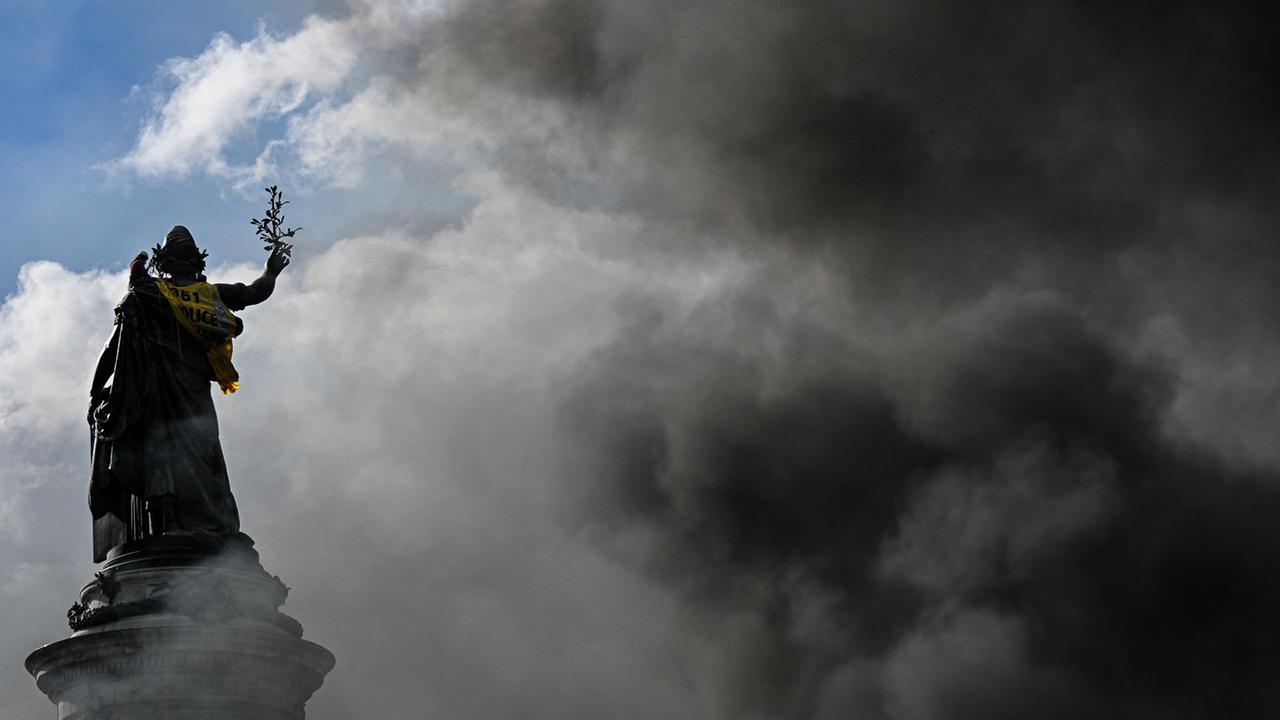
The financial architecture of the Eurozone is facing its most significant test in years. In Paris, the mood is somber as the "Place de la République" reflects more than just civil unrest; it mirrors the volatility currently roiling the country’s sovereign bond markets. For the first time since 2002, the cost of borrowing for the French state has surged to levels that are beginning to alarm both institutional investors and European policymakers. As the risk premium on French government bonds relative to German Bunds widens to a 15-year high of 1.6 percentage points, the question of whether France could trigger a systemic collapse of the currency union has moved from the fringes of economic debate to the center of global financial concern.
The Core Facts: A Triple Constraint
At the heart of the crisis lies what analysts describe as an inescapable "trilemma." France is currently attempting to maintain a comprehensive welfare state, satisfy the rising fiscal demands of increased defense spending necessitated by the geopolitical climate, and simultaneously ensure the long-term sustainability of its debt.
Volker Schilling, a lead strategist at Greiff Capital, notes that these three objectives are fundamentally incompatible under current conditions. "France is at a crossroads," Schilling told the ARD Financial Desk. "The market is no longer willing to fund all three simultaneously. Hard choices regarding priorities must be made, and the financial markets are now acting as the enforcer of that reality."
The arithmetic is unforgiving. Data from the International Monetary Fund (IMF) projects that France’s public debt will climb to 118.5 percent of GDP by the end of 2026. To put this into perspective, at the onset of the Eurozone debt crisis in 2010, France’s debt-to-GDP ratio hovered around 86 percent. Furthermore, the national budget deficit is expected to reach 5.4 percent of economic output this year—nearly double the 3 percent threshold mandated by the European Union’s fiscal rules. These numbers create a feedback loop: as yields rise, the cost of servicing existing debt increases, further bloating the deficit and triggering further market skepticism.
Chronology of a Crisis: From Stability to Anxiety
To understand the current volatility, one must look at the transition from the Eurozone’s "core" to its "periphery." Historically, the Eurozone was divided into the stable core—led by Germany and France—and the more vulnerable periphery, which included Greece, Portugal, Spain, and Italy.
During the height of the 2010–2012 crisis, investors penalized the southern European states, demanding higher risk premiums while flocking to French and German debt as "safe havens." Today, that dynamic has inverted. In a remarkable shift, French debt is now perceived as carrying higher risk than Italian debt in some market segments. This has led analysts to proclaim that "the new periphery of the Eurozone now begins at the Seine."
The timeline of this descent is marked by persistent political gridlock. As domestic reform agendas stalled in the National Assembly, investor confidence began to erode. The current situation reached a boiling point this week as markets anticipated a potential credit rating downgrade by Moody’s. A downgrade would not only increase borrowing costs but would also force institutional investors with strict mandate requirements to divest from French assets, potentially triggering a secondary wave of selling.
Supporting Data: Why Investors are Nervous
The data driving this market sentiment is stark. The yield on ten-year French government bonds has breached the five-percent threshold for the first time in 24 years. While some observers caution against panic, noting that this is not a systemic breakdown of the Euro, the sheer speed of the yield expansion is unprecedented for a G7 nation.
The fiscal slippage is particularly concerning to ratings agencies. Unlike previous periods of economic expansion, France is currently struggling to find a path toward fiscal consolidation. With a divided parliament and a public that is increasingly resistant to austerity, the government finds itself unable to pass the structural reforms necessary to curb spending.
Comparatively, the Eurozone as a whole has become more resilient. European banks have significantly bolstered their capital buffers, reducing the risk of a banking-sector contagion that characterized the 2012 crisis. Yet, the sheer size of the French economy—the second-largest in the Eurozone—means that a prolonged period of high yields in Paris cannot be ignored by the European Central Bank (ECB).
Official Responses and the "Whatever It Takes" Legacy
The shadow of Mario Draghi’s 2012 pledge to do "whatever it takes" to save the Euro continues to loom over European finance. However, current ECB policy is much more nuanced. The central bank introduced the Transmission Protection Instrument (TPI) in 2022, a tool designed to allow the ECB to purchase the bonds of a member state if it faces unwarranted market pressure that threatens the transmission of monetary policy.
Despite this, the consensus among financial experts is that the ECB will not rush to deploy the TPI for France. The TPI is intended to correct "market distortions"—situations where yields rise due to irrational panic rather than poor fundamentals. Since France’s current yield surge is driven by legitimate concerns over its fiscal trajectory, the ECB is wary of intervening.
Stephan Kemper, Chief Market Strategist at BNP Paribas Wealth Management, emphasizes that the ECB is in a difficult position. "If the ECB intervenes now, it creates a moral hazard," Kemper explains. "It would send a signal to Paris—and to every other capital in the Eurozone—that fiscal discipline is optional because the central bank will act as the ultimate backstop. That is a dangerous precedent that the ECB is not yet willing to set."
Implications: A Political Construct Under Pressure
The implications of this crisis extend far beyond the balance sheets of French banks. The Euro is, at its core, a political project. For the last two decades, the tandem of Paris and Berlin has driven the European integration agenda. If France becomes a long-term fiscal laggard, the power dynamics of the European Union will fundamentally shift.
There is, however, a silver lining. Unlike the crisis of 2012, there is no serious political movement in France calling for an exit from the Eurozone. Even the most extreme political factions acknowledge that the nation’s economic survival is tied to the currency. This consensus prevents the "existential" panic that plagued the continent a decade ago.
Nevertheless, the path forward for France is narrow. The government must demonstrate a credible commitment to deficit reduction to satisfy both the European Commission and the global bond markets. This will require a delicate balancing act: implementing enough austerity to calm the markets without triggering a recession that would further increase the debt-to-GDP ratio.
Conclusion: The Clock is Ticking
As the dust settles on the recent protests and market sell-offs, the message to the Élysée Palace is clear: the era of cheap, unconditional credit has ended. The market is no longer looking for promises; it is looking for evidence of a structural pivot in fiscal policy.
The stability of the Eurozone rests on the shoulders of its two largest economies. While the European financial system is undoubtedly more robust than it was during the last decade, it is not immune to the consequences of sustained, large-scale fiscal mismanagement. Paris is currently being tested, and the outcome of this test will define the economic trajectory of the entire continent for years to come. For France, the time for incrementalism has passed; the time for a decisive, transparent, and painful fiscal correction is now. Whether the government has the political capital to deliver remains the most significant risk facing the European project today.