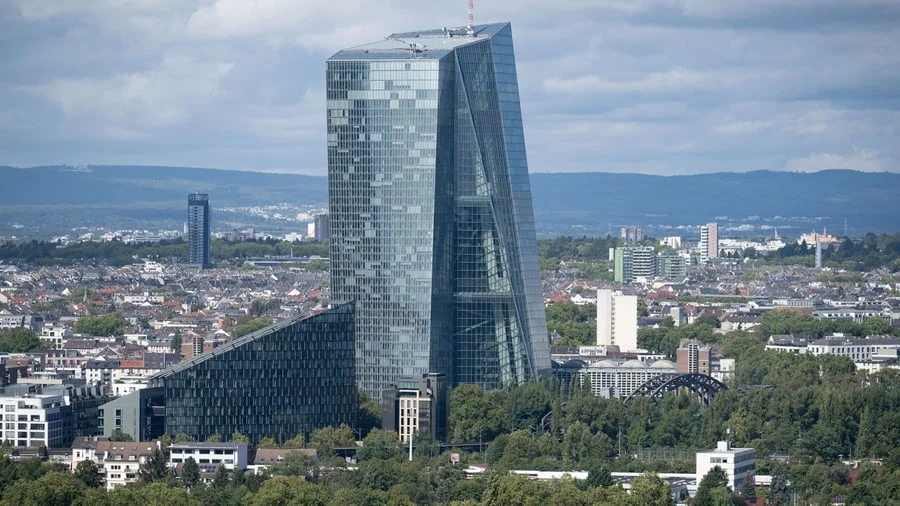
FRANKFURT – The era of "easy money" has firmly come to an end in the Eurozone. According to the latest data released by the European Central Bank (ECB), the financial landscape for European businesses and households is undergoing a profound transformation. The ECB’s quarterly Bank Lending Survey (BLS) paints a sobering picture: credit standards are tightening, loan demand is waning, and the long-standing boom in lending has reached a definitive turning point.
As interest rates remain at restrictive levels to combat persistent inflation, the economic engine of the Eurozone is feeling the friction. Banks are becoming increasingly selective, risk-averse, and cautious, signaling a potential cooling period for capital investment and consumer spending across the continent.
I. Main Facts: A Tightening Vise
The central takeaway from the ECB’s recent survey is the clear intensification of credit standards. Throughout the third quarter, financial institutions across the Eurozone continued to make it more difficult for both corporate entities and private individuals to access fresh capital.
This is not merely a localized phenomenon; it is a systemic shift. The primary driver behind this restrictive stance is the heightened perception of risk. With the economic outlook dampened by sluggish growth and geopolitical uncertainty, banks are prioritizing the preservation of their balance sheets over market share.
The data indicates that the "credit peak" has been surpassed. For more than two years, the economy benefited from a robust flow of credit, but that period has now concluded. Banks are no longer just raising the costs of borrowing—they are fundamentally narrowing the criteria under which they will approve a loan application.
II. Chronology: From Expansion to Retrenchment
To understand the current climate, one must look at the trajectory of the last 24 months.
- 2022 – The Great Shift: Following years of near-zero or negative interest rates, the ECB began an aggressive hiking cycle to counter runaway inflation. Initially, businesses maintained their demand for credit to manage supply chain disruptions and input cost increases.
- Early 2023 – Sustained Resilience: Despite higher borrowing costs, the credit market held up surprisingly well during the first half of the year as companies utilized existing credit lines.
- Summer 2023 – The Turning Point: The summer months marked a distinct shift. The "Bank Lending Survey" began to capture a more pronounced drop in demand for loans, particularly in the housing and commercial real estate sectors.
- Third Quarter 2023 – The Current Reality: The most recent data confirms that the tightening is now entrenched. For the first time in over two years, there was a measurable decline in corporate loan growth, signaling that the "wait and see" approach adopted by many firms has transitioned into a "hold and cut" strategy.
- Q4 Outlook: Banks have signaled that this trend is likely to intensify as they prepare for a winter of potentially higher defaults and economic stagnation.
III. Supporting Data: The Anatomy of the Decline
The Bundesbank, in its analysis of the ECB’s findings, has highlighted several critical metrics that underscore the severity of the situation.
The Decline in Corporate Demand
Perhaps the most alarming indicator is the decline in demand for corporate credit. Businesses are citing the high level of interest rates as the primary deterrent to new investment. When the cost of capital exceeds the projected return on investment, capital expenditure projects are inevitably shelved.
The Real Estate Cooling
The real estate market, once a darling of the low-interest-rate era, has experienced an "unexpectedly sharp" downturn over the summer. Both commercial and residential property developers are finding it increasingly difficult to secure financing. Banks are wary of the valuation risks in property markets where prices have yet to fully adjust to the new interest rate environment.
The Rejection Rate
The Bundesbank notes that banks are increasingly rejecting loan applications rather than simply increasing the interest rate. This suggests that the issue is not just about the cost of money, but about the availability of money. Banks are conducting stricter stress tests on applicants, focusing heavily on cash flow liquidity and the ability of borrowers to service debt in a higher-rate environment.
IV. Official Perspectives: The View from Frankfurt
The European Central Bank maintains that its current policy stance is necessary to bring inflation back to its 2% target. Officials argue that while the tightening of credit conditions is a "side effect" of the policy, it is also a "transmission mechanism." By making borrowing more expensive, the ECB is effectively slowing down the economy to dampen demand, which in turn should reduce price pressures.
However, the tone from the Bundesbank is slightly more cautious. They are closely monitoring the impact on the "Mittelstand"—the backbone of the German and European economy. The concern is that if small-to-medium enterprises (SMEs) cannot access the capital they need for innovation or day-to-day operations, the long-term competitive edge of European industry could be eroded.
Bank analysts suggest that the institutions themselves are under pressure from regulatory requirements. Capital adequacy ratios and liquidity requirements, while designed to keep the banking sector safe, can act as a pro-cyclical force that exacerbates the lending crunch during downturns.
V. Implications: What This Means for the Eurozone
The consequences of this credit environment are far-reaching, touching almost every sector of the European economy.
1. Dampened Capital Expenditure (CapEx)
When companies cannot borrow, they cannot invest. This leads to a cycle of under-investment in technology, green energy transitions, and infrastructure. If this persists, the Eurozone risks a period of "secular stagnation" where growth remains anemic for years.
2. The Housing Market Adjustment
The residential real estate sector is likely to face continued downward pressure. As mortgages become more expensive and credit standards tighten, the pool of eligible buyers shrinks. This creates a difficult environment for construction companies, which in turn impacts employment in the building trades.
3. Increased Insolvency Risks
The "zombie companies"—firms that were kept alive by cheap debt—are now facing a reckoning. As existing loans mature and need to be refinanced at current, much higher market rates, many of these companies will struggle to survive. We can expect an uptick in bankruptcy filings and corporate restructuring in the coming quarters.
4. Consumer Behavior
Households are already feeling the pinch. With the cost of consumer credit rising, discretionary spending is being curtailed. This cooling of private consumption is exactly what the ECB’s policy aims to achieve, but it brings with it the risk of pushing the Eurozone into a mild recession.
5. A Shift in Banking Strategy
Banks are clearly moving toward a defensive posture. They are prioritizing low-risk lending and are likely to favor large, established corporations over smaller, riskier borrowers. This creates a "credit gap" that may require policymakers to consider new instruments—such as public-private loan guarantee schemes—to ensure that the real economy does not starve for liquidity.
Conclusion
The findings of the latest ECB Bank Lending Survey serve as a stark reminder of the cost of reining in inflation. The transition from a period of abundant credit to one of scarcity is painful, yet it is a fundamental part of the economic cycle.
For businesses, the message is clear: the era of reliance on cheap debt is over. Companies must focus on internal cash generation and operational efficiency to navigate the months ahead. For the Eurozone, the challenge lies in ensuring that the credit squeeze does not turn into a credit collapse. As the ECB continues to walk the tightrope of monetary policy, the data will be watched with increasing urgency, as it provides the clearest signal of whether the Eurozone’s economy is merely cooling—or beginning to freeze.