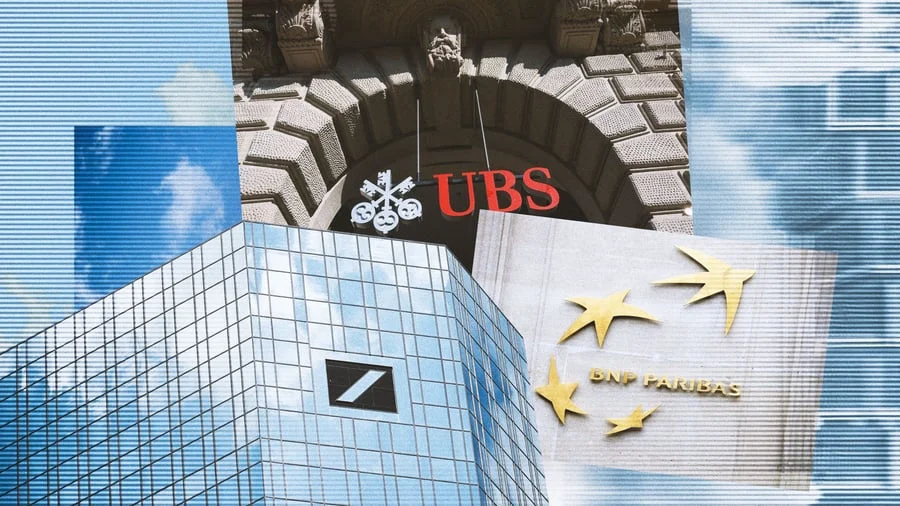
The era of effortless profitability for European banking institutions appears to be hitting a formidable wall. After a period of robust performance buoyed by rising interest rates and post-pandemic recovery, the sector is currently grappling with a confluence of macroeconomic stagnation, geopolitical friction, and shifting investor sentiment. As banks prepare to release their latest quarterly results, the narrative surrounding the industry has shifted from one of optimistic expansion to one of defensive posturing.
The Current Landscape: A Sector in Transition
For much of the past two years, European banks have enjoyed a "golden window" of profitability. The European Central Bank’s aggressive interest rate hikes provided a significant tailwind, allowing net interest margins to widen and balance sheets to swell. However, that momentum is now fading.

The broader European equity market, represented by the Stoxx Europe 600, has shown resilience, yet the banking sector has decoupled from this trend in the wrong direction. The Stoxx 600 Banks index has faced a sharp correction, shedding nearly ten percent of its value since the start of the month. This divergence highlights a growing anxiety among institutional investors regarding the sustainability of current earnings levels.
The catalyst for this recent volatility is multifaceted. From the political instability currently rattling France to the persistent sluggishness of economic growth across the Eurozone and the ongoing diplomatic and trade disputes involving Switzerland, the operating environment has become undeniably complex.

Chronology: The Erosion of Investor Confidence
The recent downturn did not happen in a vacuum. It is the result of a gradual accumulation of negative sentiment that reached a breaking point earlier this week.
- Early Q3 2024: Market analysts began signaling that the peak of net interest margin expansion was likely behind the sector. While banks remained profitable, the "easy money" derived from high rates started to plateau.
- Mid-October 2024: Geopolitical tensions, particularly regarding fiscal policy debates in France, began to weigh on regional bank valuations. Investors grew wary of the potential for increased taxation or regulatory burdens on financial institutions.
- Tuesday Morning: The turning point occurred with the release of the latest performance indicators from HSBC. The global banking giant reported figures that significantly undershot market expectations. Specifically, a pronounced weakness in revenue growth triggered an immediate sell-off, with HSBC shares plunging by 7.5 percent in a single trading session.
- Late Week: The shockwave from the HSBC report cascaded through the sector, leading to a broader sell-off across European exchanges as investors preemptively de-risked their portfolios ahead of upcoming earnings reports from other major players.
Supporting Data: Why the "Golden Era" is Fading
The data paints a sobering picture. The primary driver of the banking rally—the interest rate environment—is now becoming a double-edged sword. As the ECB signals potential rate cuts to stimulate a lethargic economy, the primary engine of bank profitability (net interest income) is expected to shrink.
Furthermore, the volume of loan originations has failed to recover to levels seen in the pre-inflationary era. In Germany and France, two of the continent’s largest economies, industrial output remains constrained, leading to a cautious approach toward corporate lending. When businesses are not expanding, banks lose their most lucrative source of revenue.
Moreover, credit quality is beginning to show early signs of stress. While default rates remain historically low, the "cost of risk" is trending upward. Banks are being forced to set aside larger provisions for potential bad loans, a direct reflection of the deteriorating financial health of their commercial clients.

Expert Analysis: The End of the Rekordjagd
Industry experts are cautioning that the period of record-breaking stock performance is firmly in the rearview mirror. Alexandra Annecke, a prominent fund manager at Union Investment, recently stated, "The record-breaking run of European bank stocks is over for now."
This assessment is shared by many in the City of London and Frankfurt’s financial district. The consensus is that the market is currently "pricing in" a long period of stagnation. The transition from a high-rate environment to a more neutral or easing cycle requires a fundamental shift in business models—a transition that many traditional banks are struggling to execute with the necessary speed.

Official Responses and Strategic Pivots
While the official reports from many European institutions are still being finalized, preliminary statements from management teams have focused on cost-discipline and capital allocation.
In response to the market reaction, several banks have signaled a move toward more aggressive share buyback programs, hoping to appease shareholders who are worried about dividend sustainability. Others are leaning into digital transformation, attempting to shed legacy costs that have long hampered their price-to-book ratios.

"We are entering a phase of operational efficiency," noted one executive from a major continental lender. "When revenue growth is harder to come by, the focus must shift entirely to the bottom line through digitisation and branch consolidation."
Implications: What Lies Ahead?
The implications of this shift are profound for the European economy. Banks serve as the plumbing for the financial system; if they become too risk-averse, credit availability for SMEs (Small and Medium-sized Enterprises) could tighten significantly.
- The Credit Squeeze: If banks increase their risk premiums to protect their balance sheets, the cost of borrowing for companies will rise, further depressing economic growth.
- M&A Activity: Analysts expect a wave of consolidation. Smaller, less efficient banks, struggling with the current margins, may become targets for larger, more resilient players looking to achieve economies of scale.
- Regulatory Scrutiny: With economic growth in the balance, political pressure on banks to support "national interests" or "green initiatives" is likely to increase. This adds a layer of non-market risk that investors are clearly beginning to fear.
- Investor Reallocation: As the banking sector loses its luster, capital is likely to rotate back into defensive sectors or technology-driven growth areas, further keeping bank valuations depressed in the near term.
Conclusion
The recent volatility in European banking is not merely a temporary blip; it is a structural adjustment. The sector is moving from a period of high-rate-induced excess to a period of reality-based growth. While individual banks with strong balance sheets and diversified income streams will likely survive and even thrive, the industry as a whole is facing a challenging period of recalibration.
For investors, the message is clear: the days of buying bank stocks simply for the interest rate tailwind are over. Future performance will be dictated by operational excellence, the ability to manage credit risk in a stagnant economy, and the agility to navigate a fragmented political landscape. As the next round of earnings reports looms, the market will be looking for more than just profit figures—it will be looking for a roadmap for survival in an increasingly uncertain economic climate.