Elon Musk’s aerospace giant, SpaceX, has officially signaled a bold transition from being a niche satellite internet provider to a direct challenger of the terrestrial telecommunications establishment. In a move that has sent shockwaves through Wall Street and prompted emergency meetings in boardrooms across the globe, Starlink—the company’s satellite internet division—has reached a definitive agreement to acquire a nationwide portfolio of mobile radio frequencies in the United States.
This strategic acquisition is not merely an expansion of existing capabilities; it is the final piece of a technological puzzle that could allow SpaceX to bypass traditional cell towers entirely, providing seamless, indoor-penetrating mobile connectivity directly to standard smartphones from orbit.
The Strategic Shift: Breaking the Indoor Barrier
For years, the Achilles’ heel of satellite-to-mobile connectivity has been the physical limitation of signal penetration. Traditional satellite signals operate on high-frequency bands that struggle to pierce through concrete, brick, or dense foliage. Consequently, previous attempts at satellite mobile telephony were restricted to open-sky environments—useful for emergency SOS features on mountain peaks, but insufficient for the demands of modern urban or suburban living.
By acquiring frequencies in the lower-frequency range—specifically the 800-megahertz (MHz) spectrum currently held by the investment firm Grain Management—SpaceX is effectively purchasing the "golden ticket" of telecommunications. Lower-frequency signals possess superior propagation characteristics, meaning they can navigate obstacles and provide reliable coverage inside buildings.
This new acquisition is intended to augment Starlink’s existing 2-gigahertz (GHz) spectrum, which is primarily optimized for high-bandwidth data transmission. By marrying the two, SpaceX is positioning itself to offer a hybrid service that provides both the raw speed of high-frequency data and the reliability of low-frequency penetration.
Chronology of a Disruption
To understand the gravity of this announcement, one must look at the rapid evolution of Starlink’s business model over the past few years:
- 2019-2021 (The Infrastructure Phase): SpaceX focuses on the aggressive launch of thousands of Starlink satellites, establishing the basic shell of a global low-Earth orbit (LEO) constellation.
- 2022 (The First Mobile Alliance): SpaceX announces a partnership with T-Mobile US, aiming to use "Direct-to-Cell" technology to eliminate "dead zones" across the United States. At this stage, skeptics argue that the bandwidth will be too limited for daily consumer use.
- August 2024 (The Denial Phase): Telecom CEOs, including Deutsche Telekom’s Tim Höttges, publicly dismiss the threat. Höttges asserts that satellite-to-mobile technology is merely a "supplement" for rural areas and lacks the capacity to challenge terrestrial mobile giants.
- Late 2024 (The Technical Breakthrough): SpaceX begins testing a new generation of "Direct-to-Cell" satellites capable of handling higher volumes of traffic, proving that the technical limitations cited by critics are rapidly being mitigated.
- Current Day (The Acquisition Phase): SpaceX secures a massive, nationwide low-frequency spectrum portfolio, moving beyond partnerships with mobile carriers to potentially acting as a standalone competitor.
Supporting Data: A Market in Flux
The financial implications of this move were immediate. Upon the announcement of the spectrum purchase, shares of major U.S. carriers—T-Mobile US, Verizon, and AT&T—dropped by more than 5% in after-hours trading. Investors are clearly pricing in the threat of a "price war" that could force these legacy companies to drop their subscription fees to remain competitive.
As of the end of March 2024, Starlink boasted over 10 million active subscribers. While this is still a fraction of the user base of a global giant like Verizon, the growth rate is exponential. Furthermore, the cost of satellite manufacturing and launch has plummeted due to SpaceX’s reusable Falcon 9 rocket program, giving Musk a massive competitive advantage in operational expenditures (OpEx) compared to the maintenance-heavy nature of terrestrial cellular towers.
Official Responses and Industry Skepticism
The reaction from the telecommunications sector has been a mix of calculated dismissiveness and defensive maneuvering. Tim Höttges of Deutsche Telekom has been one of the most vocal critics, arguing that satellite mobile communication is inherently limited by the physics of distance and the sheer volume of users a single satellite can support.
"Satellite mobile is a niche," a sentiment echoed by several European analysts. However, SpaceX’s Chief Operating Officer, Gwynne Shotwell, has consistently pushed back against this narrative. Shotwell emphasizes that the "Direct-to-Cell" technology is not just about filling holes in coverage; it is about redefining what a mobile network looks like.
"With our new, high-power satellites, we aren’t just looking to fill the gaps in rural regions," a spokesperson for the company hinted. "We are looking at a future where your phone connects to the network regardless of where you are standing on the planet."
Meanwhile, regulators at the U.S. Federal Communications Commission (FCC) are now under immense pressure. The proposed acquisition of the Grain Management frequency portfolio requires explicit government approval. The FCC must weigh the benefit of enhanced national connectivity against the risk of creating a monopoly that could destabilize the domestic mobile market.
The Technological Implications: A New Era of Connectivity
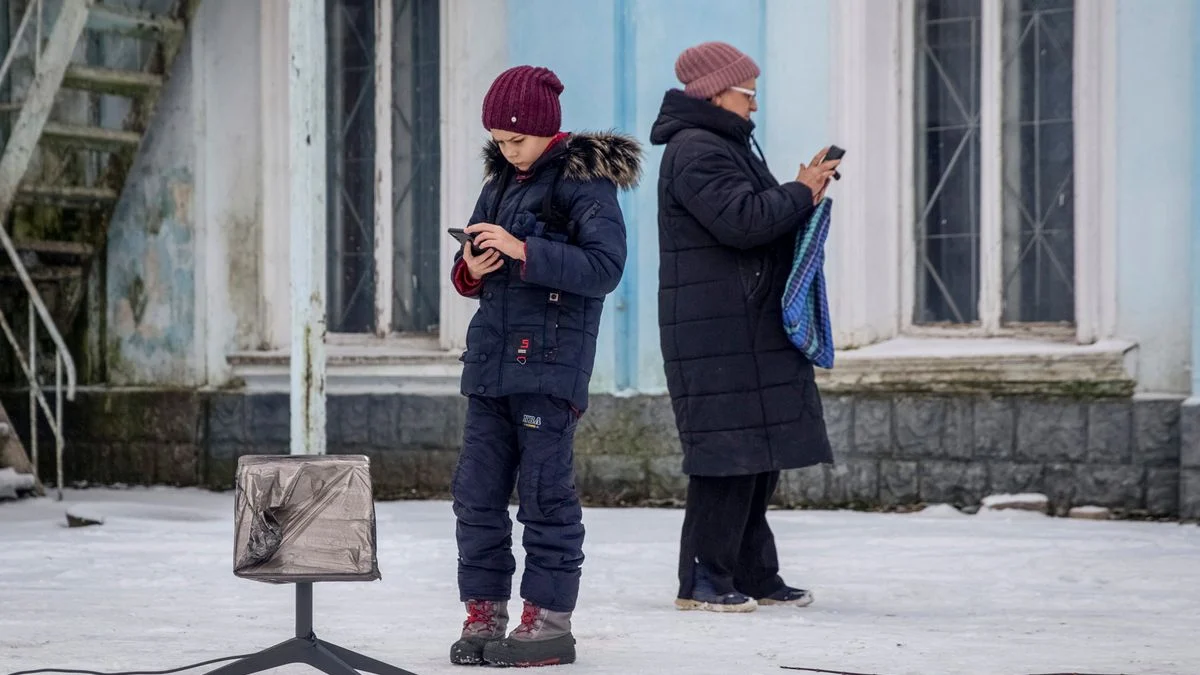
The transition from specialized satellite terminals—like the standard Starlink dish—to direct-to-smartphone connectivity represents a massive shift in user experience. Traditionally, consumers required a dedicated, powered terminal to access the Starlink constellation. With the next generation of satellites and the newly acquired 800 MHz spectrum, standard smartphones will essentially see the sky as a giant, ubiquitous cell tower.
1. Eliminating the "Digital Divide"
For decades, rural areas in the U.S. and abroad have suffered from poor connectivity due to the high cost of deploying fiber and towers in sparsely populated regions. SpaceX’s solution is inherently geographic-agnostic. By providing connectivity from above, the cost of coverage becomes independent of the density of the population on the ground.
2. The Threat to Legacy Infrastructure
If SpaceX successfully integrates this low-frequency spectrum, they could potentially offer a service that rivals 5G in terms of coverage consistency. This poses a structural threat to companies that have spent billions of dollars on land-based infrastructure. If a customer can get reliable, "good enough" data anywhere on earth for a flat, low monthly fee, the incentive to pay premium prices for terrestrial fiber or local cellular data plans diminishes.
3. Regulatory and Geopolitical Challenges
The acquisition is not without risks. Aside from the FCC approval process, there is the issue of international spectrum coordination. Different countries use different frequency bands, and SpaceX will have to navigate a complex web of international treaties and national regulations to roll out this service globally. However, if SpaceX succeeds in the U.S., it creates a blueprint that other nations may be forced to adopt or risk falling behind in the global digital economy.
Conclusion: The Final Frontier of Telecommunications
The move by SpaceX is more than a technical upgrade; it is a declaration of intent. By acquiring the ability to penetrate indoor spaces with mobile signals, Starlink has moved from the periphery of the telecommunications market to its very center.
The industry is now at a crossroads. Will legacy carriers innovate and adapt to this orbital challenge, or will they watch as their infrastructure, once considered an immovable utility, is rendered obsolete by a fleet of satellites operating silently in the vacuum of space? As the FCC begins its review of the spectrum deal, the world is watching, knowing that the outcome will dictate the future of human connectivity for the next several decades. One thing is certain: the era of the "cell tower" is being challenged by the era of the "space tower."