The Battle Over Business Assets: A Defining Moment for German Inheritance Tax
At the heart of the matter lies the preferential treatment of "Betriebsvermögen" (business assets) over "Privatvermögen" (private assets) when it comes to inheritance tax. While the state’s intention is to safeguard jobs and ensure the continuity of family-run enterprises, critics argue that the current exemptions have become overly generous, creating loopholes that disproportionately benefit the wealthy and lead to billions in lost tax revenue.
The political dimension of this judicial review became immediately apparent with a sharp intervention from Andreas Dressel, Hamburg’s Finance Senator and a prominent Social Democratic Party (SPD) politician. Dressel publicly quantified the financial drain, revealing that Hamburg alone has foregone a staggering 857 million euros in inheritance tax since the current privilege was introduced in July 2016. This sum, representing approximately 7.5 percent of the nationwide exemption volume, places Hamburg disproportionately among the affected states, highlighting the uneven financial impact across the German federal system.
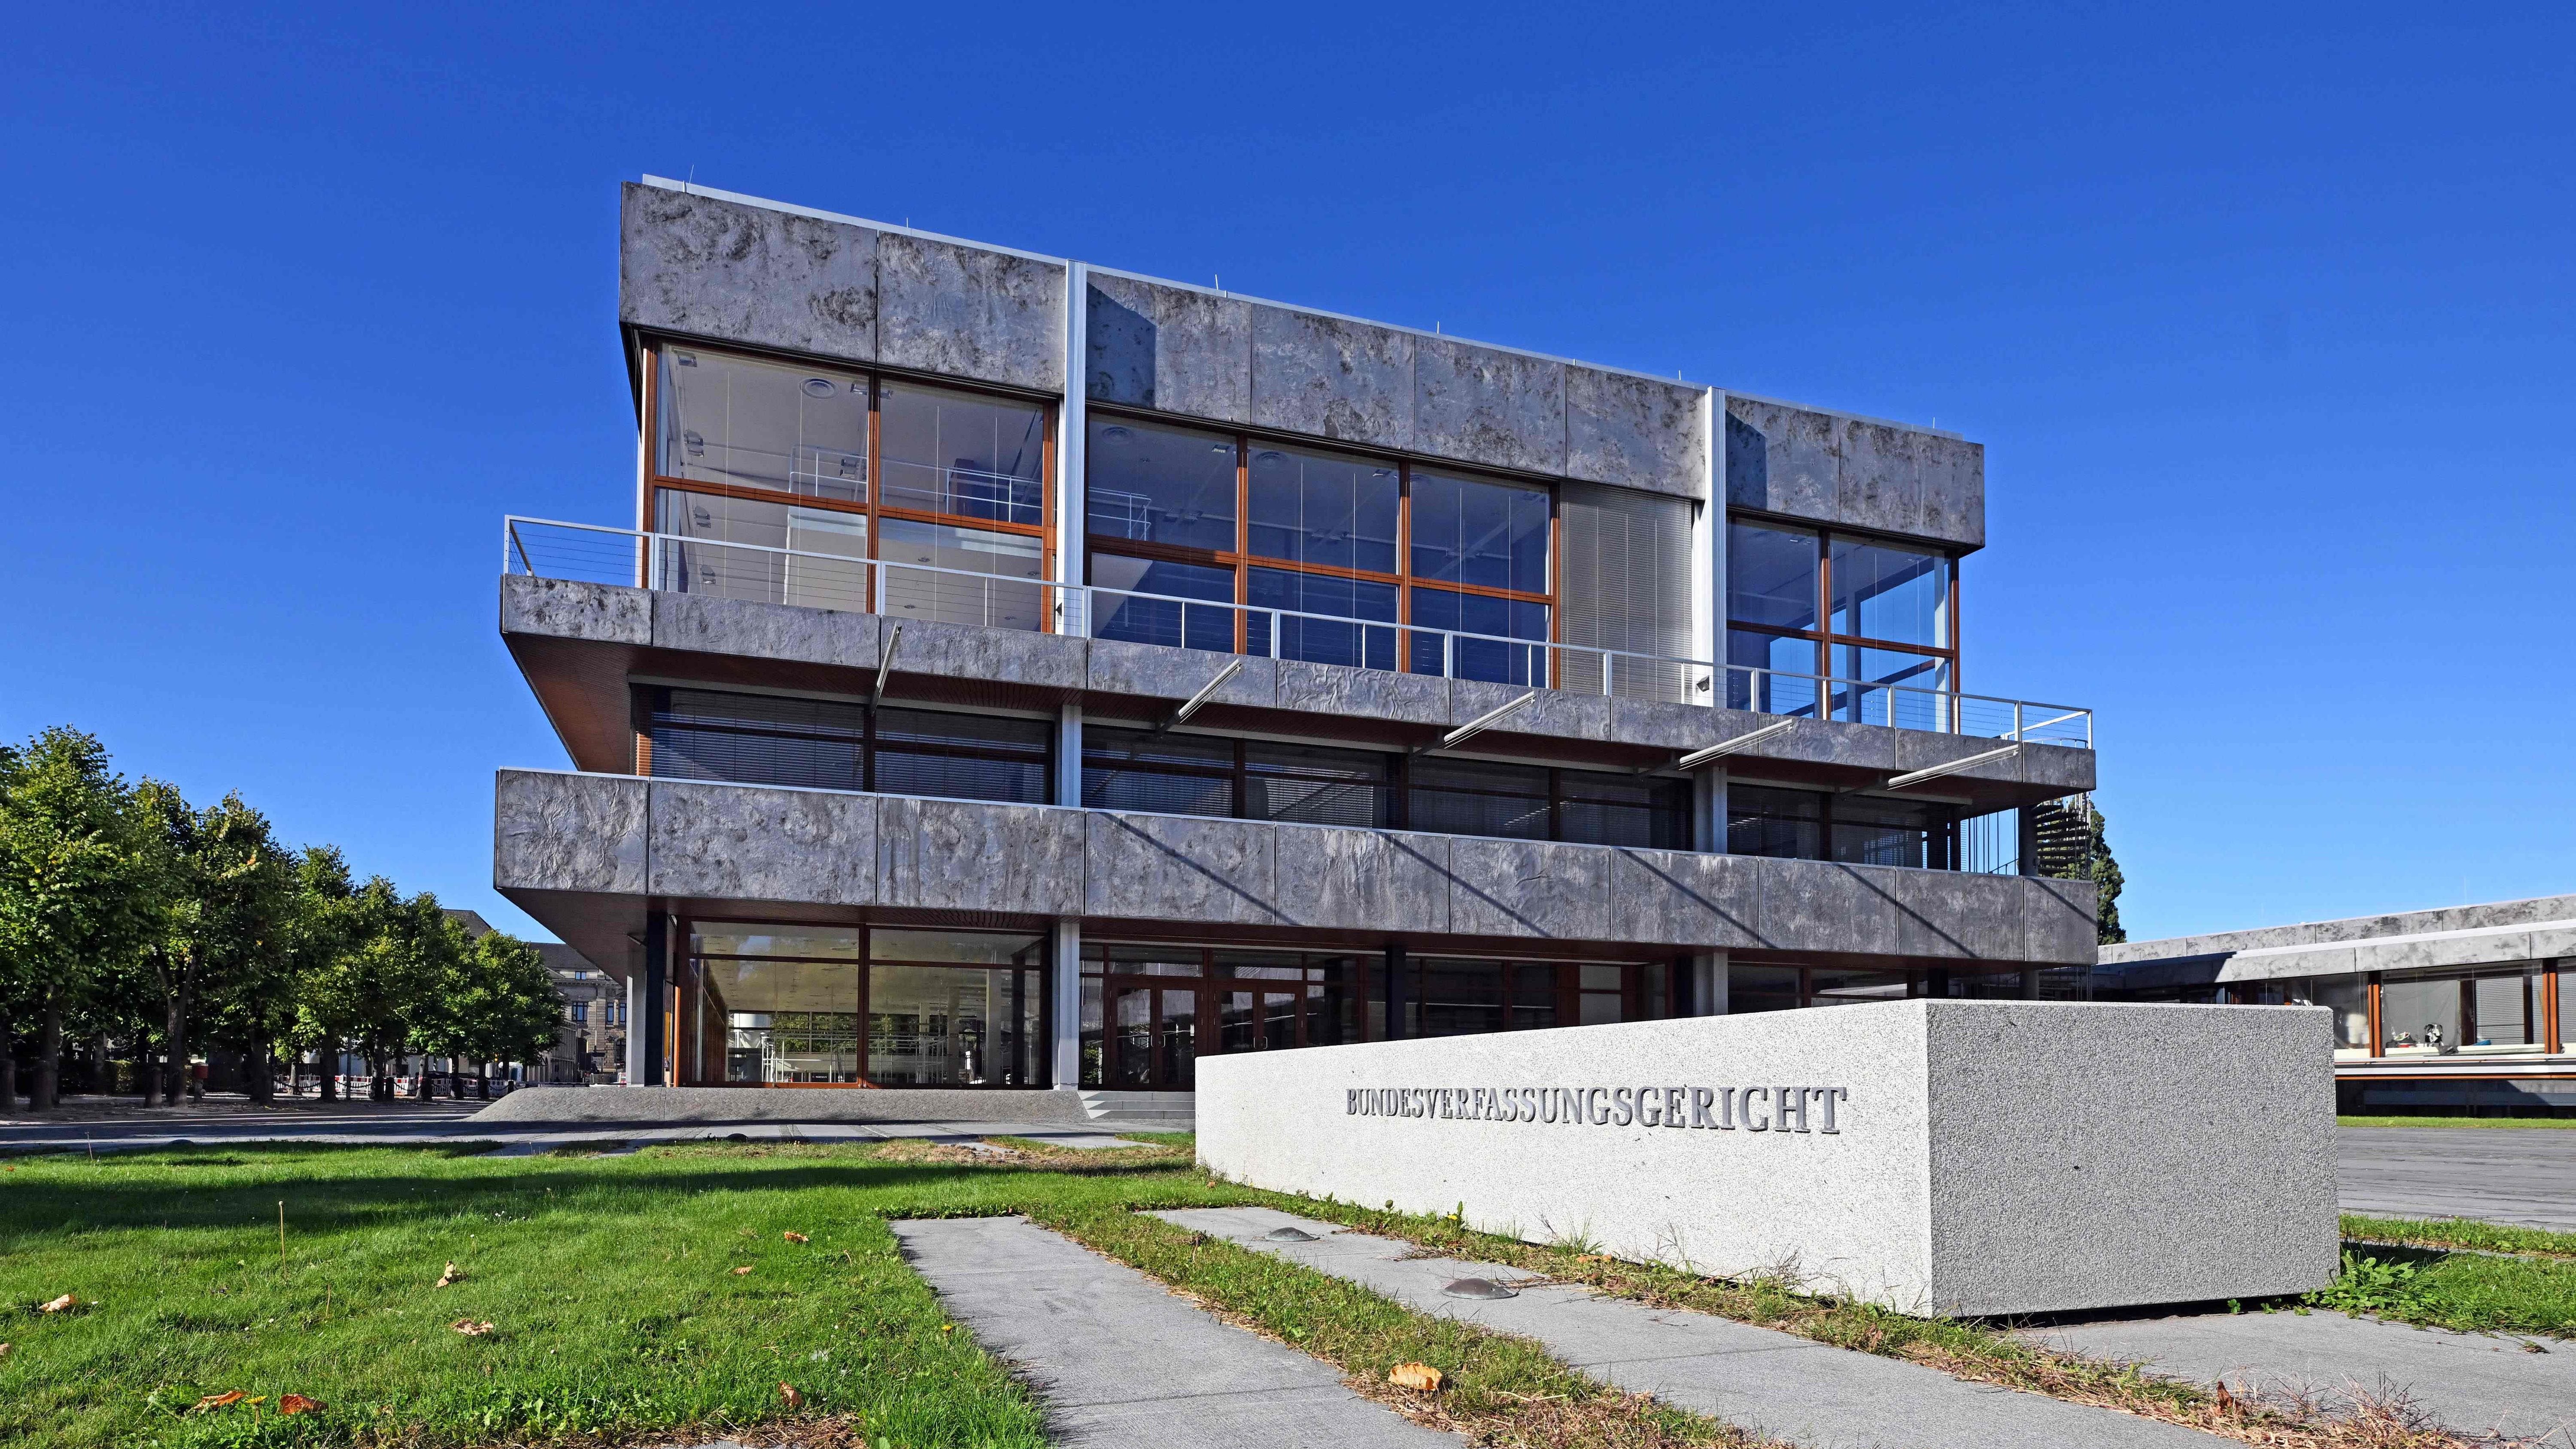
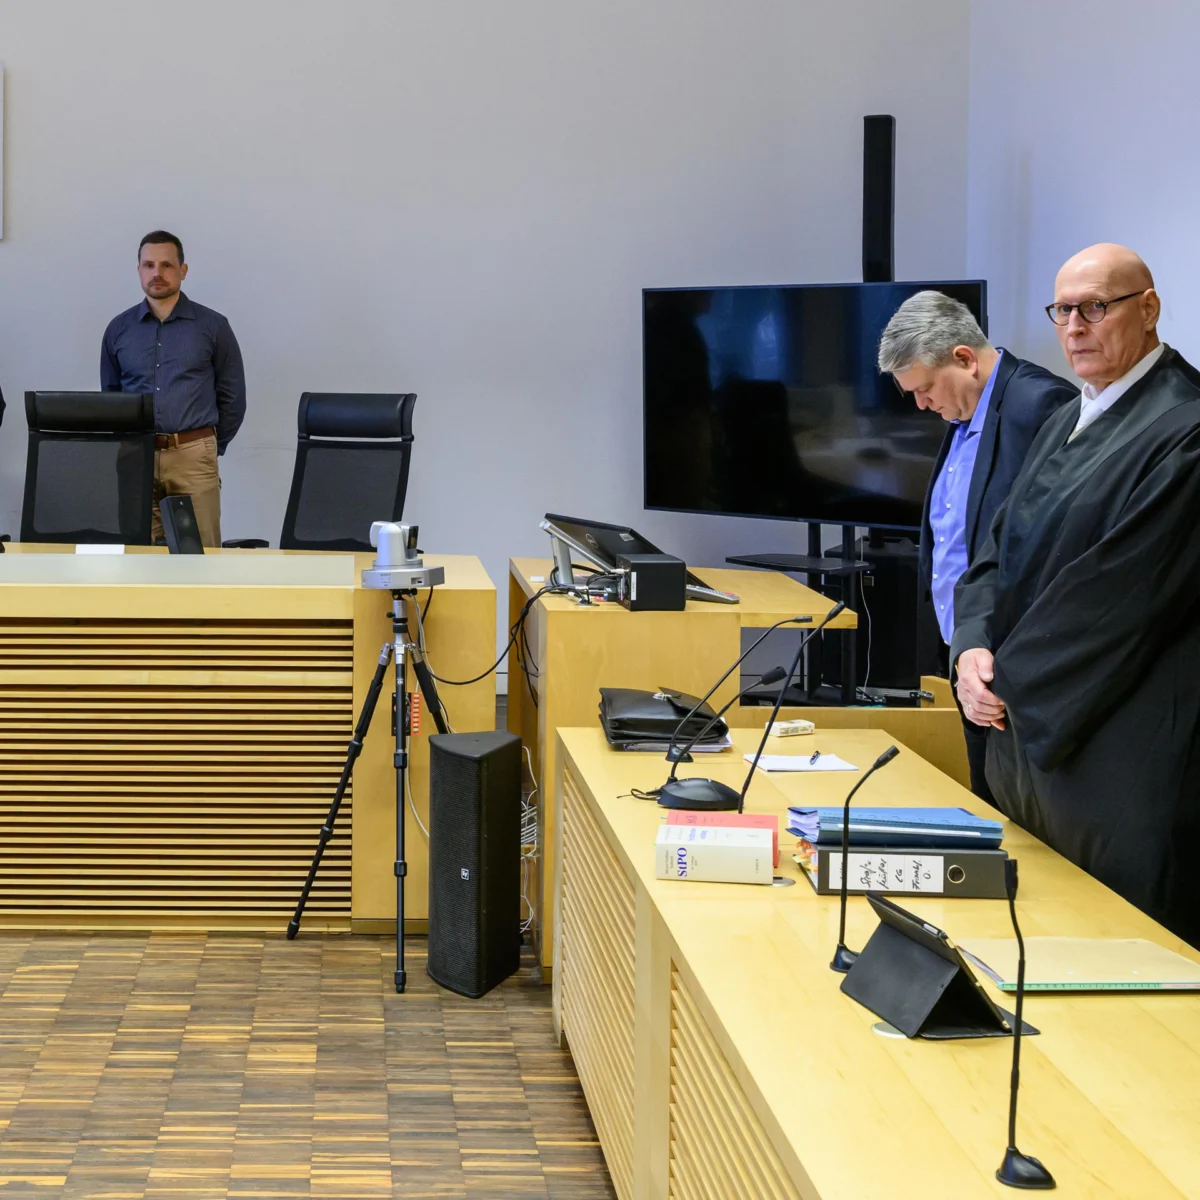
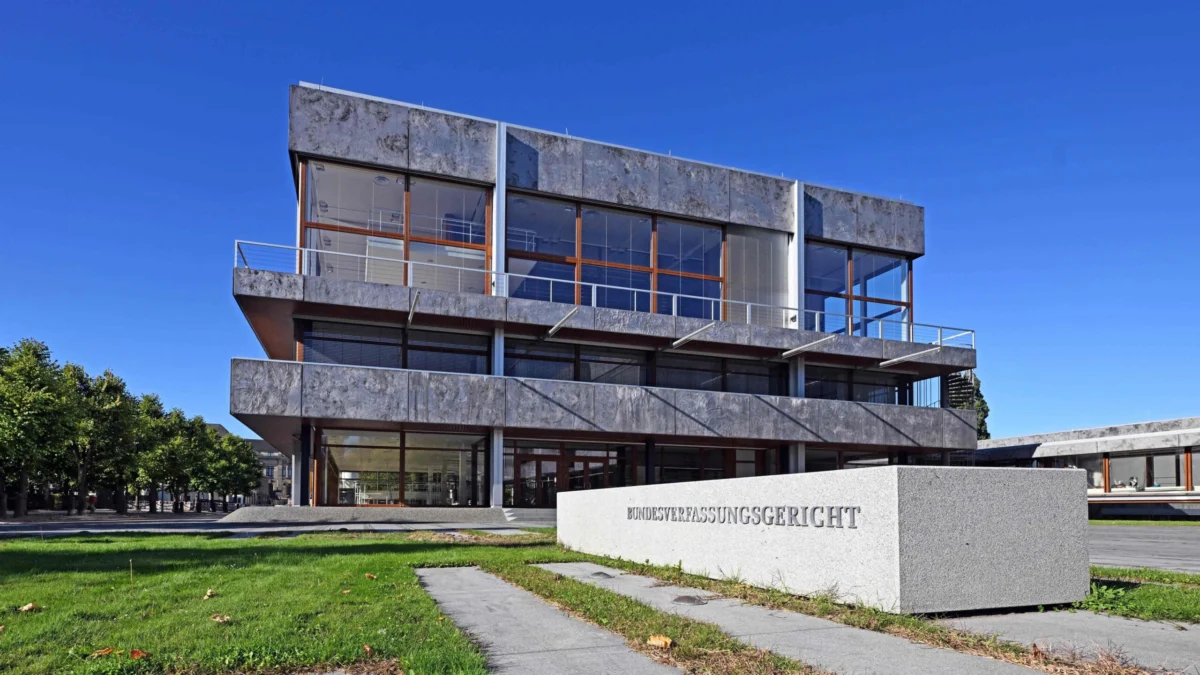
Court President Stephan Harbarth, opening the oral proceedings, acknowledged the profound societal relevance of the case. He stated that the question of equitable tax burden, particularly concerning inheritance tax, "touches the sense of justice of many people in our country in a prominent way." This statement sets the stage for a ruling that is expected to resonate far beyond the legal chambers, impacting countless family businesses, state budgets, and the political landscape itself.
Chronology of a Contentious Privilege
The current debate is not new; it is the latest chapter in a long-running saga concerning Germany’s inheritance tax. The Federal Constitutional Court has previously upheld the fundamental principle of privileging business assets, recognizing the legitimate state interest in preventing the forced sale of companies to cover tax liabilities, thereby protecting jobs and economic stability. A landmark decision in 2014, for instance, affirmed this principle but simultaneously demanded reforms to curb excessive exemptions, particularly for large fortunes, leading to the 2016 reform that is now under scrutiny.
The 2016 reform aimed to strike a balance, introducing mechanisms like the "Verschonungsbedarfsprüfung" (need-based exemption). This provision allows heirs inheriting business assets exceeding 26 million euros to be fully exempt from inheritance tax if they can demonstrate that their other private assets are insufficient to cover the tax burden. While seemingly designed to prevent genuine hardship, this clause has become a focal point of criticism.
Adding another layer of complexity is the contentious "300-apartment rule" for housing companies. This administrative guideline, which treats companies managing more than 300 residential units as legitimate business operations, thereby qualifying them for inheritance tax exemptions, has been a source of significant legal and public outcry. In 2017, the Federal Fiscal Court (Bundesfinanzhof) explicitly rejected this arbitrary numerical threshold, arguing that the nature of the business—whether it provides services beyond mere property management—should be the decisive factor. However, in a move that underscored the political sensitivity and financial stakes, state finance ministries issued a "non-application decree" in 2018, effectively instructing tax authorities to continue applying the 300-apartment rule, directly circumventing the higher court’s interpretation.
This history reveals a continuous tension between the legislative desire to support business continuity, the judiciary’s mandate to ensure constitutional equality, and the administrative realities of tax collection. The current hearing is therefore not just about interpreting the 2016 reform but potentially re-evaluating the entire framework of business asset privileges in the context of fairness and fiscal responsibility. A verdict is not expected for several months, but the oral arguments have already illuminated the profound significance of this question for Germany’s economic structure, its political parties, and the broader perception of social justice.
Supporting Data and the "Making Oneself Poor" Phenomenon
The figures cited by Hamburg’s Finance Senator Andreas Dressel are just one indicator of the substantial financial impact of the current inheritance tax regime. The loss of €857 million for a single city-state since 2016 underscores the magnitude of the tax revenue foregone nationally. While specific nationwide annual figures tied to the 2016 reform were not explicitly detailed in the original text, the mention of "2025 wurden 3,7 Milliarden Euro erlassen" (though likely a typo for an earlier year or a projection, pointing to billions in exemptions) highlights that the total volume of exempted business assets runs into the billions of euros annually. Such significant exemptions inevitably lead to shortfalls in public coffers, which could otherwise be invested in public services, infrastructure, or education.
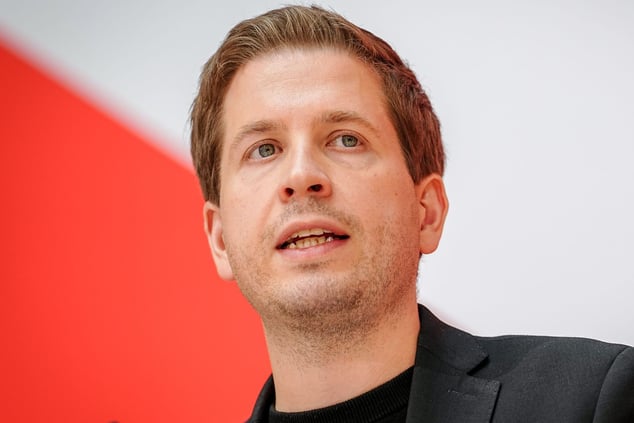
One of the most vocal criticisms leveled against the "Verschonungsbedarfsprüfung" is its alleged susceptibility to manipulation, allowing heirs to strategically "make themselves poor" to qualify for full tax exemption. Kevin Kühnert, the former SPD General Secretary who now works with the civic movement Finanzwende, articulated this concern clearly in Karlsruhe. He asserted that the exemption, as it has existed since 2016, "invites making oneself poor."
Kühnert elaborated on how this mechanism functions: "The legal rule," he argued, "no longer asks what is necessary to protect companies and jobs, but only whether the entrepreneur is liquid." This distinction is crucial. If an heir prepares for the inheritance by shifting liquid assets to other entities, such as closed private foundations, before the cut-off date, their personal liquidity might appear insufficient to cover the tax, thereby triggering the full exemption for the business assets. This effectively cancels the tax liability without genuinely endangering the company’s operational capacity or jobs. "That upsets many people," Kühnert concluded, pointing to the public’s strong sense of injustice when large fortunes appear to escape taxation through such maneuvers.
Independent experts corroborate this view. Swen Bäuml, a professor of tax law who advises entrepreneurial families on asset structuring and succession, confirmed the potential for comprehensive tax exemptions. "Anyone who structures their assets correctly, i.e., has a low administrative asset ratio, can, by law, transfer even multi-billion-euro business assets tax-free," Bäuml explained. This illustrates how sophisticated financial planning can legally navigate the current system to minimize or eliminate inheritance tax, especially for very large estates. The core issue, critics contend, is that the law focuses on the heir’s immediate liquidity rather than the overall value and nature of the inherited assets, thereby undermining the principle of equal treatment.

Official Responses and Divergent Perspectives
The debate surrounding inheritance tax privileges for business assets pits fundamental economic arguments against principles of social justice and fiscal equity. Representatives from industry and business associations have voiced strong opposition to any significant reform that would diminish these privileges, arguing that they are essential for Germany’s economic health.
Rainer Kirchdörfer, a board member of the Stiftung Familienunternehmen (Foundation for Family Businesses), dismissed the reported tax loss figures as misleading. He contended that "business assets are not cash in the bank, but are tied up in machinery, patents, and buildings." This perspective emphasizes the illiquid nature of business wealth, suggesting that taxing it heavily could force companies to sell off productive assets, jeopardizing their operations, investments, and ultimately, employment. For family businesses, which form the backbone of the German economy, maintaining continuity across generations without excessive tax burdens is paramount.
Monika Wünnemann of the Federation of German Industries (BDI) echoed these concerns, explicitly defending the current system. "The differences in the taxation of business assets and private assets are factually justified," Wünnemann stated. She argued that inheritance tax must typically be paid out of company profits, which would then weaken the company’s investment capacity. In an environment of increasing global competition, she warned, such a weakening could have detrimental effects on Germany’s industrial base and its ability to innovate and create jobs. The BDI’s stance is clear: preserving the current exemptions is vital for economic stability and growth.

On the other side, proponents of reform, including the plaintiff in the current case and organizations like Finanzwende, argue that the current system creates an unacceptable imbalance. The plaintiff, who inherited a securities portfolio and real estate and faced a €50,000 tax bill, feels unfairly disadvantaged compared to heirs of large corporations who might pay nothing. This sentiment taps into a broader public desire for fairness and equal treatment under the law.
The Contentious "300-Apartment Rule"
Another significant point of contention before the Constitutional Court is the privilege extended to large housing companies. The plaintiff’s representative sharply criticized this discrepancy, highlighting the absurdity of taxing the inheritance of three private apartments while 300 (or more) units held by a corporate entity might be tax-exempt.
The current practice in Germany’s tax administration generally assumes that if a company holds more than 300 residential units, it constitutes a genuine business operation rather than mere asset management. Consequently, these apartments are classified as "Betriebsvermögen" and can benefit from the same inheritance tax exemptions as a factory or a machinery park.

Professor Swen Bäuml vividly illustrated this perceived injustice: "Whoever inherits three properties privately pays a significant tax on their market value, quickly a very high one in Munich or Frankfurt. Whoever inherits more than 300 units in the same metropolitan areas, however, pays nothing due to the provided material tax exemptions." This highlights a significant loophole where the scale of asset ownership, when structured corporately, can lead to vastly different tax outcomes compared to individual ownership, regardless of the underlying asset type.
The legal incongruity is further exacerbated by the fact that the Bundesfinanzhof (Federal Fiscal Court), Germany’s highest court for tax matters, explicitly rejected the 300-apartment threshold in 2017. The Munich judges ruled that the sheer number of apartments was irrelevant. Instead, they emphasized that the crucial factor should be whether a company provides services beyond ordinary rental and administration, such as cleaning, security, or hotel-like services. According to the court, merely collecting rent, whether for 50 or 5,000 apartments, constitutes asset management, not an active business operation qualifying for special tax privileges.
Despite this clear judicial pronouncement, the state finance ministries chose to disregard it. In 2018, they issued a "non-application decree," effectively instructing tax offices to continue adhering to the 300-apartment rule. This executive decision to override a higher court’s interpretation has fueled accusations of political interference and further deepened the controversy, demonstrating a willingness by authorities to maintain a system that critics argue is fundamentally unfair and legally questionable.

Broader Implications and Political Ramifications
The upcoming ruling from the Federal Constitutional Court on inheritance tax will have far-reaching implications across Germany. For thousands of family businesses, the decision could bring either greater legal certainty or necessitate significant restructuring of their succession planning. While the core principle of protecting businesses and jobs is likely to be reaffirmed, the specific extent and conditions of exemptions, particularly for large fortunes and complex asset structures, could be severely curtailed. Any tightening of the rules would require businesses to re-evaluate their financial strategies, potentially increasing their tax burden and impacting their ability to invest and grow.
Politically, the ruling arrives at a highly sensitive time. The current governing coalition, comprising the Social Democrats (SPD) and the Union (CDU/CSU), is already navigating deep divisions and facing significant public scrutiny. The SPD, traditionally advocating for greater social justice and wealth redistribution, has often pushed for stricter inheritance tax rules, aligning with the sentiments expressed by figures like Andreas Dressel and Kevin Kühnert. Conversely, the Union parties (CDU/CSU) are strong proponents of family businesses and often argue against reforms that they believe would burden entrepreneurs and undermine economic stability.
A ruling that significantly limits the current exemptions could be seen as a victory for the SPD’s progressive wing but would likely trigger strong resistance from the Union and business lobbies. Conversely, a decision that largely upholds the status quo might disappoint the SPD’s base and civic movements, fueling public discontent over perceived wealth inequality and tax unfairness. This makes the issue a potential flashpoint that could further strain an already fragile political alliance and influence upcoming election campaigns.

Beyond party politics, the case touches upon fundamental questions about the nature of wealth, responsibility, and the social contract in a modern economy. The court’s decision will either reinforce existing perceptions of a two-tiered tax system – one for private individuals and another, more lenient one, for large corporate and business assets – or it could usher in a new era of greater equity and transparency in Germany’s tax landscape. Regardless of the outcome, the debate over inheritance tax is set to remain a defining issue in Germany’s ongoing discussion about economic justice and the future of its social market economy.