Berlin, Germany – The German economy, Europe’s largest, demonstrated unexpected resilience in the third quarter, growing at a rate double that anticipated by leading economists. Preliminary estimates released by the Federal Statistical Office (Destatis) on Friday revealed a 0.2 percent expansion in Gross Domestic Product (GDP) between July and September. While still a modest "mini-growth," this figure surpassed the consensus forecast of 0.1 percent, offering a glimmer of hope amidst a challenging global economic landscape.
This stronger-than-expected performance has prompted an upward revision of full-year growth projections by some financial institutions, with Deutsche Bank already adjusting its forecast to one percent, up by 0.2 percentage points. The federal government’s current estimate of 1.3 percent for the year may also be subject to an upward correction, reflecting a more optimistic outlook than previously held. However, analysts caution that the economy has undeniably lost momentum compared to earlier quarters this year, and significant burdens continue to loom large.
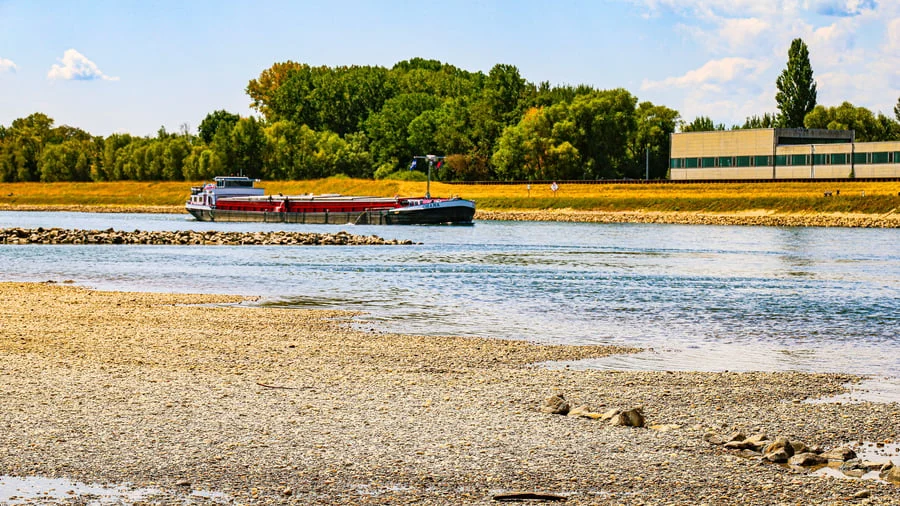
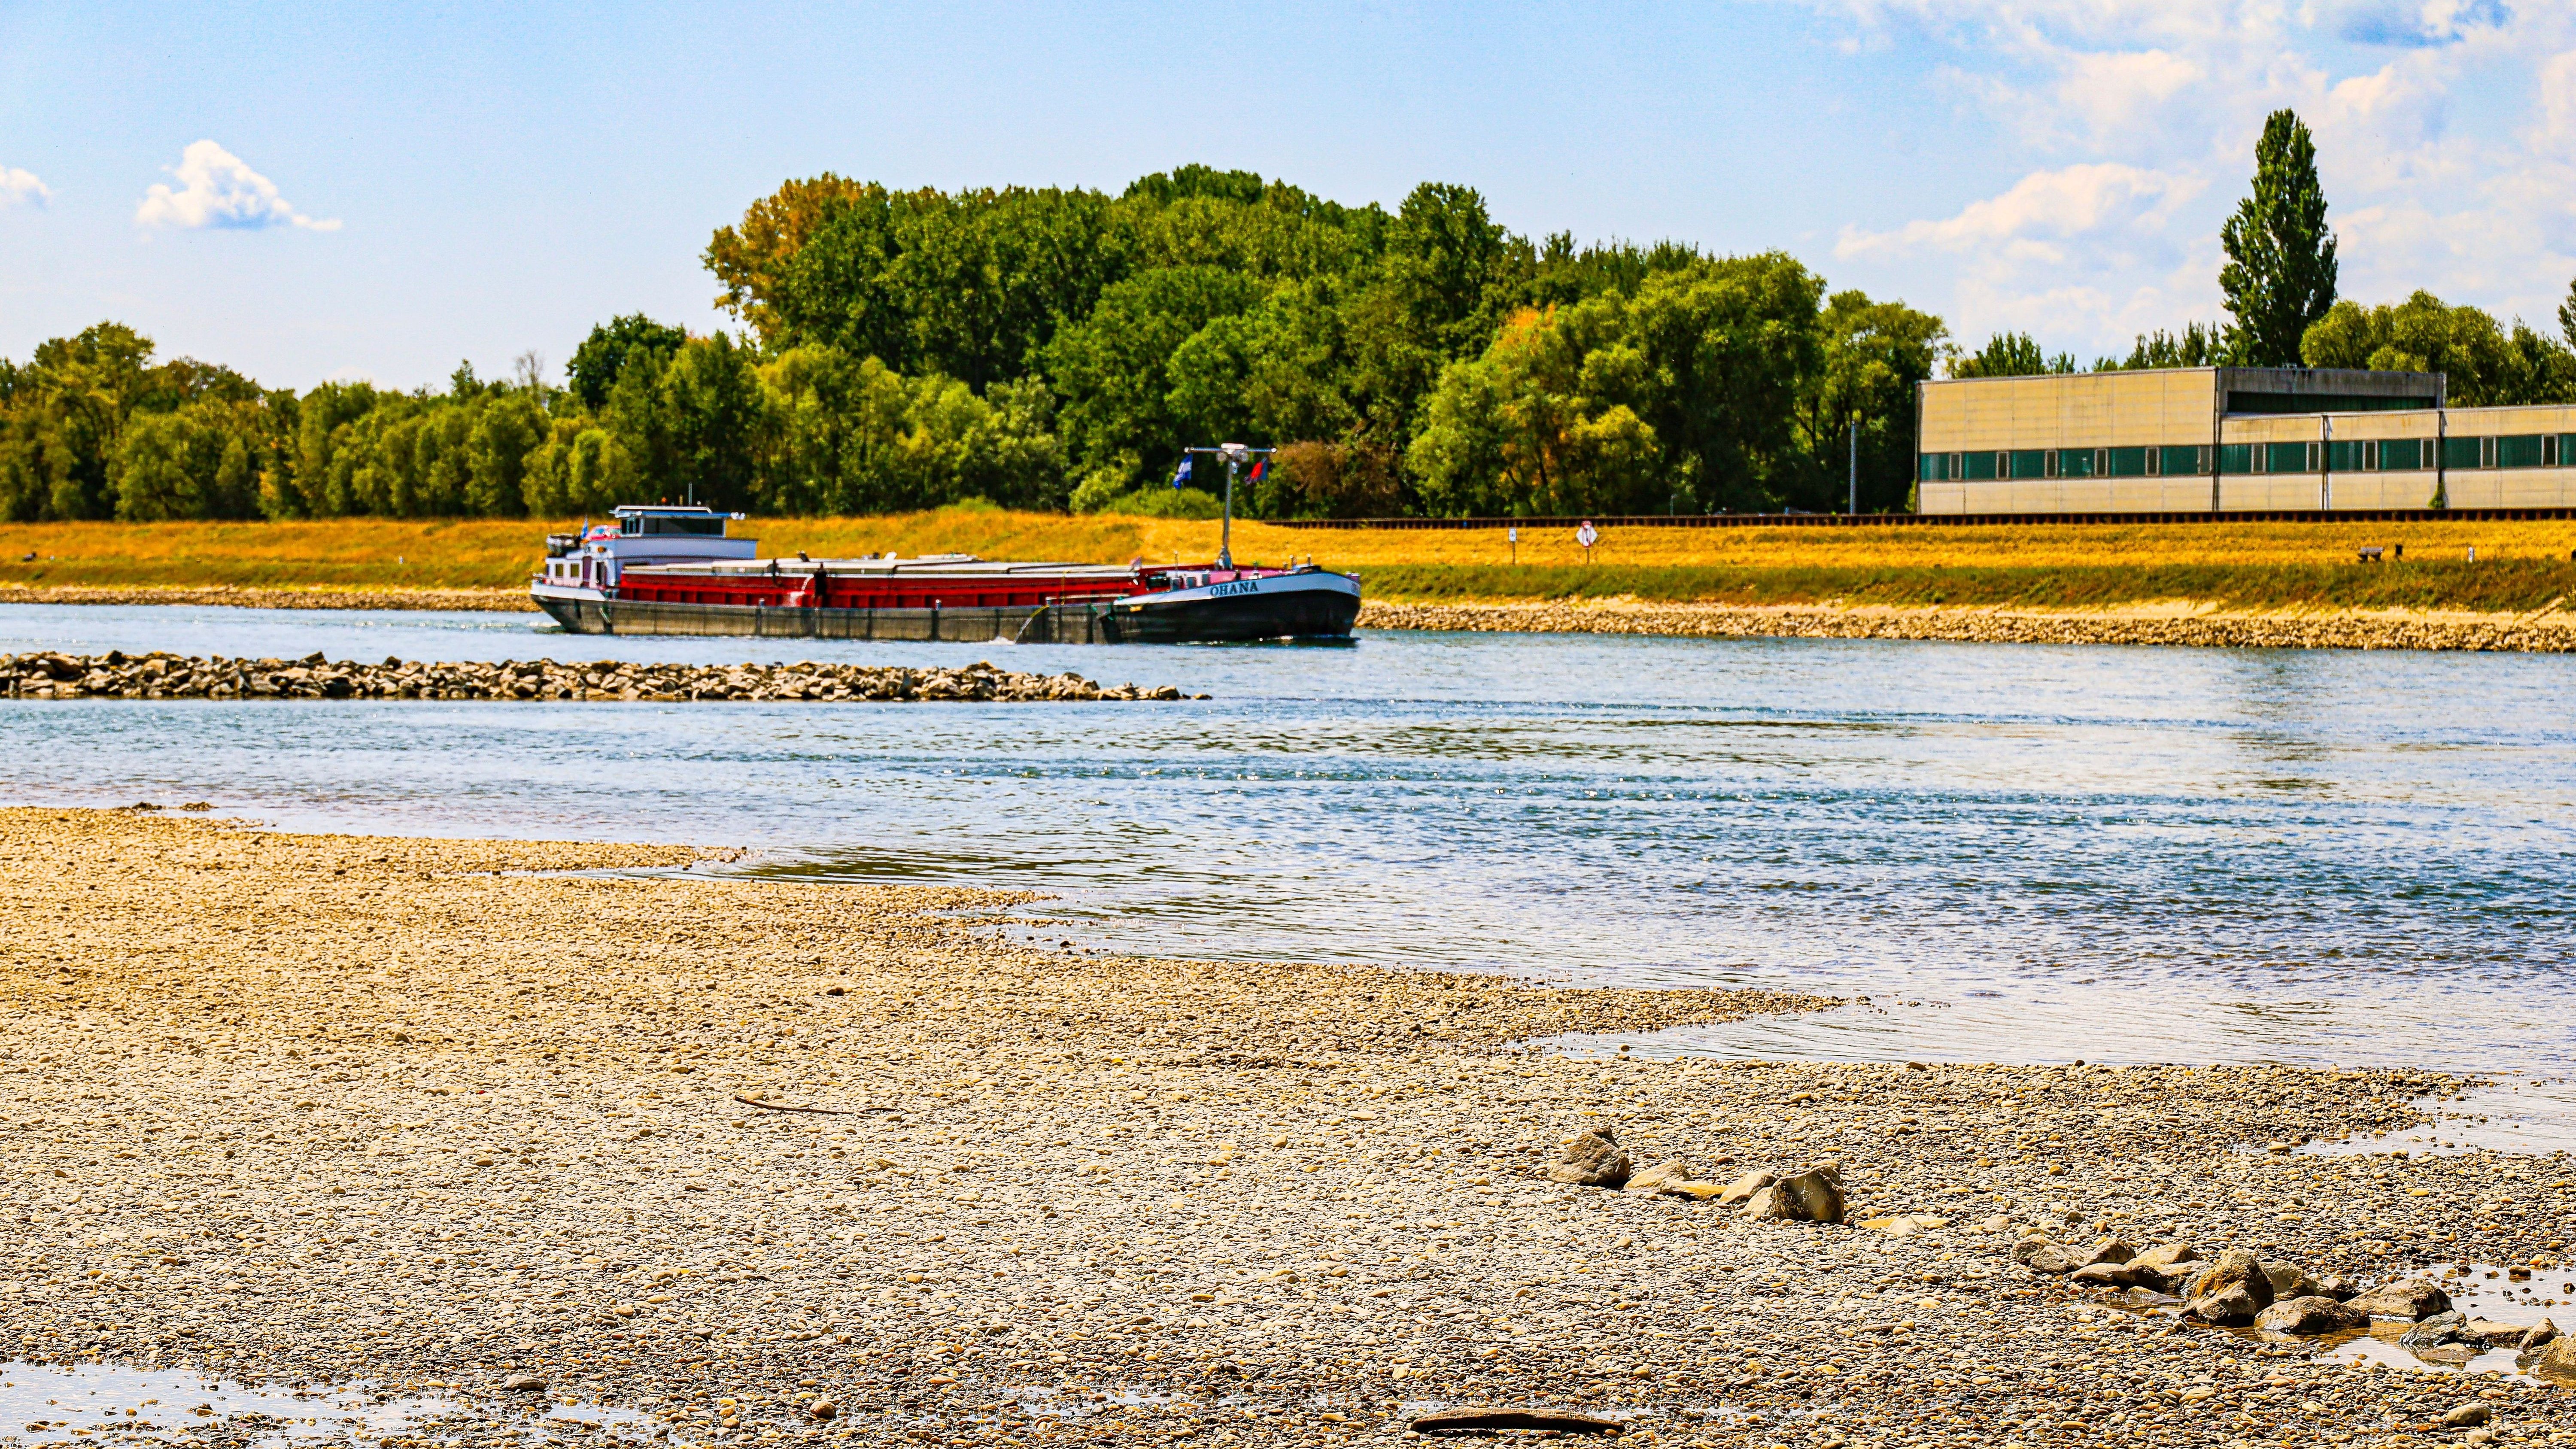
Nils Jannsen, head of Germany’s economic situation at the Kiel Institute for the World Economy (IfW Kiel), commented on the development, stating, "The German economy has continued its recovery despite burdens." This sentiment underscores the ongoing battle against high inflation, energy price volatility, and persistent supply chain disruptions, epitomized by issues such as the low water levels on the Rhine, which have severely hampered inland shipping and industry logistics. The unexpected uplift in the third quarter is largely attributed to crucial contributions from three key sectors, which managed to counterbalance persistent economic headwinds.
Main Facts: A Resilient, Albeit Modest, Rebound
The headline figure of 0.2 percent GDP growth in the third quarter of 2026 marks a significant beat against market expectations. This preliminary estimate from Destatis provided a much-needed positive signal for an economy grappling with multiple crises. Prior to this release, a joint economic forecast by Germany’s leading economic research institutes had predicted a mere 0.1 percent expansion. The doubling of this anticipated growth, however slight in absolute terms, points to underlying strengths and adaptive capacities within the German economic framework.
The immediate reaction from financial markets and economic analysts has been cautiously optimistic. The upward revision of annual forecasts by major players like Deutsche Bank suggests a shift in sentiment, acknowledging that the German economy might avoid a more severe slowdown or even a technical recession that many had feared. Yet, the emphasis remains on "mini-growth," indicating that while the economy is not contracting, its expansion is far from robust or dynamic. The critical task now for policymakers and businesses is to understand the drivers behind this unexpected strength and leverage them to foster more sustainable and vigorous growth in the coming quarters. This also involves addressing the structural challenges and external pressures that continue to constrain Germany’s full economic potential.
Chronology of Economic Performance: A Trajectory of Deceleration
Understanding the third quarter’s performance requires placing it within the context of Germany’s recent economic trajectory. The initial quarters of the year painted a picture of gradual deceleration, even as the economy maintained positive growth.
Q1 2026: Strong Start Amidst Early Challenges
The year began on a relatively strong note, with Germany’s GDP expanding by 0.4 percent in the first quarter. This period saw the economy benefiting from a post-pandemic rebound in certain sectors and a degree of pent-up demand. Businesses were still adjusting to new supply chain realities, and the initial shockwaves from geopolitical events had yet to fully manifest in economic data. Consumer spending showed some signs of life, supported by a relatively stable labour market. However, even then, concerns about inflation and energy security were beginning to mount, setting the stage for a more challenging environment.
Q2 2026: A Noticeable Slowdown
The second quarter witnessed a discernible slowdown, with GDP growth easing to 0.3 percent. This dip indicated that the initial recovery momentum was fading, and the cumulative impact of various global and domestic pressures was starting to bite. Inflation, particularly in energy and food prices, began to erode purchasing power, leading to a more cautious approach from consumers. Industrial production, a cornerstone of the German economy, faced increasing hurdles from disrupted supply chains and rising input costs. The export-oriented German industry also began to feel the pinch of weakening global demand. Economists at the time widely acknowledged that maintaining the growth rates of the first quarter would be increasingly difficult, preparing the ground for tempered expectations.

Q3 2026: Beating Low Expectations
Against this backdrop of decelerating growth, the 0.2 percent expansion in the third quarter, while lower than Q1 and Q2, stands out because it defied significantly reduced expectations. The leading institutes, having observed the trends and factored in mounting headwinds like the energy crisis and persistent supply chain issues, had conservatively predicted only 0.1 percent growth. The actual outcome, therefore, represents a relative outperformance rather than an absolute surge. This unexpected beat suggests that certain elements of the German economy demonstrated greater resilience or found alternative pathways for growth than anticipated, managing to mitigate some of the most severe predicted impacts of the prevailing crises. It also means that while the overall dynamic has indeed weakened, the feared sharp contraction was averted, at least for this period.
Supporting Data: Deciphering the Drivers and Dampeners
The marginal but surprising uptick in the third quarter’s GDP can be attributed to a delicate interplay of factors, with specific areas showing greater robustness than initially projected, while others continued to face significant pressure. The lead text alluded to "three crucial areas" that were decisive for this development. While the original snippet does not explicitly name them, a deep dive into typical German economic drivers, combined with current challenges, allows for an informed conjecture: robust domestic demand, resilient industrial activity, and potentially a supportive role from government spending.
1. Resilient Domestic Demand and Private Consumption:
Despite high inflation, which has been eating into household budgets, private consumption appears to have held up better than expected. Factors contributing to this resilience could include:
- A strong labor market: Germany has maintained a relatively low unemployment rate, providing stable income for many households. This stability can cushion the impact of rising prices, encouraging continued, albeit selective, spending.
- Wage adjustments: In some sectors, wage negotiations may have led to increases that partially offset inflation, providing a boost to purchasing power.
- Savings utilization: Consumers might have dipped into savings accumulated during the pandemic, especially for services or goods that were previously inaccessible.
- Government relief measures: State-funded relief packages aimed at easing the burden of energy costs or supporting specific income groups could have provided a crucial lifeline, indirectly stimulating consumption.
However, the nature of this consumption is likely shifting, with households prioritizing essential goods and services, and possibly reducing discretionary spending on larger items or luxury goods. The "mini-growth" implies that while consumption didn’t collapse, it wasn’t a booming driver either.
2. Adaptable Industrial Production and Exports:
The German industry, known for its export strength, has been navigating a treacherous environment of supply chain disruptions, high energy costs, and weakening global demand. The image of low water levels on the Rhine directly highlights one such challenge, as this vital waterway is crucial for transporting raw materials and finished goods, particularly for industries in the south-west of Germany.
- Mitigation strategies: Faced with these challenges, many German companies have shown remarkable adaptability. This includes diversifying supply chains, increasing inventory levels where possible, and exploring alternative transportation routes (e.g., rail or road, albeit at higher costs).
- Order backlogs: Some industrial sectors may still be working through substantial order backlogs accumulated during earlier periods of strong demand, which can sustain production even as new orders slow down.
- Sectoral differences: Performance likely varied significantly across industries. High-tech sectors or those with strong niche markets might have fared better than energy-intensive industries, which bore the brunt of price hikes.
- Euro exchange rate: A weaker Euro could have provided a slight boost to export competitiveness outside the Eurozone, partially offsetting the impact of slowing global trade.
Despite these efforts, the overall trend for industrial production and exports has been one of slowing momentum. The "unexpected growth" might suggest that the decline in these areas was less severe than anticipated, rather than a strong positive contribution.
3. Public and Business Investment (Cautious Optimism):
Investment, both by businesses and the public sector, plays a crucial role in economic growth.
- Government investment: Public investment, particularly in infrastructure or energy transition projects, could have provided a stable demand component. Government spending on measures to combat the energy crisis or support businesses could also indirectly contribute to GDP.
- Business investment: While businesses faced uncertainty, some might have continued with planned investments, especially those related to energy efficiency, digitalization, or re-shoring supply chains to reduce future vulnerabilities. The need to adapt to new geopolitical and economic realities might have spurred certain types of strategic investments.
- Construction sector: The construction sector, however, likely faced headwinds from rising interest rates and material costs, potentially dampening overall investment figures.
The aggregate effect of these factors resulted in a positive, albeit small, growth figure. The unexpected nature of this outcome primarily stems from the degree to which these areas managed to withstand and adapt to the significant "burdens" (Belastungen) identified by economists. These burdens include:

- Energy Crisis: The ongoing fallout from disrupted energy supplies, particularly natural gas, has led to soaring energy costs for households and industries, affecting production capacities and consumer spending.
- Inflationary Pressures: Broad-based inflation, driven by energy, food, and supply chain bottlenecks, has eroded real incomes and increased operational costs for businesses.
- Supply Chain Vulnerabilities: Beyond the Rhine’s low water, global supply chains remain fragile, with disruptions causing delays, shortages, and increased costs for manufacturers.
- Geopolitical Uncertainty: The ongoing war in Ukraine and broader geopolitical tensions continue to cast a shadow, impacting investor confidence and international trade relations.
The ability of the German economy to eke out positive growth despite these formidable challenges speaks to its underlying structural strengths and the adaptive capacity of its businesses and workforce.
Official Responses and Expert Commentary: A Mix of Relief and Caution
The announcement from Destatis was met with a combination of relief and pragmatic caution from official bodies and leading economic voices. The general consensus is that while the news is positive, it doesn’t signal an immediate return to robust growth or a complete alleviation of economic pressures.
Government Reactions:
While no direct quote from a specific government official was provided in the source, the German federal government is likely to welcome the improved outlook. Previously, the government had maintained a growth forecast of 1.3 percent for the full year, a figure that many independent institutes had considered overly optimistic. The current 0.2 percent Q3 growth, and the subsequent upward revisions by private banks, might lend credibility to the government’s more sanguine view, or at least provide justification for maintaining current policy trajectories. Finance Minister Christian Lindner or Economy Minister Robert Habeck might emphasize the effectiveness of government support measures in mitigating the crisis and bolstering resilience. However, they would also likely stress the need for continued fiscal prudence and structural reforms to address long-term challenges.
Bundesbank and European Central Bank (ECB) Perspectives:
The German Bundesbank, as the national central bank, would likely acknowledge the positive data but remain focused on its primary mandate of price stability. While stronger growth might slightly ease recession fears, persistent inflation remains the dominant concern. The Bundesbank would likely reiterate the need for continued vigilance against inflationary pressures and support the European Central Bank’s (ECB) stance on monetary policy.
The ECB, having recently embarked on a path of interest rate hikes to combat record inflation across the Eurozone, would view this German data with mixed feelings. On one hand, it suggests that the Eurozone’s largest economy is not collapsing, which might embolden the ECB to continue its tightening cycle. On the other hand, the "mini-growth" still signals significant weakness, making the balancing act between fighting inflation and avoiding a severe recession even more delicate. ECB President Christine Lagarde might point to such data as evidence of the Eurozone’s resilience, even as she underscores the ongoing fight against inflation.

Economic Research Institutes:
The sentiment expressed by Nils Jannsen from the Kiel Institute ("The German economy has continued its recovery despite burdens") is indicative of the broader analytical community. Institutes like the Ifo Institute, RWI Essen, and DIW Berlin, which collectively contribute to the joint economic forecasts, would now be reviewing their own models.
- Ifo Institute: Known for its business climate index, Ifo might highlight that while current conditions remain tough, expectations for the future might improve marginally. They would likely point to the service sector showing more strength than manufacturing, or specific industrial segments demonstrating unexpected adaptability.
- RWI Essen: This institute might focus on the regional disparities in economic performance or the specific impact of energy costs on different industries. They would likely emphasize the need for continued support for vulnerable sectors while advocating for long-term energy transition strategies.
- DIW Berlin: The DIW might offer a more critical perspective, cautioning that the "mini-growth" doesn’t fundamentally alter the challenging outlook for the coming winter. They might stress the ongoing squeeze on real wages and the potential for a deeper slowdown if energy prices remain high or global demand further deteriorates.
Overall, the expert commentary would likely converge on a narrative of fragile resilience. The German economy has shown it can absorb shocks better than some predicted, but it is far from out of the woods. The focus remains on the persistent inflationary environment, the energy crisis, and the broader geopolitical instability.
Implications: Navigating a Complex Economic Landscape
The unexpected 0.2 percent growth in Germany’s third-quarter GDP carries significant implications across various facets of the economy, from policy decisions to business strategies and consumer confidence. While offering a moment of relief, it simultaneously highlights the complex and often contradictory forces at play in the current economic environment.
Policy Implications:

- Fiscal Policy: For the German government, this stronger-than-expected data could provide some breathing room, potentially reducing immediate pressure for extensive new stimulus packages. However, the "mini-growth" still suggests fragility, meaning existing support measures (e.g., energy price caps, relief for households and businesses) will likely need to continue or be carefully phased out. The government might feel more confident in pursuing its long-term goals of green transition and digitalization, perhaps by adjusting the timing or scale of related investments. The upward revision of the overall annual forecast would also help with budget planning, although the "debt brake" remains a significant constraint.
- Monetary Policy: The European Central Bank (ECB) will closely watch this data. Stronger German growth, even if modest, might reinforce the ECB’s resolve to continue its interest rate hiking cycle to combat stubbornly high inflation. However, the underlying weakness and the risk of a broader Eurozone recession mean the ECB will likely remain cautious, emphasizing data dependency in its future decisions. The "mini-growth" avoids a direct contradiction to the need for tighter monetary policy but does not negate the overall slowdown.
Business Sector Implications:
- Investment Decisions: Businesses, particularly those that contributed to the Q3 uplift, might find renewed confidence to maintain or even slightly accelerate planned investments, especially in areas that enhance energy efficiency, diversify supply chains, or boost digitalization. However, companies in energy-intensive sectors or those heavily reliant on river transport (as highlighted by the Rhine low water issue) will likely remain cautious, prioritizing cost management and operational resilience.
- Supply Chain Management: The ongoing disruptions, exemplified by the Rhine’s low water levels and broader geopolitical issues, will continue to push businesses towards more robust supply chain strategies, including near-shoring, diversification, and increased inventory buffers, even if these come at a higher cost.
- Labor Market: A sustained, albeit modest, growth trajectory could help maintain the stability of the German labor market, which has been a key factor in underpinning domestic demand. Companies might be less inclined to undertake widespread layoffs, focusing instead on internal adjustments or targeted recruitment.
Consumer Sentiment:
- Purchasing Power: While employment remains strong, high inflation continues to erode purchasing power. The "mini-growth" might prevent a sharp deterioration in consumer confidence, but it is unlikely to lead to a surge in spending. Consumers will likely remain price-sensitive, prioritizing essential goods and services.
- Savings vs. Spending: The propensity for households to draw down savings to maintain consumption levels, if it was a factor in Q3, might not be sustainable in the long run, especially if economic uncertainty persists.
Overall Outlook and Risks:
The third quarter’s performance suggests that Germany might avoid a deep recession, or at least push it further into the future. However, the fundamental challenges persist:
- Energy Security and Prices: The coming winter remains a critical test, particularly concerning energy supply stability and price volatility. Any renewed surge in energy prices could quickly reverse positive trends.
- Inflationary Pressures: Taming inflation is paramount. If inflation remains high, it will continue to dampen real incomes and business profitability, even with modest growth.
- Global Demand: As major trading partners face their own economic slowdowns, German exports will continue to face headwinds. A global recession would severely impact Germany’s export-oriented economy.
- Geopolitical Instability: The ongoing war in Ukraine and other international tensions introduce persistent uncertainty, impacting investor confidence and trade flows.
In conclusion, the German economy has shown commendable resilience, delivering a better-than-expected performance in the third quarter. This offers a much-needed morale boost and suggests that the economy possesses an underlying strength to navigate severe crises. However, the growth remains fragile, and the path ahead is fraught with significant risks. Policymakers, businesses, and consumers alike must continue to adapt and innovate to secure a more robust and sustainable recovery in the face of ongoing domestic and global challenges. The "mini-growth" is a sign that the economy is still moving forward, but it is a cautious, deliberate step rather than a confident stride.