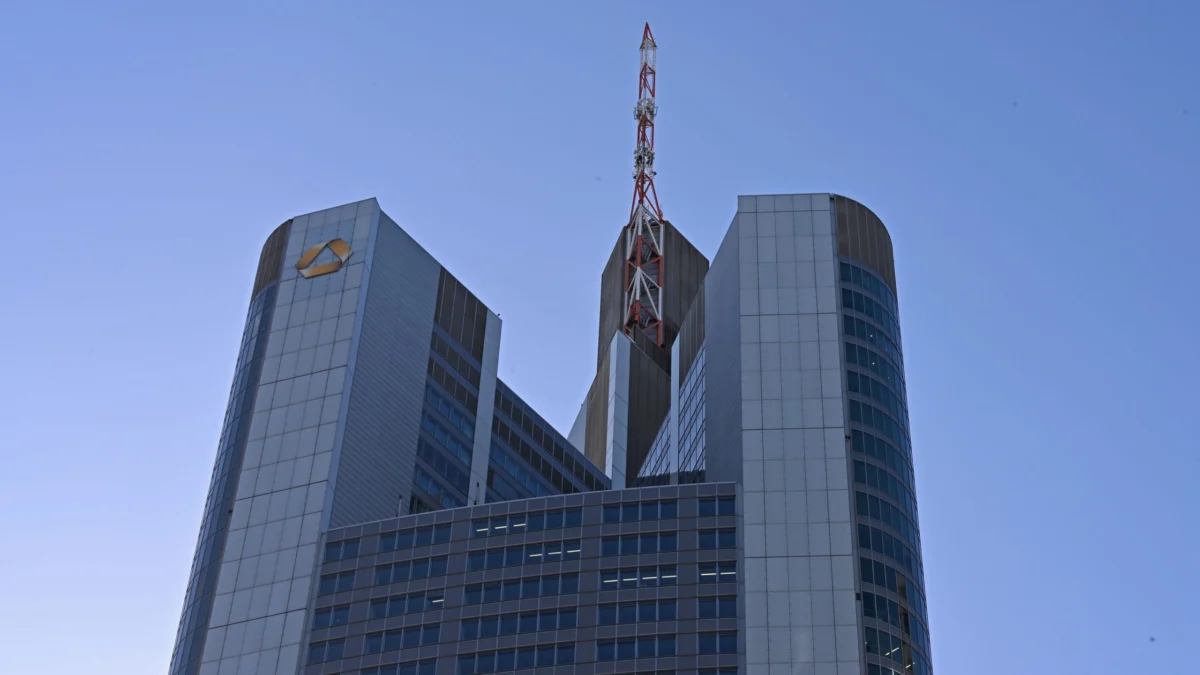
In a landmark decision that could reshape the landscape of the European financial sector, the European Central Bank (ECB) has provided its official blessing for the Italian banking giant UniCredit to significantly expand its stake in Germany’s Commerzbank. By granting regulatory approval for UniCredit to increase its shareholding beyond the 30 percent threshold—with no further upward limit—the Frankfurt-based regulator has effectively cleared the path for a potential full-scale takeover.
This move marks a watershed moment in the long-discussed consolidation of the Eurozone’s fragmented banking market. For UniCredit, the acquisition of the German lender represents an aggressive pursuit of European dominance, while for Commerzbank, it signals the potential end of its independence as a standalone German institution.
The Core Facts: A Regulatory Green Light
The announcement, delivered late Thursday evening, confirms that the ECB’s supervisory arm has deemed the proposed move acceptable. UniCredit, which has already established itself as a major shareholder with a stake approaching 30 percent, now possesses the regulatory clearance to acquire a controlling interest.

Beyond the existing stake, UniCredit has already secured the rights to an additional 20 percent through complex financial derivatives and takeover offers executed over the summer months. This regulatory approval transforms these financial preparations from theoretical maneuvers into a practical, actionable blueprint for a total takeover. The bank is now free to pursue further shares on the open market or launch a formal, comprehensive takeover bid for the remaining equity, subject to standard market conditions.
A Chronology of the Takeover Pursuit
The journey to this moment was neither swift nor straightforward. The timeline of the UniCredit-Commerzbank saga reflects a broader trend of cross-border consolidation in the EU.
- Early 2024: Market rumors began to circulate regarding UniCredit’s interest in expanding its footprint in Germany, a market where it has maintained a presence through its subsidiary, HypoVereinsbank.
- The Summer Surprise: In a bold move, UniCredit revealed it had acquired a 9 percent stake in Commerzbank, quickly followed by the tactical use of financial instruments to secure an additional 20 percent.
- The "Hostile" Narrative: The initial acquisition was met with skepticism and resistance from German political circles and Commerzbank’s own management, leading to a period of intense public debate over "national champions" versus "European integration."
- Regulatory Scrutiny: Throughout the autumn, the ECB’s supervisory board, led by Claudia Buch, conducted an exhaustive review of the proposed increase in ownership.
- The November Decision: The ECB’s approval, granted this week, marks the definitive end of the "wait-and-see" phase. The regulatory body has essentially declared that the consolidation of these two major entities poses no systemic risk that would preclude a merger.
Supporting Data and Financial Context
To understand the magnitude of this deal, one must look at the balance sheets involved. Commerzbank, once the bedrock of German corporate and retail banking, has undergone a grueling multi-year restructuring process. Its return to profitability and its improved capital ratios made it an attractive target for a predator like UniCredit, which has been one of the most profitable banks in Europe under the leadership of CEO Andrea Orcel.

UniCredit’s strategy hinges on "synergy." By integrating Commerzbank, UniCredit aims to leverage its digital infrastructure and cross-border lending capabilities across two of Europe’s largest economies—Germany and Italy. Analysts estimate that the combined entity would possess a balance sheet and market capitalization capable of challenging the dominant global giants, such as JPMorgan Chase or HSBC, within the European context.
Furthermore, the "cost of control" remains a significant variable. While the ECB has cleared the way, the acquisition will not be cheap. Should UniCredit proceed with a full tender offer, it will likely have to pay a substantial premium above the current market price of Commerzbank shares, potentially impacting the short-term earnings per share for UniCredit investors.
Official Responses and Stakeholder Sentiment
The reaction to the news has been polarized, reflecting the tension between market efficiency and national sovereignty.
The View from Milan
UniCredit’s official statement was one of triumph, framing the decision as a vindication of its operational strength. "The approval is a significant milestone," the bank stated. "It underscores the ECB’s positive assessment of the transaction and its confidence in UniCredit’s solvency and its strong position in the European banking sector."
The German Perspective
In Germany, the reaction has been more measured, bordering on apprehension. The German government, which still holds a remaining stake in the bank, has historically viewed the Commerzbank as a key lender to the "Mittelstand"—the small-to-medium-sized enterprises that form the backbone of the German economy. Concerns persist that a foreign-led bank might shift its focus away from these local businesses in favor of international investment banking.
The Regulator’s Stance
The ECB has remained consistent throughout this process. Representatives of the central bank have frequently voiced their support for cross-border banking mergers. They argue that a fragmented European banking system prevents the formation of a true capital markets union. By allowing this merger, the ECB is effectively putting its money where its mouth is, proving that it favors market-driven consolidation over protectionist banking barriers.

Long-Term Implications for the Eurozone
The implications of this move extend far beyond the two institutions involved.
1. The Era of European Banking Consolidation
If this merger succeeds, it will likely trigger a wave of similar activity across the continent. Smaller, regional banks that have struggled with low interest rate margins and high legacy costs may find themselves under pressure to merge to survive. The "UniCredit-Commerzbank" model could become the template for the next decade of European finance.
2. The Capital Markets Union
This move is a massive step toward the European Union’s long-term goal of a Capital Markets Union. A truly integrated European market requires banks that operate across borders as easily as they do within their home countries. By removing regulatory hurdles, the ECB is actively lowering the "friction" that has kept Europe’s financial markets smaller and less efficient than those of the United States.

3. The Future of the "National Champion"
The success of this takeover would signal the decline of the "national champion" era in European banking. For years, European governments have protected their domestic banks from foreign acquisition. This regulatory approval suggests that the EU is prioritizing a unified, competitive banking market over the sentimental or strategic value of keeping major financial institutions under domestic ownership.
4. Competitive Dynamics
For competitors like Deutsche Bank or BNP Paribas, the rise of a new, massive entity spanning Germany and Italy will necessitate a strategic response. We can expect to see increased competition in lending rates, retail banking services, and investment banking fees as the market adjusts to the new landscape.
Conclusion: A New Horizon
As the dust settles on the ECB’s decision, the focus now shifts to the boardroom of Commerzbank and the investment analysts watching the stock market. While the regulatory gate is open, the path to full control is still filled with operational challenges—integrating IT systems, harmonizing corporate cultures, and managing the potential workforce reductions that often accompany such massive mergers.

However, the precedent is set. The European banking sector is entering a period of profound transformation. Whether this leads to a more stable, efficient, and globally competitive European financial sector remains to be seen. What is clear, however, is that the era of status quo in European banking is rapidly drawing to a close. UniCredit has taken the leap; the rest of the market is now forced to choose between leading, following, or falling behind.