Have you ever looked at a local development project—a new bridge, a refurbished community center, or a digital infrastructure initiative—and wondered if the taxpayer money flowing into it from Brussels was being spent with strict adherence to the law? If you’ve felt a sense of skepticism, you might be closer to the truth than the European Commission would like to admit.
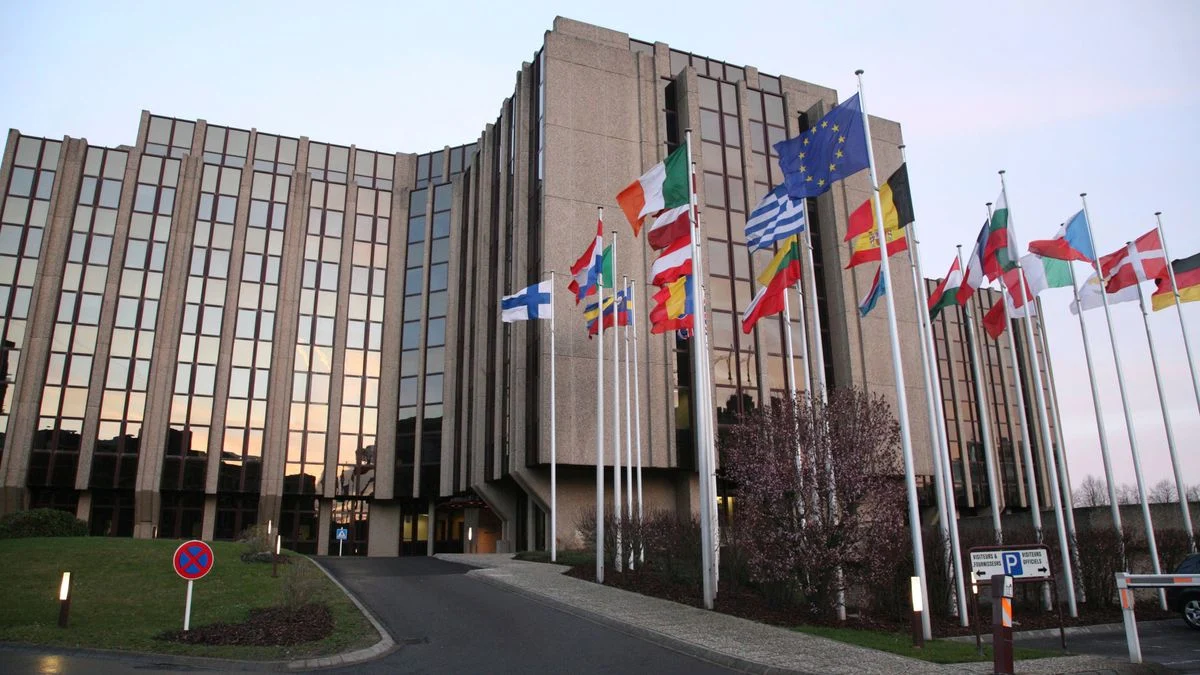
According to the latest annual report from the European Court of Auditors (ECA) based in Luxembourg, the improper expenditure of EU funds is not just an occasional administrative hiccup; it is a recurring, systemic challenge. As the EU navigates complex budgetary negotiations for the 2028–2034 period, the watchdog’s findings paint a sobering picture of fiscal mismanagement, "goal-post shifting," and mounting debt that threatens to burden future generations of European taxpayers.
The Magnitude of the Mismanagement: Key Facts
For the 2025 financial year, the ECA has estimated that 3.8 percent of total EU expenditure was affected by errors. While this figure may seem modest in isolation, the scale of the EU budget makes it a staggering sum. With total expenditures amounting to approximately 176.3 billion euros, the error rate translates to roughly 6.7 billion euros spent in violation of EU regulations.
These errors are not merely technicalities. The auditors highlight that a significant portion of these breaches involves the violation of public procurement rules—the essential legal framework designed to ensure fair competition and value for money—as well as the financing of projects that are fundamentally ineligible under existing criteria.
A Chronology of Financial Integrity
To understand the current state of affairs, one must look at the recent trajectory of EU fiscal oversight. The 3.8 percent error rate represents a slight uptick from the 3.6 percent recorded in the previous year. However, the context is vital: in 2023, the auditors reported an error rate of 5.6 percent, which stood as the highest level in over a decade.
This fluctuation reflects the growing complexity of the EU’s funding mechanisms. As the Union moves away from traditional, rule-based reimbursement models toward performance-based funding—most notably through the 650-billion-euro Corona Recovery and Resilience Facility (RRF)—the nature of the risk has shifted. The challenge is no longer just "did we follow the paperwork," but "did we achieve the results we promised?" Increasingly, the answer is a complicated "no."
The Corona Recovery Fund: A Case Study in Compliance Failures
The most pressing concern for the ECA lies in the management of the COVID-19 recovery funds. Unlike traditional EU grants, the RRF is designed to be tied to specific "milestones" and "targets." Member states are expected to submit comprehensive plans for reforms and investments, and funds are only disbursed once these benchmarks are verified.
However, the reality of implementation has been fraught with non-compliance. In their analysis of 37 disbursements made in 2025, the auditors found that nine payments—nearly one-quarter—did not meet the necessary conditions. In these instances, member states had either failed to complete the promised reforms or had ignored established procurement regulations.
This is particularly significant given that the European Commission is currently pushing for a similar performance-based model for the next long-term EU budget (2028–2034), which is expected to be worth over a trillion euros. The auditors are essentially sounding an alarm: if the EU cannot effectively police the current recovery fund, expanding this model could lead to even greater financial leakage.
"Goal-Post Shifting": How Projects Fail Upwards
One of the most damning sections of the ECA report details how member states have learned to "game" the system. President of the Court of Auditors, Tony Murphy, did not mince words in his assessment, noting that in many cases, the original, ambitious goals of a project are quietly downgraded to ensure that the money is paid out regardless of actual success.
"Essentially, the ambitions in the plans are being scaled back to ensure that the money can be paid out," Murphy remarked.
A prime example cited by the auditors involves a telemedicine application in Luxembourg. Initially, the project was promised as a broad service for the entire population. When implementation faltered and the scope narrowed significantly to only a small fraction of the intended users, the project was not deemed a failure. Instead, the Council simply approved a retrospective change to the goals.
Daniel Caspary, a German member of the Court of Auditors, characterized this practice as a dangerous precedent. "The goal was retrospectively lowered in order to reach it," Caspary noted, highlighting the moral hazard created when the gatekeepers (the Council) lower the bar to accommodate the shortcomings of the applicants (the member states).
Official Responses and the Burden of Proof
The European Commission, while acknowledging the findings, often defends the current model by pointing to the "political necessity" of the recovery funds. They argue that the focus on results is the future of European integration and that the teething problems identified by the auditors are a necessary cost of modernizing the EU’s fiscal architecture.
However, the auditors are careful to clarify what these "errors" actually are. The 3.8 percent error rate, they emphasize, is "not a measure of fraud, inefficiency, or waste." It is a measure of the amounts that were not spent in accordance with the legal requirements. Yet, for the average citizen, the distinction is thin. When money is spent on ineligible projects or through flawed procurement processes, the net result is an erosion of trust in the European project.
Long-term Implications: A Debt-Ridden Future
The fiscal outlook extends far beyond current administrative errors. The EU is currently carrying a significant debt load, which the ECA predicts could rise to as much as one trillion euros by 2027. This shift in the EU’s financing model—moving from a budget based on contributions to one based on shared debt—has profound implications for the future.
According to Caspary, the interest burden alone is becoming a massive factor in EU planning. "In the future, almost every tenth euro of the European budget will go toward debt servicing," he warned.
This reality has a direct impact on the citizens of member states, particularly those in the largest economies. Because the EU must service this debt, there is an inevitable trajectory toward higher national contributions. For Germany, the largest net contributor to the EU, this means that even if the domestic economy faces headwinds, the requirement to fund the Brussels apparatus will only grow.
Conclusion: The Need for Rigorous Oversight
The report from the European Court of Auditors serves as a critical mirror held up to the face of European institutions. It highlights a recurring tension between the desire for ambitious, large-scale investment and the capacity for administrative oversight.
As negotiations for the 2028–2034 budget intensify, the message from Luxembourg is clear: simply throwing money at reform-based objectives is insufficient if there is no robust mechanism to ensure those objectives are met honestly. Without a fundamental shift toward greater transparency and stricter accountability, the EU risks not only losing billions in "error-ridden" spending but also losing the hard-won trust of the taxpayers who fund the union.
For now, the 3.8 percent error rate remains a flashing red light on the dashboard of the European economy. Whether policymakers will heed this warning or continue to "shift the goal-posts" remains the defining question of the current legislative term.