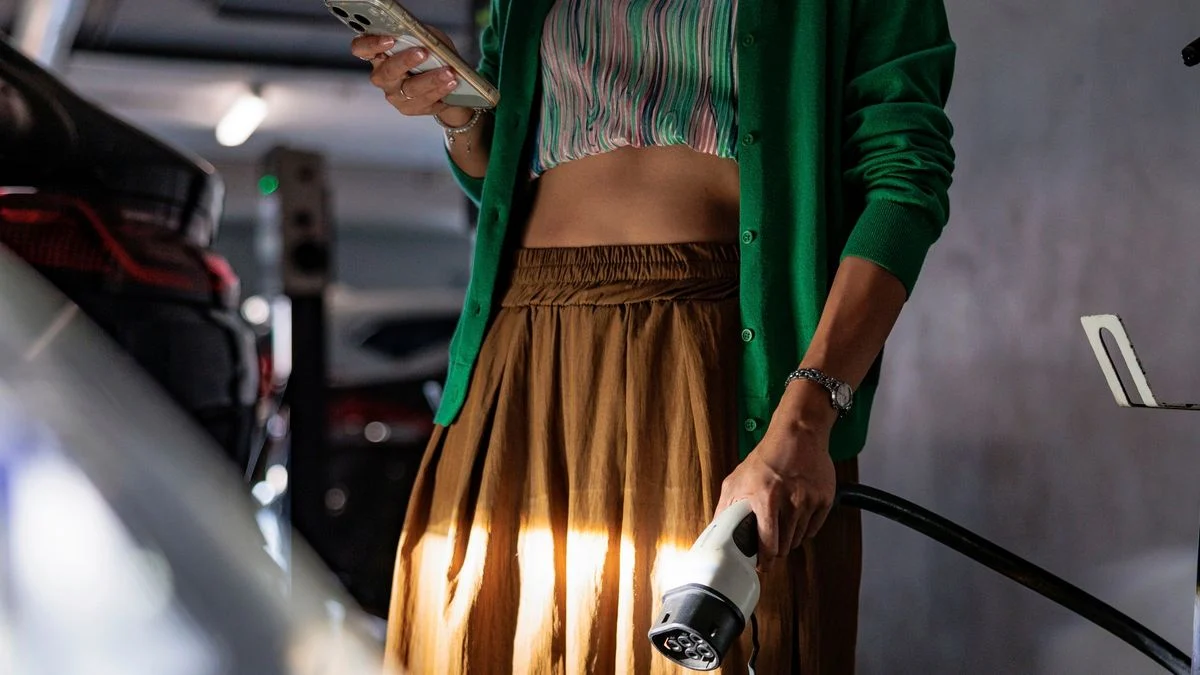
The landscape of personal mobility in Germany is undergoing a seismic shift. As the automotive industry pivots aggressively toward electrification, the barrier to entry for consumers—historically defined by high upfront costs and skepticism regarding charging infrastructure—is being dismantled. Central to this transition is the emergence of highly aggressive leasing offers that bring the cost of driving an electric vehicle (EV) below the €100-per-month threshold.
While such figures sound like marketing hyperbole, they are the result of a complex interplay between government subsidies, manufacturer inventory strategies, and the evolving secondary market for used EVs. This report dissects the mechanics of these deals, the economic realities behind them, and what they signify for the future of the German automotive sector.
The Economics of the "Sub-100" Deal
At the heart of the current leasing trend lies a sophisticated financial engineering model. Manufacturers, under pressure to meet stringent European Union fleet emission targets, are incentivized to move volume. Simultaneously, the German government’s previous support mechanisms—often referred to as the Umweltbonus (environmental bonus)—have acted as a catalyst, even as those programs face transition and reduction.
The Math Behind the Margin
To achieve a monthly rate of less than €100, several factors must align:
- Residual Value Stability: Leasing companies calculate payments based on the expected depreciation of the car. For EVs, this is the most volatile variable. High residual values allow for lower monthly payments.
- Subsidies and Grants: Many of these deals are structured to include the state’s environmental bonus as a down payment. If the government covers a portion of the vehicle’s cost, the lessor can lower the consumer’s monthly burden significantly.
- Manufacturer Incentives: Brands often subsidize the leasing rates directly to clear stock, especially during model changeovers or to avoid penalties associated with fleet-wide CO2 emissions.
Chronology of the Electric Shift
The journey toward affordable electric mobility in Germany has been incremental but steady.
- 2016–2018: The Early Adopter Phase. EVs were niche, expensive, and limited in range. Leasing offers were largely corporate-focused.
- 2020: The Pandemic Push. As the automotive market stalled, the German government introduced significantly bolstered EV subsidies to stimulate the economy. This led to the first wave of "zero-down" or "low-monthly" leasing deals.
- 2022: Supply Chain Bottlenecks. Global chip shortages meant that demand for EVs far outstripped supply. Leasing deals vanished as manufacturers focused on high-margin models.
- 2023–2024: The Inventory Correction. As production capacity recovered and consumer demand cooled due to inflation and interest rate hikes, inventory levels climbed. Manufacturers returned to aggressive promotional leasing to stimulate demand, leading to the current "under-€100" climate.
Supporting Data: Understanding the Market Dynamics
Industry analysts point to a "bottleneck effect" in the current market. According to recent data from the Kraftfahrt-Bundesamt (KBA), the registration of electric vehicles has shown a plateauing effect compared to the explosive growth seen between 2020 and 2022.
Market Indicators
- Inventory Levels: Dealer lots are currently holding record numbers of battery-electric vehicles (BEVs). This oversupply forces manufacturers to subsidize leasing rates to maintain market share.
- Interest Rate Sensitivity: Because leasing is essentially a financing product, the European Central Bank’s interest rate policy heavily impacts monthly costs. Despite higher base rates, manufacturer-backed captive banks (e.g., VW Financial Services) are absorbing interest costs to keep "headline rates" attractive.
- Total Cost of Ownership (TCO): While the €100 lease is the "hook," consumers must account for insurance, home charging costs, and maintenance. Even with these, the TCO of an entry-level EV is now frequently lower than a comparable internal combustion engine (ICE) vehicle.
Official Responses and Industry Stance
The automotive industry remains divided on the long-term viability of ultra-low leasing rates.
The Manufacturer Perspective
Major German OEMs argue that these deals are necessary to build the "EV ecosystem." By getting drivers into electric cars today, they are building brand loyalty for the next generation of software-defined vehicles. However, CFOs have privately expressed concern regarding the impact on margins. "We are essentially trading short-term profitability for long-term market compliance," noted a spokesperson for a major German manufacturer.
The Political Viewpoint
Government officials emphasize the role of these deals in reaching Germany’s climate goals. The Ministry for Economic Affairs and Climate Action has repeatedly stated that mass adoption is the only way to make the transition affordable. "If we want to hit the target of 15 million EVs on German roads by 2030, the vehicle must be accessible to the average household," a ministry representative stated during a recent energy policy summit.
Implications: The Future of Mobility
The implications of the "under-€100" era are profound, reaching far beyond the automotive sector.
1. The Death of the ICE Vehicle
As entry-level leasing makes EVs cheaper than their gasoline counterparts, the secondary market for used ICE vehicles will likely collapse in value. This creates a "pincer movement": high demand for subsidized new EVs and low demand for used combustion cars.
2. Infrastructure Pressure
The rise of low-cost leasing will drive a massive increase in the number of EVs on the road, putting unprecedented pressure on Germany’s charging infrastructure. If the speed of installation for high-power charging (HPC) stations does not match the growth in vehicle registrations, the "EV experience" for new, budget-conscious adopters may suffer, leading to long-term disillusionment.
3. Shift in Ownership Models
The success of these leasing deals suggests that the German public is increasingly comfortable with the "user-ship" model over ownership. This shift is crucial for the transition to autonomous fleets in the future. If the consumer views the car as a utility that is replaced every 24 to 36 months, the barrier to adopting robotaxi services or shared mobility platforms decreases.
4. Economic Risks
There is a potential "leasing bubble." If residual values for EVs continue to fall—driven by rapid advancements in battery technology that make older models obsolete—leasing companies may face significant write-downs. This could lead to a sudden withdrawal of these attractive offers, potentially stalling the transition if the market is not yet self-sustaining.
Conclusion: A Window of Opportunity
For the consumer, the current availability of electric vehicles for under €100 per month represents a unique convergence of manufacturing surplus, climate policy, and financial maneuvering. It is a rare window of opportunity to enter the electric market at a cost that is arguably lower than the real-world operating cost of the vehicle.
However, consumers must remain vigilant. These deals are frequently time-sensitive and tied to specific inventory clearance cycles. Before committing, potential lessees should look beyond the monthly headline rate, examining the total contract length, mileage caps, and the "exit" costs at the end of the term.
As Germany navigates the middle of this decade, the electric vehicle will continue to transition from a luxury statement to a consumer commodity. The under-€100 lease is not just a promotional tactic; it is a barometer for the entire industry’s transition. Whether this trend is sustainable or merely a temporary bridge to a more expensive, self-sustaining market remains the multi-billion-euro question for the German automotive sector.
For now, the message is clear: the electric future has arrived, and it is more affordable than many predicted—provided you are willing to embrace the lease.