PARIS/DÜSSELDORF – France, the eurozone’s second-largest economy, finds itself at a precarious crossroads. While the nation successfully avoided a formal downgrade of its sovereign credit rating by Moody’s this past Friday, the underlying economic architecture remains under intense scrutiny. As the French government grapples with mounting fiscal pressures and political instability, market participants are sounding the alarm, with yields on government bonds climbing to levels unseen in over two decades.
The Current State of French Sovereign Debt
The financial markets have sent a clear, urgent signal to Paris: the fiscal status quo is becoming unsustainable. In the most recent trading week, the yield on ten-year French government bonds (OATs) breached the five percent threshold for the first time since 2002. This surge is not merely a reflection of global interest rate trends but a localized manifestation of "France-specific" risk.
The spread—the difference between the yield on French bonds and their German counterparts, which serve as the European benchmark—has widened significantly. This gap is currently at its most expansive point since the height of the Eurozone debt crisis. Investors are demanding a higher risk premium to hold French debt, signaling a profound lack of confidence in the nation’s ability to manage its deficit and debt-to-GDP ratio effectively in the current climate.
Moody’s Decision: A Reprieve, Not a Solution
On Friday evening, the credit rating agency Moody’s provided a sigh of relief for the Élysée Palace by maintaining France’s sovereign rating at "Aa3." This remains seven notches above the so-called "junk" status, ensuring that French debt remains firmly within the investment-grade category.

However, the "stable" rating masks a volatile reality. Moody’s has maintained a "negative" outlook for the French economy. This designation suggests that while the rating is currently safe, the medium-term trajectory is downward. For institutional investors, this serves as a yellow flag: if the French government does not demonstrate a concrete path toward fiscal consolidation, a downgrade in the near future remains a distinct possibility.
Chronology of the Fiscal Standoff
The current crisis did not emerge in a vacuum; it is the culmination of years of fiscal expansion and recent political gridlock.
- 2020–2022: Like many nations, France responded to the COVID-19 pandemic with aggressive fiscal stimulus. While necessary at the time, these measures fundamentally shifted the trajectory of public debt.
- Early 2024: Concerns began to mount as the French deficit significantly outpaced the European Union’s Stability and Growth Pact guidelines.
- Mid-2024: Political instability following parliamentary elections complicated the legislative process, leaving the government with limited tools to pass necessary austerity measures.
- Late 2024: The combination of a slowing industrial base and the high-interest-rate environment imposed by the European Central Bank (ECB) began to hit French bond markets with full force.
- November 2024: The breach of the five percent yield mark on ten-year bonds triggered a wave of market volatility, leading to intense speculation regarding the potential for a credit rating downgrade.
Supporting Data and Economic Indicators
The structural weaknesses facing France are multifaceted. Firstly, the debt-to-GDP ratio has hovered stubbornly above 110 percent, a level that limits the state’s fiscal flexibility. Secondly, the structural deficit—the shortfall that remains even when the economy is at full capacity—is among the highest in the developed world.
The ING Bank, led by their senior rates strategist Padhraic Garvey, has been particularly vocal regarding the nature of this decline. In a recent analysis, the team described the current fiscal environment in France as "a slow-motion train wreck." This metaphor captures the essence of the market’s frustration: the problems are well-known and visible, yet the political mechanisms to avert a disaster seem gridlocked.
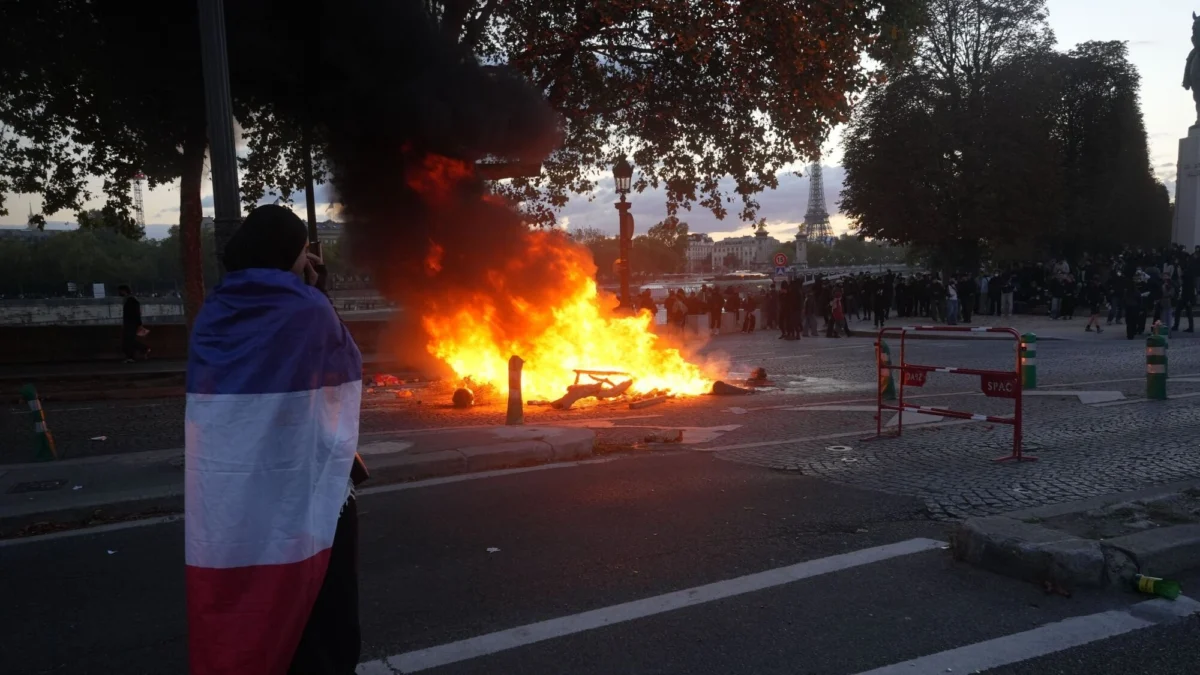
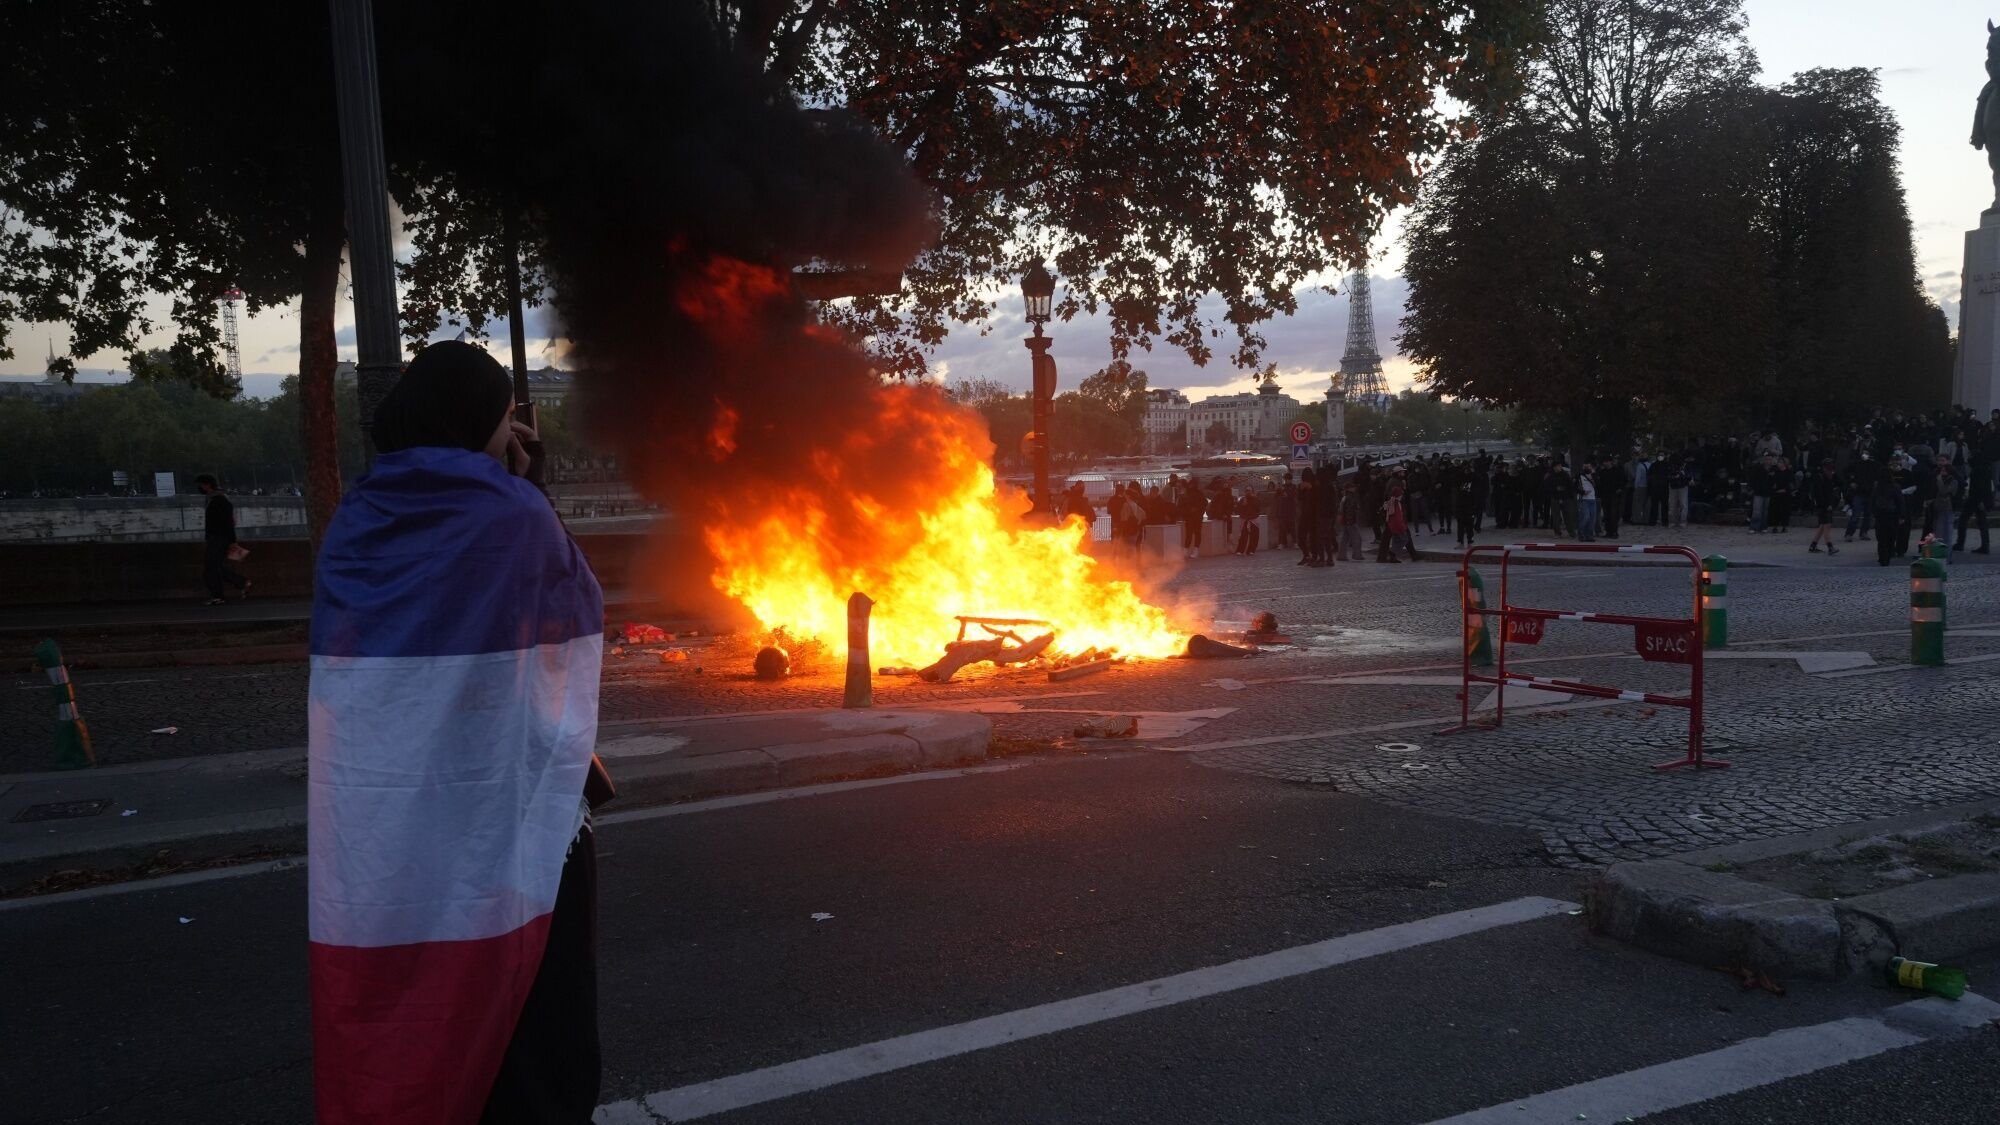
Furthermore, the recent protest movements in France, which have erupted in response to economic policy and pension reforms, have added a layer of complexity to the financial landscape. Social unrest discourages investment, complicates labor market efficiency, and makes it politically perilous for the government to cut spending or raise taxes.
Official Responses and Political Maneuvering
The French government, led by the Ministry of Finance, has consistently argued that the country’s fundamentals remain strong. Officials point to the underlying productivity of the French workforce and the government’s commitment to "re-industrialization." However, these long-term goals do little to appease bond traders looking at quarterly deficit reports.

International institutions, including the European Commission, have urged Paris to take more decisive action. Brussels has initiated an excessive deficit procedure, placing France under heightened surveillance. This puts the French government in the difficult position of having to satisfy domestic political demands for social spending while adhering to strict EU fiscal mandates.
Implications for the Eurozone
The implications of a potential French default or prolonged fiscal crisis extend far beyond the borders of France. As the second-largest economy in the currency union, France’s financial health is a pillar of the eurozone’s stability.
1. Market Contagion
If investors lose faith in French debt, the "risk-off" sentiment could easily spread to other Mediterranean economies like Italy, Spain, and Greece. This could lead to a fragmentation of the European bond market, forcing the European Central Bank to intervene, potentially through the Transmission Protection Instrument (TPI) or other unconventional liquidity measures.
2. The Credibility of the Euro
The euro is anchored by the perceived stability of its constituent members. If the sovereign debt of a major member like France is viewed as high-risk, it undermines the global status of the euro as a safe-haven currency. This could lead to long-term depreciation of the euro against the dollar and the yen, impacting inflation and purchasing power across the continent.
3. Policy Paralysis
The fiscal constraints imposed by the current debt situation mean that the French government has less room to maneuver in the event of another global shock. With limited fiscal space, France would be unable to provide the kind of support it offered during the pandemic, potentially exacerbating the impact of any future recession.
The Path Forward: Can France Stabilize?
To escape the current "negative" outlook from rating agencies, the French government must move beyond rhetoric. Economists suggest three primary pillars for recovery:
- Structural Spending Cuts: The government must address the primary drivers of the deficit, which include high levels of public sector spending and administrative overhead.
- Tax Reform: While politically difficult, a comprehensive review of the tax system to ensure competitiveness and efficiency is essential to stimulate growth.
- Labor Market Flexibility: Further reforms to the labor market could help reduce structural unemployment, which would in turn broaden the tax base and reduce the burden of social welfare spending.
Conclusion: A Delicate Balance
The decision by Moody’s to maintain France’s "Aa3" rating is a stay of execution rather than a seal of approval. The financial markets have made it clear that patience is wearing thin. The "slow-motion train wreck" mentioned by ING analysts can only be halted if the government in Paris can transcend its current political gridlock and present a credible, long-term fiscal consolidation plan.
France remains a cornerstone of the European project, but its current fiscal trajectory is unsustainable. Whether the nation can implement the necessary reforms without triggering further social unrest or political instability is the defining question of the next year. For now, the world watches as Paris tries to balance the books while the ground beneath them continues to shift. The reprieve granted by Moody’s provides a brief window—a critical moment for the French administration to prove that the "train" can still be steered away from the edge.