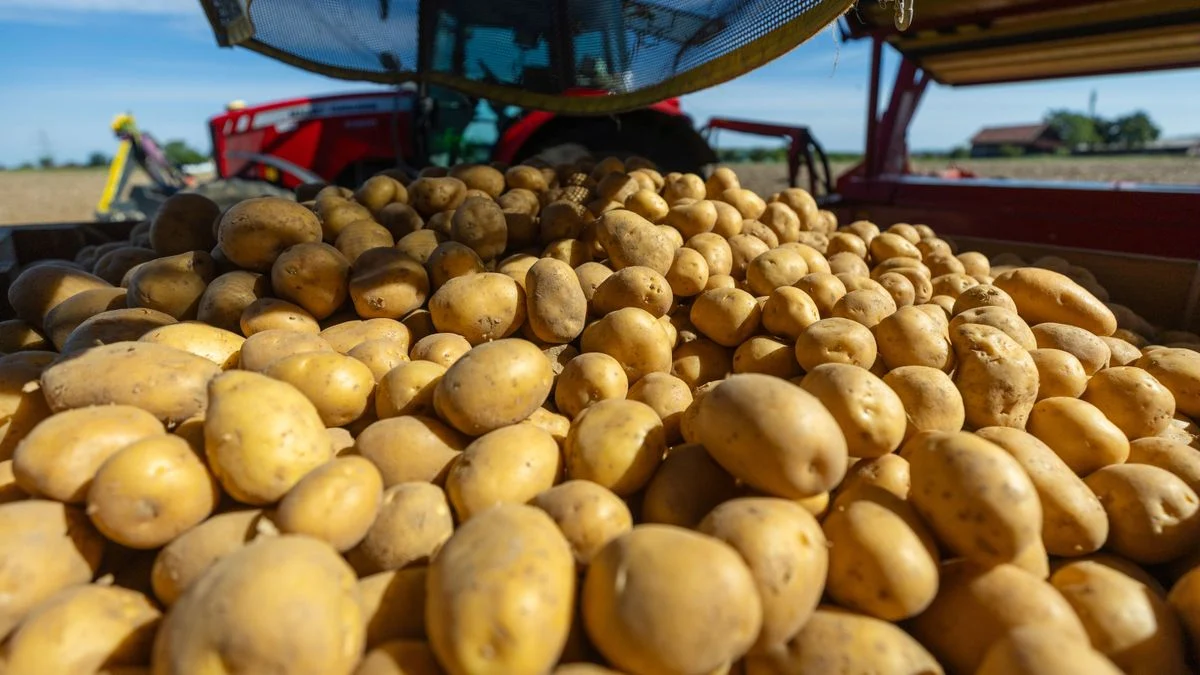
The humble potato, a cornerstone of the German culinary identity and a staple in millions of households, has become the latest protagonist in a sobering economic narrative. As inflation figures stabilize across various sectors, the potato market is bucking the trend, with prices surging at a rate that significantly outpaces the general cost of living. According to recent data from the Federal Statistical Office (Destatis), consumers in September were forced to pay 11.3% more for fresh potatoes compared to the same month last year. This sharp uptick serves as a stark reminder of how climate volatility and agricultural planning directly translate into the financial pressures felt at the supermarket checkout.
The Mechanics of a Supply-Side Crisis
The current market reality is not the result of a single economic anomaly but rather the convergence of multiple agricultural setbacks. After a bumper year in 2024, where the harvest yielded a robust 13.9 million tonnes, the industry has suffered a dramatic contraction. Preliminary estimates for the current year place the harvest at a mere 10.4 million tonnes. To put this figure into perspective, one must look back to the drought-stricken summer of 2018, when Germany produced only 8.9 million tonnes.
The decline in output is twofold, driven by both environmental degradation and strategic shifts in land use. Firstly, the erratic weather patterns—characterized by prolonged dry spells—have severely hindered tuber growth. The lack of adequate moisture in the soil meant that potatoes could not reach their typical size or weight. Consequently, yields per hectare have plummeted from 46 tonnes to just 38.9 tonnes.
Secondly, the industry is grappling with a 11.1% reduction in the total cultivation area compared to the previous year. This contraction in planting reflects the mounting economic risks for farmers, who are balancing higher operational costs against the unpredictability of climate change. When a smaller land base meets a low-yield season, the result is an inevitable supply crunch that ripples through the entire supply chain.
Chronology of a Price Surge
The path to the current price spike began in the fields during the spring and summer planting seasons.
- Early 2024: Farmers faced rising input costs, including fertilizers and energy, leading many to cautiously reduce their planting area to hedge against potential financial losses.
- Mid-Summer: The lack of precipitation began to take a toll on the developing tubers. By August, the severity of the crop deficiency became clear, triggering a massive shift in Erzeugerpreise (producer prices).
- August 2024: The market witnessed a seismic shift. Landowners saw the prices paid for their potatoes jump by 61.5% compared to the previous year. This was the largest increase in producer-level potato prices in three years.
- September 2024: The reality hit the retail sector. As wholesale costs surged, retailers began passing these expenses to the end consumer, resulting in the 11.3% price hike reported by the Federal Statistical Office.
This trajectory underscores a fundamental law of economics: when supply is constrained by environmental factors, the commodity price at the source is the first to react, followed by a lag time as that cost is transferred to the consumer.
Supporting Data: A Comparison of Costs
To understand the severity of the situation, it is essential to compare the potato market with the broader inflationary landscape. Germany’s general inflation rate currently sits at approximately 3.3%. The 11.3% increase in potato prices is, therefore, more than three times the general inflation rate. This places the potato in a unique category of "inflationary outliers"—essential goods that are experiencing price volatility far beyond the reach of standard monetary policy interventions.
However, the data offers a nuanced picture. While the price of raw, unpeeled, or bagged potatoes has risen, the frozen food sector presents a curious anomaly. Data indicates that processed potato products—such as frozen French fries, hash browns, or potato croquettes—have actually seen a price decrease of 4.7% compared to the same month last year.
Analysts suggest this discrepancy is due to the nature of the supply chain for processed goods. These products are often manufactured using long-term contracts and raw materials stored in cold-chain facilities from previous, higher-yield cycles. As these stockpiles deplete and new, more expensive raw materials are integrated into the manufacturing process, it is expected that the prices for frozen goods will eventually align with the current upward trend in fresh produce.
The Economic Implications for Producers and Retailers
For the German agricultural sector, the current state of affairs is a double-edged sword. While the 61.5% increase in producer prices suggests higher revenue per tonne, the reality for the individual farmer is more complex. The significant loss in yield means that even with higher prices, total revenue per hectare may not cover the fixed costs of machinery, labor, and crop protection.
Furthermore, the pressure on retailers is immense. Supermarket chains in Germany operate on notoriously thin margins. When a staple product like the potato experiences a double-digit price hike, retailers are faced with a difficult choice: absorb the cost and risk profitability, or pass the price on to the consumer and risk a backlash or a change in shopping habits. The current trend indicates that retailers have opted for the latter, choosing to maintain their margins even at the risk of consumer dissatisfaction.
The Broader Impact on Consumer Behavior
The potato, long considered an "inflation-proof" staple, is no longer immune to the pressures of the modern global economy. For low-income households, which rely heavily on affordable, nutrient-dense staples, this price hike is significant. The household budget, already stretched thin by rising energy costs and previous rounds of food inflation, is being pressured once again.
Sociologists and nutritionists are watching these trends closely. Historically, when staple food prices rise, consumption patterns shift toward cheaper, often less healthy alternatives. There is a concern that if potato prices remain elevated, consumers may turn away from fresh vegetables entirely, opting for processed, shelf-stable, or lower-quality foods.
Future Outlook: Adaptation and Policy Needs
Looking ahead, the German potato industry is at a crossroads. The reliance on traditional cultivation methods in the face of increasingly frequent droughts is becoming untenable.
Strategic Responses:
- Investment in Irrigation: There is a growing consensus that large-scale investment in irrigation infrastructure is required to insulate farmers from the effects of dry summers.
- Drought-Resistant Varieties: Agricultural research institutes are under pressure to accelerate the development and certification of potato varieties that require less water and are more resistant to heat stress.
- Diversification of Sourcing: While Germany is a major producer, the instability of local harvests suggests that the retail sector may need to diversify its supply chain to include more international imports during lean years, though this poses its own challenges regarding carbon footprints and supply chain reliability.
The Federal Ministry of Food and Agriculture has acknowledged the strain on the sector, noting that climate change is no longer a future threat but a present reality for German farmers. Policy discussions are now shifting toward providing more robust "climate-resilience" subsidies, aiming to help farmers transition to regenerative practices that improve soil water retention.
Conclusion: A Wake-Up Call for the Food System
The 11.3% increase in potato prices is more than just a line item on a grocery receipt; it is a manifestation of the structural vulnerabilities in the food supply chain. As climate change continues to disrupt traditional growing cycles, the agricultural sector must pivot toward more resilient, data-driven farming methods.
For the average German consumer, the coming months will be a test of how much the market can sustain. With frozen goods still reflecting previous, cheaper cycles, the full impact of this year’s harvest failure may not be felt until the early months of 2025. In the meantime, the potato serves as a potent reminder that even the most domestic of crops is inextricably linked to global climate realities and the complex, often fragile, economic systems that feed the nation. Whether this serves as a temporary blip or a harbinger of a new era of food inflation remains to be seen, but one thing is certain: the era of cheap, predictable agricultural staples is being challenged by a changing planet.