
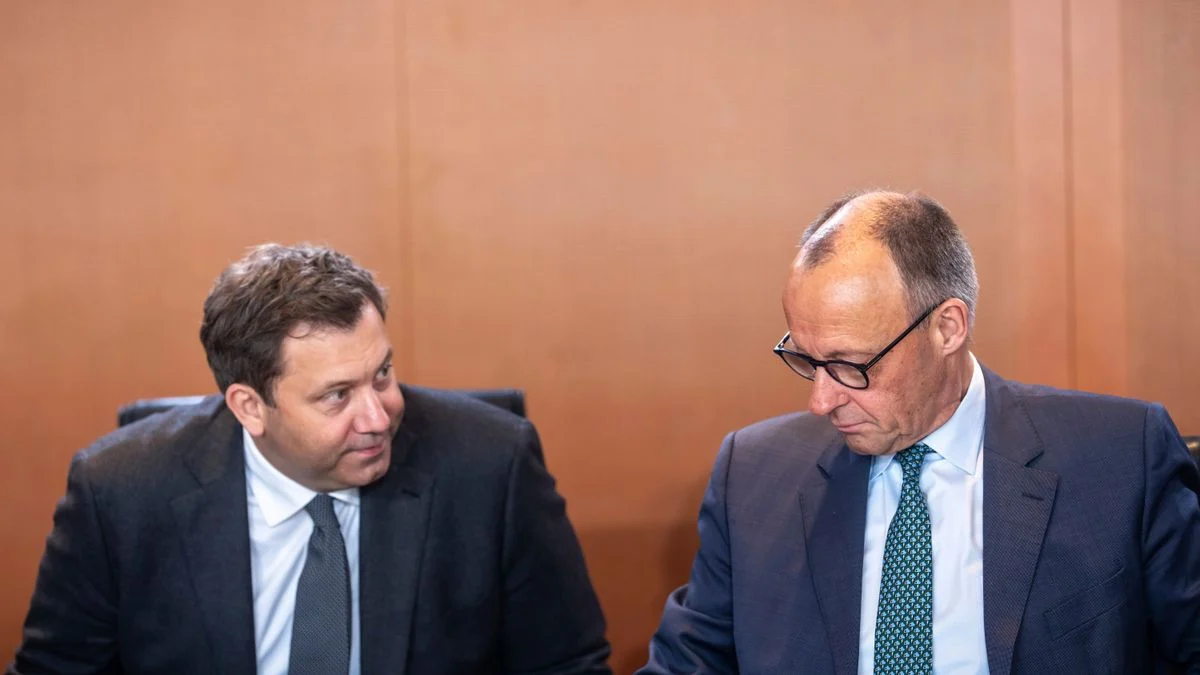
The German federal government is once again at the center of a heated fiscal and health policy debate as plans for a national "sugar tax" on sweetened beverages move into the inter-ministerial coordination phase. Spearheaded by Lars Klingbeil, the initiative aims to strike a delicate balance between public health objectives and fiscal revenue generation. However, the proposal has already encountered significant headwinds, sparking criticism from political allies and raising questions about the efficacy of such a levy in an increasingly inflationary economic climate.
The Core Proposal: A Strategic Shift in Public Health
At the heart of the current proposal is a desire to tackle rising rates of obesity and diabetes—conditions that place an immense, growing burden on the German public healthcare system. Klingbeil’s strategy is twofold: to generate substantial tax revenue for the federal budget and to create a market-based incentive for beverage manufacturers to reformulate their products.
By imposing a financial penalty on high-sugar content, the government hopes to force a "health-by-stealth" approach, encouraging corporations to reduce sugar levels to avoid the tax threshold. The latest iteration of the draft, circulated to government ministries this past Wednesday, represents a significantly "softened" version of initial, more aggressive proposals.
Under the current plan, the tax would apply to all beverages containing more than five grams of sugar per 100 milliliters. Recognizing the complexities of the beverage market, the government has carved out several significant exemptions:
- Zero-calorie beverages: Drinks sweetened with sugar substitutes will remain untaxed.
- Natural juices: Pure fruit and vegetable juices are exempt.
- Alcoholic alternatives: Non-alcoholic beers and wines are excluded from the levy.
The tax rate itself is designed to be graduated, shifting in correlation with the sugar content. The projected cost to the consumer—and the burden on the manufacturer—is expected to fall between 26 and 38 cents per liter, depending on the specific sweetness profile of the drink.
Chronology of a Controversial Draft
The path to this week’s draft has been fraught with internal friction. The proposal’s journey reflects the typical, often gridlocked nature of German coalition governance.
Initial Conceptions: The idea of a sugar tax has been discussed in policy circles for years, gaining momentum as a way to combat lifestyle-related diseases.
The Commission’s Role: A specialized Financial Commission on Health had previously weighed in with its own set of recommendations. However, government insiders report that Klingbeil’s current draft deviates significantly from the commission’s original suggestions, leading to friction within the executive branch.
The Wednesday Submission: On Wednesday, the formal draft was sent to various ministries for coordination. This triggered immediate pushback, not just regarding the content, but the process.
Internal Criticism: According to sources close to the SPIEGEL reporting, members of the Union (CDU/CSU) and even some internal government factions have criticized the Ministry of Finance for failing to conduct a "pre-coordination" phase. By skipping this step, the ministry effectively bypassed the opportunity to iron out political disagreements before the draft became public, leading to the current public-facing friction.
Fiscal Projections and Economic Impact
The Ministry of Finance has tied the implementation of this tax to a timeline starting July 1, 2027. The fiscal projections accompanying the draft are ambitious, reflecting the government’s need to shore up federal coffers.
The ministry expects the tax to yield roughly one billion euros in annual revenue once fully operational. The projected breakdown of these figures is as follows:
- First Year (2027): 945 million euros.
- Second Year (2028): 1.155 billion euros.
- Long-term Outlook (2031): The government anticipates revenue climbing to 1.18 billion euros, assuming current consumption patterns persist.
These figures rely on the assumption that the tax will act primarily as a fiscal tool rather than a purely preventative one. Critics, however, argue that if the tax is truly successful in changing consumer behavior and encouraging manufacturers to lower sugar content, these revenue figures will naturally decline. This creates a "fiscal paradox": the government is effectively budgeting for a health-negative behavior to continue to ensure the stability of the tax revenue.

Official Responses and Ministerial Silence
When pressed for comment, the Ministry of Finance has adopted a posture of cautious diplomacy. In a statement provided to SPIEGEL, a spokesperson noted: "The Federal Government has decided to introduce a sugar-sweetened beverage tax. Currently, consultations are underway regarding its concrete implementation."
The ministry has pointedly refused to provide further details, citing the sensitive nature of the "ongoing negotiations." This reflects the reality that the bill is currently a "work in progress" and remains subject to significant revision as other ministries—particularly those concerned with the economic burden on the food and beverage sector—weigh in.
Implications for the Beverage Industry and Consumers
The implications of this policy extend far beyond the Ministry of Finance. For the German beverage industry, which includes thousands of small-to-medium-sized enterprises (Mittelstand), the tax represents an additional layer of administrative and financial complexity.
1. The Burden on Manufacturers
Companies will face the immediate cost of reformulating recipes, conducting laboratory testing to certify sugar content, and updating labeling requirements. For smaller producers, these costs could be prohibitive, potentially leading to market consolidation where only large multinationals have the scale to absorb these compliance costs.
2. The Consumer Experience
For the average shopper, the tax will likely manifest as a price increase at the checkout counter. While proponents argue that the price signal will encourage healthier choices, critics point out that these costs are regressive. Lower-income households, who often rely more heavily on processed, sugary beverages, will feel the pinch of these price hikes more acutely than wealthier demographics.
3. The Health Argument
The fundamental justification for the tax remains the potential for long-term reduction in public health spending. If the policy effectively steers consumers toward water, tea, or low-sugar alternatives, the long-term impact on the public healthcare system could be substantial. However, public health experts are divided on whether a tax alone is sufficient to change deeply ingrained dietary habits without parallel efforts in education, school lunch programs, and advertising restrictions.
Conclusion: A Delicate Balancing Act
As the draft moves through the bureaucratic machinery of the German government, the sugar tax remains a lightning rod for broader ideological disputes. It pits the state’s role as a "nanny" (or guardian of public health) against the principles of free-market enterprise and individual consumer choice.
The failure to conduct early coordination among ministries suggests that the path to passage will be rocky. As the 2027 implementation date approaches, the government will need to navigate not only the industry’s lobbying efforts but also the skepticism of voters who may view the tax as yet another state-mandated increase in the cost of living.
Ultimately, the success of the sugar tax will not be measured solely by the billion-euro revenue it generates, but by whether it succeeds in shifting the German palate away from excess sugar—a goal that remains as complex as the politics surrounding the bill itself. Whether the government can maintain the integrity of its health goals while addressing the economic concerns of its critics will be the defining challenge of this legislative process in the coming months.