Düsseldorf. Germany, long considered a bastion of stability in the European housing market, is currently facing a profound structural crisis. As mortgage interest rates climb and construction costs surge, the dream of homeownership is becoming increasingly elusive for millions. Simultaneously, the political landscape is shifting, with radical debates over the expropriation of large real estate corporations intensifying following electoral successes for left-wing parties in Berlin.
The latest data from the Empirica Regio Immobilien- und Mietpreisindex for the third quarter of 2026, obtained exclusively by the Handelsblatt, paints a sobering picture of a market defined by soaring costs and mounting pressure on both tenants and prospective buyers.
Main Facts: The Escalating Cost of Living
The data reveals a stark reality: both the rental and purchase markets are experiencing significant upward pressure. According to the index, which aggregates data from over 100 real estate portals including Immoscout24, Immowelt, and Immonet, new construction rents have climbed by an average of 3.8% compared to the same quarter last year.
Even more alarming is the situation in the existing housing stock, where rents have surged by 10.2%. This divergence suggests that as new housing remains expensive due to high construction costs, landlords of older properties are increasingly adjusting their prices to match the broader market inflation.
Nationwide, the average price for a newly built apartment now sits at 5,230 euros per square meter. While this reflects a modest 1.1% increase compared to the second quarter of 2026, it represents a long-term trend of escalating barrier-to-entry costs that shows little sign of abating.
A Regional Deep Dive: The Bavarian Dominance
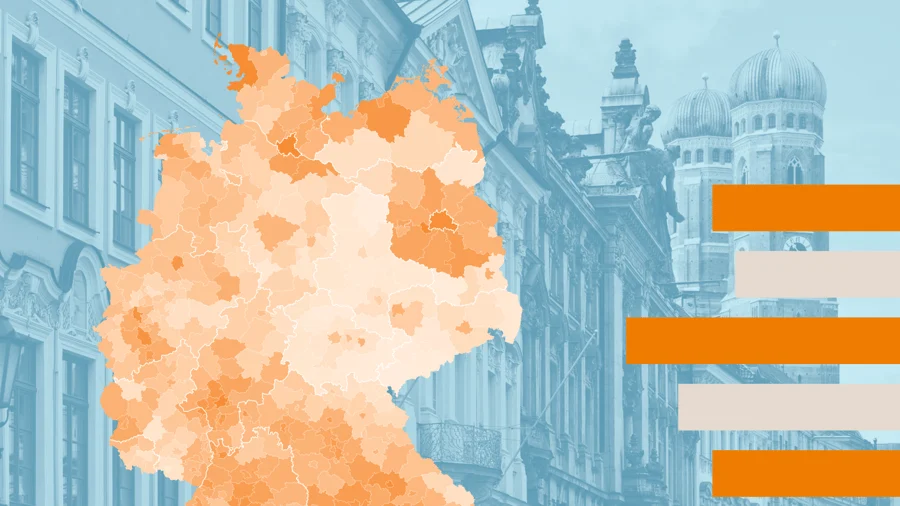
The geography of the German housing crisis is heavily skewed toward the south. Traditionally, Munich has been the epicenter of high real estate costs. However, the latest figures show that the city has been surpassed by Garmisch-Partenkirchen, which now claims the title of the most expensive region for new construction in Germany.
The concentration of wealth and demand in Southern Bavaria is absolute. The eight most expensive administrative districts in the country are all located in the southern part of the state. Starnberg, for instance, recorded the strongest growth, with prices jumping 7.8% over the year.
This stands in sharp contrast to rural regions, particularly in Eastern Germany, where price levels remain significantly lower. However, even in these regions, volatility is high. The district of Anhalt-Bitterfeld in Saxony-Anhalt, for example, saw a staggering 60.9% increase in new construction prices, illustrating that the crisis is not confined to urban centers but is rippling outward into previously affordable regions.

Chronology of the Crisis: From Stability to Turbulence
To understand how Germany arrived at this point, one must look at the convergence of three distinct factors that have hit the market in rapid succession over the last 36 months.
- The Pandemic Shock: Initial supply chain disruptions during the global health crisis caused raw material costs for construction to spike, halting many new projects.
- The Interest Rate Pivot: The rapid shift in monetary policy by the European Central Bank intended to curb inflation sent mortgage rates soaring. For an average homebuyer, this has meant an additional 200 euros in monthly credit costs, forcing many to reconsider their purchase plans.
- The Regulatory Squeeze: Stricter building standards and energy efficiency requirements have combined with high labor costs to create a "cost-plus" environment where builders are unable to lower prices without risking insolvency.
Supporting Data: The Divergence of New vs. Existing Homes
One of the most revealing insights from the Empirica Regio data is that existing home prices are rising significantly faster than new builds.
Tobias Just, Professor of Real Estate Economics at the University of Regensburg, interprets this as a clear signal of "affordability displacement." As potential buyers are priced out of the new-build market due to soaring interest rates and construction premiums, they are flooding the market for older, existing properties. This surge in demand for the limited stock of existing homes is driving prices up faster than in the new-build segment.
"In some regions, the lack of new construction is so severe that there is almost no price-forming supply left," Just explains. "When buyers are forced to compete for a dwindling supply of existing homes, the upward pressure on prices is inevitable."
Official Responses and Expert Analysis
The industry is divided on the trajectory of the market. Reiner Braun, CEO of Empirica AG, offers a sobering outlook. He believes that while new construction prices are tied to the immutable rise of labor and material costs—which he describes as rising until "St. Nimmerleinstag" (the Greek calends)—the existing home market may face a correction.
"Existing property prices could soon yield because the buyers are disappearing," says Braun. "The lack of affordability due to rising credit costs will dampen demand and likely return some bargaining power to the buyers."
Ingo Foitzik, Head of Sales at mortgage broker Interhyp, confirms that while there is no "fundamental retreat" from the real estate market, buyers are becoming increasingly pragmatic. "Prospective buyers are now much more willing to compromise on location, size, or equipment to fit their monthly budget," Foitzik notes.
Implications: The Search for a Solution
The political implications of these data points cannot be overstated. With rental markets in Frankfurt, Hamburg, and Munich experiencing double-digit percentage increases, the pressure on the federal government to intervene is immense.

1. The Debate Over Expropriation
The discussion surrounding the expropriation of large housing companies in Berlin has moved from the fringes to the center of political debate. Proponents argue that the market has failed to provide affordable housing, and therefore, the state must take direct control of assets to cap rents. Critics, however, argue that such measures would deter the very investment required to solve the supply shortage.
2. The Need for Regulatory Reform
Experts like Professor Tobias Just argue that the answer lies not in market interference but in supply-side reform. "A trend reversal is not currently recognizable," he says. "Genuine relaxation can only occur if we simplify and accelerate the building process." The current bureaucratic hurdles, coupled with strict environmental regulations, have created a bottleneck that prevents the market from responding to the clear signals of high demand.
3. The Impact on Social Mobility
The housing crisis is fundamentally a crisis of social mobility. As the "rental burden ratio" (the percentage of income spent on housing) continues to climb, the ability of middle-class families to build wealth through property ownership is being severed. This creates a long-term risk of a wealth gap that could define German society for decades to come.
Conclusion: A Market in Search of Equilibrium
As of the final quarter of 2026, the German housing market remains a tale of two realities. In major metropolitan areas, the peak may have been reached, with price growth stagnating as buyers hit an affordability wall. In smaller, less liquid markets, the lack of supply continues to drive prices toward historic highs.
The path forward is fraught with difficulty. If the government chooses to focus on price controls and expropriation, it risks stalling the construction of new units, further exacerbating the supply deficit. If it focuses on deregulation and incentivizing construction, it faces the political challenge of navigating a public that is increasingly frustrated by the perceived greed of the real estate sector.
Ultimately, the Empirica Regio data serves as a diagnostic tool: Germany is suffering from a supply-side structural illness. Without a fundamental shift in how housing is planned, permitted, and financed, the current cycle of rising costs and diminished accessibility is likely to persist, leaving both renters and buyers in a state of prolonged uncertainty.
First published: October 15, 2026, 04:10 AM.