

FRANKFURT – The French Republic, the second-largest economy in the Eurozone, is currently grappling with a convergence of crises that threatens to destabilize the broader European financial landscape. Following a series of disappointing economic indicators and an alarming spike in volatility within the sovereign debt markets, economists and EU policymakers are increasingly sounding the alarm. France is not merely facing a temporary downturn; it is undergoing a profound stress test that is testing the limits of investor confidence in the heart of the European Union.
Main Facts: A Dual Crisis of Growth and Debt
The situation in France is defined by a simultaneous contraction in business activity and a sharp erosion of market trust. According to the latest data from S&P Global, the Purchasing Managers’ Index (PMI) for the manufacturing and services sectors has plummeted to 48.4 points. This reading is critical because any figure below 50.0 indicates a contraction in economic output.
Market analysts had anticipated a more resilient performance, projecting the index to remain at or above the 51.1 level recorded in September—a threshold that would have signaled modest, albeit stagnating, growth. Instead, the sharp decline highlights a rapid deterioration in private sector sentiment.
Compounding this industrial stagnation is the intensifying "spread" on French government bonds (OATs) compared to German Bunds, which are widely considered the "gold standard" of safe-haven assets in the Eurozone. In recent days, this yield differential has widened significantly, hitting levels not seen since the height of the sovereign debt crisis in 2012. Investors are demanding a premium of over 1.7 percentage points to hold French debt, a clear signal that the market is beginning to price in a higher risk profile for the French state.
Chronology: From Optimism to Contraction
The trajectory of the current crisis can be mapped through a series of escalating developments that have eroded the foundation of the French economy over the past several months:
- September Resilience: The month of September concluded with a PMI of 51.1, offering a glimmer of hope that the French economy might avoid a recession despite broader European headwinds and high interest rates.
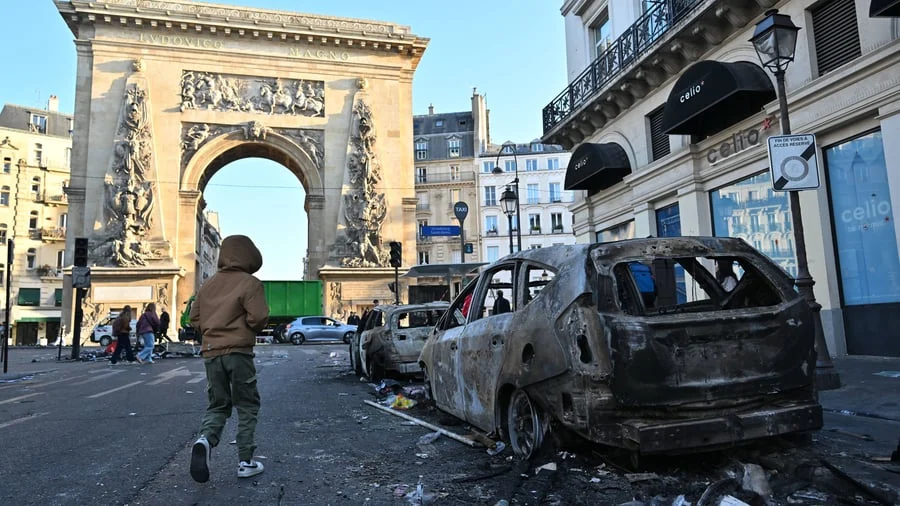
- The Onset of Social Unrest: Shortly after the release of the September data, a wave of civil unrest broke out across Paris and several major French metropolitan areas. These events did not merely cause social disruption; they had immediate, tangible consequences for the commercial sector.
- Early October Indicators: As October progressed, the frequency and intensity of civil disturbances increased, directly impacting retail, logistics, and tourism. Reports from the French Chamber of Commerce began to emerge, estimating that over 2,000 businesses had sustained direct physical or operational damage.
- The "Black Friday" of Markets: By the third week of October, the financial markets began to react aggressively to the combination of poor economic data and the images of unrest. The spread between French and German bonds breached the 1.7% mark, triggering alarms in Brussels and Frankfurt.
Supporting Data: The Anatomy of the Slowdown
The data provided by S&P Global serves as a diagnostic tool for the health of the French economy. The decline to 48.4 is not an isolated event but a reflection of systemic pressures:
- Manufacturing Decline: Energy costs, combined with a softening global demand for European goods, have left the French industrial sector struggling. Manufacturers are reporting reduced order books and a reluctance to invest in capital expenditure.
- Service Sector Fatigue: As the backbone of the French economy, the services sector has been particularly vulnerable to the recent social instability. Consumer spending, which had been propping up the economy, has shown signs of a sharp pull-back as uncertainty weighs on household sentiment.
- Fiscal Vulnerability: France’s public debt-to-GDP ratio, already high compared to its Northern European neighbors, is under immense scrutiny. With interest rates remaining elevated due to European Central Bank (ECB) policies, the cost of servicing this debt is rising at a time when tax revenues are likely to shrink due to the contraction.
Charlotte de Montpellier, an economist at ING, noted that the timing of these events is catastrophic. "The timing could hardly be worse," she remarked. "With the national debt already in a fragile state, the added costs of repairing infrastructure and supporting businesses damaged during the unrest create a fiscal burden that the budget can ill afford."
Official Responses and Market Reactions
The French government and the European Central Bank find themselves in a precarious position. The Elysée Palace has been scrambling to provide assurances to both the domestic public and international investors. However, rhetoric has done little to soothe the bond markets.
Harry Chambers, a lead economist at Capital Economics, provided a sobering assessment of the situation. "The recent PMI data brings no relief to the bond market; in fact, it exacerbates the anxiety," Chambers stated. "When you combine a shrinking economy with the political instability evidenced by the ongoing unrest, you create a toxic environment for sovereign debt. The 1.7 percentage point spread is a manifestation of the market’s ‘fear factor’ regarding France’s long-term fiscal solvency."
While the French government has attempted to frame the economic downturn as a "transitory phenomenon" linked to global cycles, investors are increasingly looking at the structural issues—labor market rigidity, tax burdens, and political volatility—that prevent France from executing the reforms necessary to align its economy with the current realities of a high-interest-rate environment.
Implications: A Risk to the Eurozone
The "French Problem" is rapidly becoming a "European Problem." Because the Eurozone is a deeply integrated financial system, the instability of its second-largest member carries systemic risk.
1. The Contagion Effect
If the spread between French and German bonds continues to widen, it could lead to a broader loss of confidence in Euro-denominated assets. Historically, when investors lose faith in one major Eurozone economy, they move their capital toward the perceived safety of German Bunds, which causes the yields of the "peripheral" or more indebted nations to spike, creating a contagion effect that can destabilize the entire currency bloc.
2. The ECB’s Dilemma
The European Central Bank is caught between the need to curb inflation and the necessity of maintaining financial stability. If the ECB decides to maintain high interest rates to combat inflation, it risks pushing France further into recession. Conversely, if it lowers rates to support the economy, it may trigger currency devaluation and inflationary pressures elsewhere. The crisis in France limits the ECB’s policy flexibility significantly.
3. The Future of the European Project
Beyond the numbers, there is a political dimension. France has long been the political engine of the European Union, working alongside Germany to drive integration. A weakened France, distracted by domestic crisis and fiscal distress, leaves a power vacuum in Brussels. This could lead to a stalling of major EU initiatives, from green energy transitions to defense cooperation.
4. Investor Sentiment and the "Risk Premium"
Institutional investors are currently reassessing the "Eurozone premium." For years, the assumption was that the ECB would act as a backstop for all member states. However, the current divergence in economic performance between Germany and France is testing the limits of this belief. If investors demand higher yields for French debt, the French government will have to divert more of its budget toward interest payments, leading to potential austerity measures that could further dampen economic growth and fuel more social unrest.
Conclusion: The Path Forward
The situation in France is a wake-up call for the European Union. The combination of a cooling economy and political volatility creates a feedback loop that is difficult to break. To stabilize the situation, policymakers must find a way to decouple the immediate fiscal strain from the broader economic sentiment.
This likely requires a two-pronged approach: first, a credible medium-term fiscal strategy that reassures the bond markets of France’s commitment to debt sustainability; and second, a robust social policy to address the grievances that have led to the current civil unrest.
As the fourth quarter progresses, the eyes of the global financial community will remain fixed on Paris. Whether France can navigate this "stress test" without triggering a broader Eurozone crisis will be the defining economic story of the coming months. The era of low interest rates and predictable growth is over; for France and its European partners, the era of navigating high-stakes volatility has clearly begun.




















