By Financial News Desk
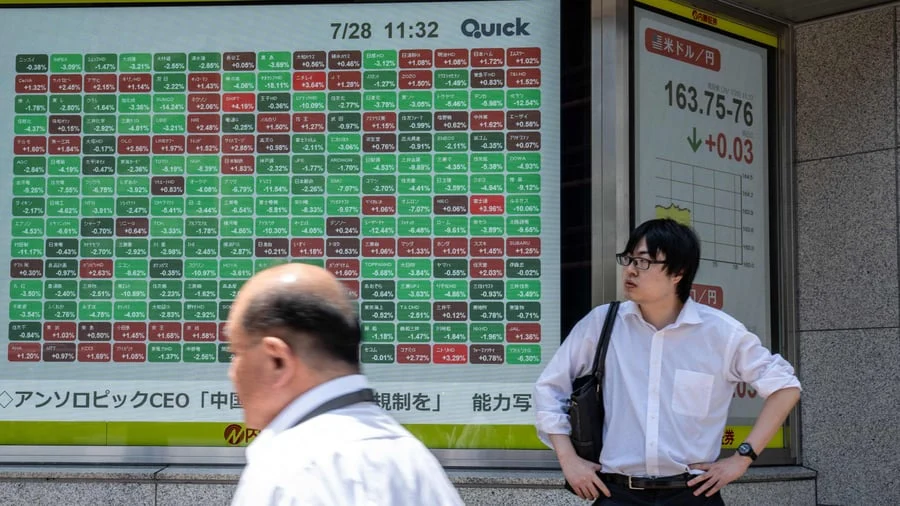
Asian equity markets are currently grappling with a wave of skepticism that threatens to derail the bullish momentum of the year. As indices like the Nikkei 225 and Topix face their second consecutive week of losses, a clear narrative has emerged: investors are no longer content with the promise of "AI potential." Instead, they are demanding empirical evidence that the billions of dollars flowing into artificial intelligence infrastructure are translating into tangible, bottom-line profitability.
This shift in sentiment—from blind optimism to critical scrutiny—has triggered a notable sell-off in key technology and manufacturing sectors, casting a long shadow over the future of the AI-driven market rally.
1. The Core Tension: Capital Expenditure vs. Profitability
The fundamental issue currently weighing on global markets, with a particular intensity in Asia, is the widening gap between capital expenditure (CapEx) and operational returns. Technology giants, chipmakers, and infrastructure providers have been pouring unprecedented sums into data centers, specialized semiconductors, and high-energy cooling systems.
While these investments are technically necessary to sustain the development of large language models (LLMs) and generative AI, the market is beginning to question the "payback period." Investors are asking: When will these massive infrastructure costs begin to yield significant improvements in profit margins?
The recent, less-than-stellar financial signals coming out of the broader AI ecosystem—including reactions to updates from industry giants like OpenAI—have served as a catalyst for this nervousness. The market is effectively signaling that it has moved past the "excitement phase" and entered the "accountability phase."

2. Chronology of the Market Shift
The cooling of the market did not happen overnight. To understand the current climate, one must look at the progression of events that led to this week’s downturn:
- Q1 2024: The Hype Cycle Peak: Early in the year, news of massive AI funding rounds and supply chain expansion drove the Nikkei to record highs. Almost any company associated with the AI supply chain—from semiconductor manufacturers to cooling technology providers—saw its valuation soar.
- Q2 2024: The First Whispers of Doubt: As earnings reports began to reflect the heavy costs of AI integration, analysts started noting that while revenue was rising, margins were being squeezed by the astronomical costs of power consumption and high-end hardware procurement.
- Early Q3 2024: The "Energy Reality Check": A rise in regional energy prices and volatility in the bond markets added a layer of macro-economic stress. Investors began to realize that the energy-intensive nature of AI infrastructure was a long-term liability.
- Current Week: The Correction: The convergence of high energy costs, tightening credit conditions, and uncertainty regarding the sustainability of AI revenue models has resulted in the current retreat. The decline of major players like the SoftBank Group has signaled a wider retreat from "high-risk, high-reward" technology bets.
3. Sector-Specific Impacts and Supporting Data
The divergence in market performance is striking. While some firms are seeing their valuations slashed, others—those with more established, software-based service models—are actually seeing gains.
The Declining Titans
The most prominent casualty in the current market environment is the SoftBank Group. As a major investor in the AI space, including its historical ties to OpenAI, SoftBank is often seen as a bellwether for AI sentiment. The 5.4 percent drop in its share price this week reflects a broader reassessment of its portfolio value in a higher-interest-rate environment.
Similarly, the manufacturing sector has been hit hard. Companies that provide the physical components for the AI revolution are suffering from a "supply glut" fear.
- Furukawa Electric: Shares fell by 4.83 percent, reflecting concerns over the demand for specialized cabling and connectivity infrastructure.
- Murata Manufacturing: Down 4.68 percent. As a key supplier of electronic components (including capacitors essential for AI-ready servers), the company’s slide suggests that investors fear a potential slowdown in server build-outs.
The Resilient Performers
Interestingly, not all tech-adjacent companies are suffering. The shift is favoring service-oriented companies that provide the "implementation" layer of AI:
- Nomura Research Institute (NRI): Bucked the trend with a 5.13 percent gain.
- Baycurrent: Rose by 3.97 percent.
- Shift: Gained 3.92 percent.
These gains indicate that investors are rotating out of the "hardware and infrastructure" phase of the AI trade and into the "consulting and implementation" phase. The market is betting that while the physical infrastructure build-out may face headwinds, the demand for businesses to integrate and manage AI tools is only just beginning.

4. Official Responses and Analyst Perspectives
Industry leaders and institutional analysts remain divided on whether this is a permanent correction or a temporary "breathing room" for the market.
The Institutional View:
Many analysts from major investment banks in Tokyo and Singapore have noted that the "AI bubble" has not burst, but rather "deflated to a more rational level." One senior analyst remarked, "The market is undergoing a necessary purification. We spent eighteen months pricing in perfection. Now, we are pricing in the reality of high capital costs and the reality of the energy grid."
Corporate Strategy:
Most large-cap tech companies have maintained their commitment to long-term AI spending. They argue that the infrastructure currently being built is a long-term moat. A spokesperson for a major semiconductor firm noted, "Building the capacity to train the next generation of models is a multi-year project. Investors looking for quarterly margin expansion are ignoring the decade-long transformation of the global economy."

5. Strategic Implications for the Future
The current market turbulence carries profound implications for both investors and corporate leaders.
For Investors: The "Quality" Shift
The days of blindly buying any company with "AI" in its branding are effectively over. Investors are pivoting toward "Quality AI"—companies that demonstrate a clear path to monetization. The outperformance of consulting firms like Nomura Research Institute suggests that the market is beginning to prioritize companies that help other firms implement AI, rather than companies that merely buy the expensive hardware required to host it.
For Tech Firms: Efficiency as the New North Star
The message from the markets is clear: efficiency is now as important as innovation. Companies that can demonstrate how they are reducing the energy footprint of their data centers, or how they are optimizing software to run on cheaper, less power-hungry hardware, will likely regain investor favor.

The Macro Risk: Energy and Geopolitics
The correlation between rising energy prices and the AI sell-off is not coincidental. AI is, at its core, a massive consumer of electricity. As long as energy prices remain elevated, the operating expenses of the AI industry will remain a drag on earnings. Furthermore, as geopolitical tensions influence the supply chains of advanced chips, the volatility we are seeing today is likely to persist.
Conclusion: A Maturing Market
The nervousness currently sweeping through the Asian stock markets is not a sign that the AI revolution has failed; rather, it is a sign that the market is maturing.
The initial period of speculative fervor has given way to a period of cold, hard financial logic. The winners of the next phase will not be those who can spend the most, but those who can prove that their investments create real value. As the Nikkei and Topix look to stabilize, the focus will remain on the intersection of capital discipline and technological progress. For now, investors are holding their breath, waiting for the next round of earnings reports to show whether the AI promise can finally pay its own bills.