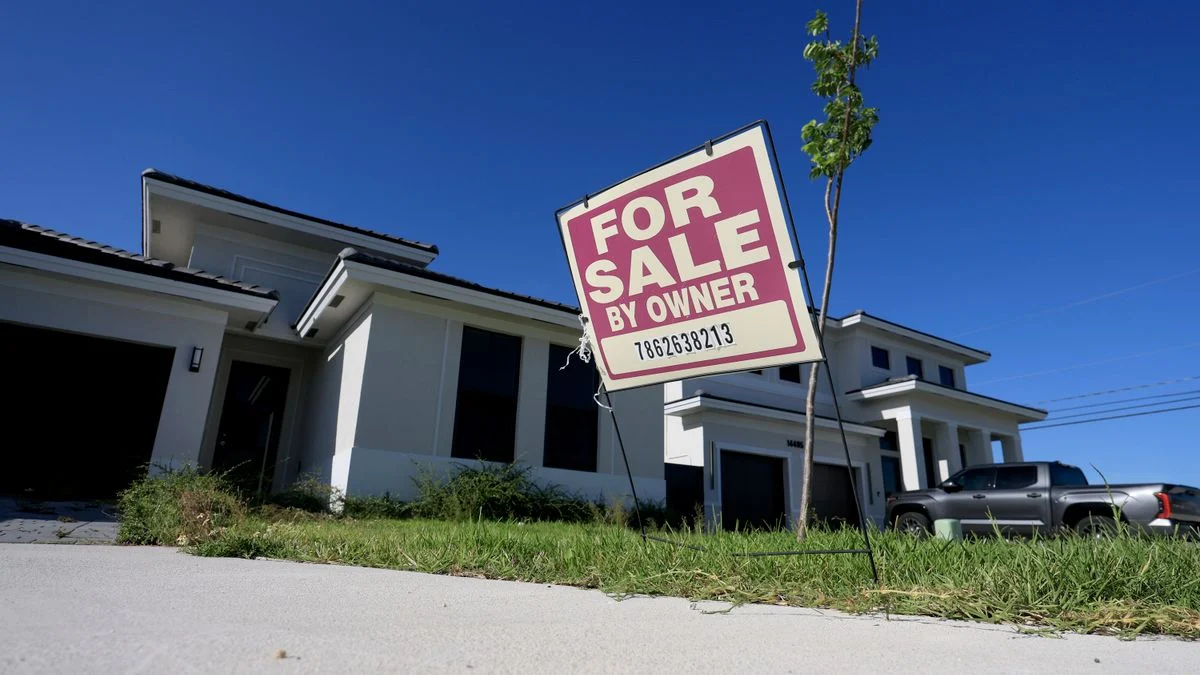
The dream of homeownership in the United States is facing its most significant structural challenge in nearly three years. According to the latest data released by the Mortgage Bankers Association (MBA), the average interest rate for a 30-year fixed-rate mortgage has surged to 7.49 percent. This rapid escalation in borrowing costs is not merely a statistical anomaly; it is a profound economic development that is reshaping the housing market, curbing consumer activity, and casting a long shadow over the upcoming congressional elections.
The Current Landscape: A Market Under Pressure
The rise to 7.49 percent marks the highest level seen since November 2023, representing a sharp departure from the relatively stable—though elevated—rate environment that defined the early months of the year. This surge has had an immediate, chilling effect on market activity. Mortgage application volumes have plummeted, dropping 4.2 percent in a single week.
Joel Kan, the deputy chief economist at the MBA, articulated the severity of the situation: "Only a very small number of homeowners currently have an incentive to refinance at these interest rates. The rapid rise in borrowing costs has effectively pushed many potential buyers out of the market, creating a state of paralysis for those who were previously considering entry."
For prospective buyers, the math has become increasingly prohibitive. When mortgage rates jump by even a single percentage point, the monthly payment on a median-priced American home increases by hundreds of dollars, forcing millions of middle-class families to either delay their plans indefinitely or pivot toward rental markets that are already strained by high demand.
Chronology of a Financial Upheaval
To understand how the U.S. economy arrived at this juncture, one must examine the confluence of geopolitical and macroeconomic pressures that have built up over the last eight months.
- February: The onset of joint U.S.-Israeli military operations in Iran served as a primary catalyst for market instability. The uncertainty surrounding these engagements triggered a flight to safety, disrupting energy markets and contributing to an environment of heightened risk. Since that month, mortgage rates have climbed by approximately 1.4 percentage points.
- Summer: Persistent inflationary pressures became the defining feature of the American economy. By August, inflation was measured at 3.4 percent—significantly higher than the Federal Reserve’s target of 2 percent. This data forced the hand of policymakers.
- September: The Federal Reserve executed a pivotal interest rate hike. While intended to cool the economy and bring inflation back toward the 2 percent target, the move signaled a "higher-for-longer" approach, confirming that the central bank is prepared to accept slower growth to ensure price stability.
- October: As the nation approaches the November 3rd congressional elections, the reality of these monetary decisions is hitting the kitchen tables of American voters. While market analysts do not anticipate another rate hike at the Fed’s next meeting in late October, the damage to consumer sentiment is already visible.
Supporting Data and Comparative Analysis
The struggle is not confined to American borders. A global trend of rising borrowing costs is currently suppressing housing markets in developed economies. In Germany, for example, the impact is equally pronounced. According to analysis by the firm Barkow Consulting, interest rates for 10-year fixed-rate mortgages have climbed to approximately 4.25 percent annually. This represents the highest level in Germany since May 2011, signaling that the era of "cheap money" that defined the post-2008 decade is effectively over.
In the United States, the discrepancy between the Fed’s target rate and the market-driven mortgage rates highlights a broader structural issue: the bond market is pricing in long-term inflation fears. Despite the Federal Reserve’s signaling of future caution, the bond yields that dictate mortgage rates have continued to climb, suggesting that investors are not yet convinced that the inflationary threat has been adequately neutralized.

Political Implications: The Cost of Living Crisis
Four weeks before the congressional elections, these financial figures have transformed into political ammunition. President Donald Trump, currently facing a historically low approval rating of 32 percent, finds himself in a precarious position.
A joint survey conducted by Reuters and the polling firm Ipsos released this Monday reveals that the "cost of living" has become the single most important issue for American voters. For many, the ability to secure a home is the ultimate barometer of economic success. As interest rates drive housing costs to record highs, the perceived failure of the current administration to curb inflation and stabilize the mortgage market is directly impacting voter sentiment.
Political analysts suggest that the "affordability trap"—whereby high rates prevent current homeowners from selling (due to their own existing low-rate mortgages) and prevent new buyers from entering—is creating a toxic political environment. When citizens feel that the basic markers of middle-class stability are being stripped away by macroeconomic policy, the incumbent party often bears the brunt of that frustration.
The Federal Reserve’s Dilemma
The Federal Reserve now finds itself in a classic "soft landing" trap. On one hand, they must continue to signal hawkishness to ensure that inflation expectations remain anchored. On the other hand, the housing market serves as a primary engine of the American economy. If the mortgage market continues to contract, the risk of a broader economic slowdown—or even a recession—increases significantly.
The Fed’s communication strategy remains focused on the "data-dependent" narrative. By keeping the door open for further action before the end of the year, they are attempting to keep the market on its toes. However, as the yield curve continues to fluctuate, it is clear that the market is beginning to prioritize growth concerns over inflation-fighting fervor.
Conclusion: A Future of Uncertainty
The current trajectory of mortgage rates serves as a sobering reminder of the interconnectedness of global security, domestic monetary policy, and individual economic well-being. As the United States moves toward the November elections, the housing market will remain a central focal point.
For the average American, the 7.49 percent interest rate is not just a percentage point; it is a barrier to entry, a constraint on wealth accumulation, and a source of deep anxiety. As the Federal Reserve balances the fight against inflation with the need for economic stability, the nation waits to see whether these rates have peaked or if the American housing market is destined for a prolonged period of stagnation. The upcoming weeks will be decisive, not only for the political landscape of Washington but for the financial future of millions of Americans looking for a place to call home.