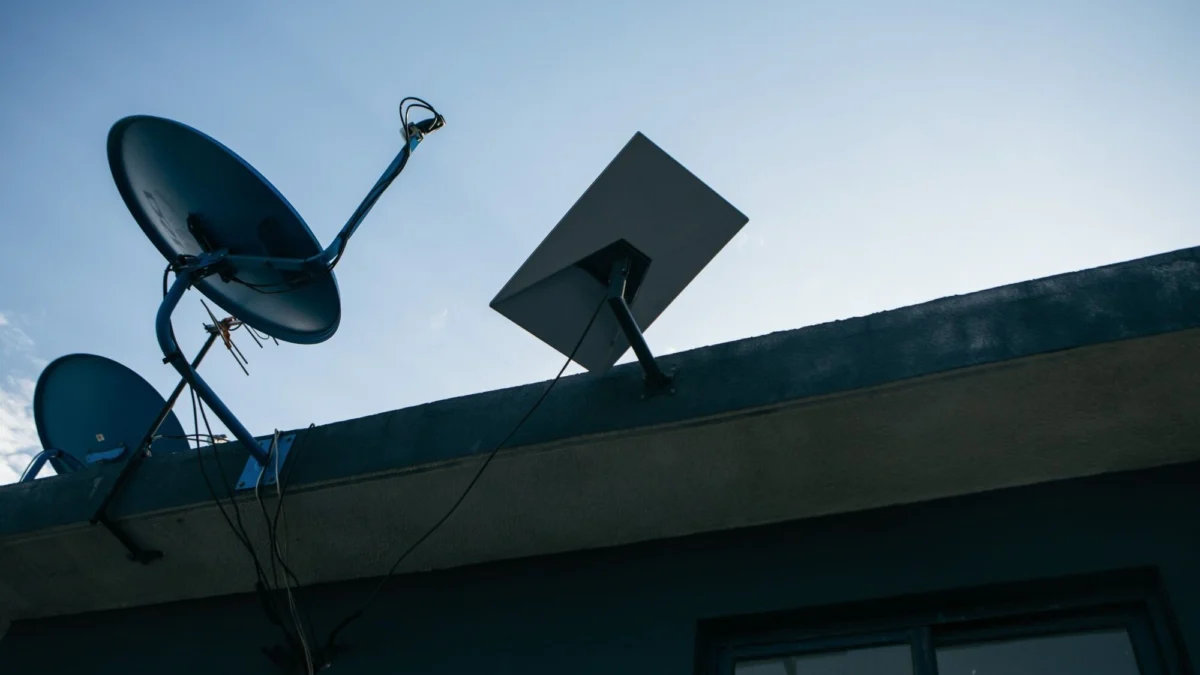
The global telecommunications landscape is witnessing a seismic shift. For years, the industry operated under the assumption that satellite internet providers like Elon Musk’s SpaceX were complementary niche players—filling the gaps in connectivity for rural, underserved, or maritime regions where traditional cellular infrastructure was cost-prohibitive. However, a series of strategic moves by SpaceX, capped by a massive acquisition of "low-band" radio frequencies, has transformed this narrative overnight. SpaceX is no longer just a partner to the mobile industry; it has emerged as a direct, formidable competitor to the world’s largest telecommunications giants.
The market reaction has been swift and unforgiving. Following news of SpaceX’s aggressive expansion into terrestrial mobile spectrum, telecommunications stocks—including the Deutsche Telekom, as well as major players in Australia and New Zealand—have seen significant downward pressure. With shares of the Deutsche Telekom dropping more than seven percent since last Friday, investors are clearly signaling a fear that the era of traditional, terrestrial-only network dominance is drawing to a close.
The Strategic Shift: Acquiring the "Final Piece of the Puzzle"
At the heart of this disruption is a calculated acquisition. SpaceX has secured a significant stake in "low-band" frequencies previously held by the investment firm Grain Management. While the financial details have been subject to intense speculation, reports from the Wall Street Journal estimate the deal to be worth approximately $8 billion.

In the telecommunications sector, frequency is the currency of power. Low-band spectrum is particularly prized because it possesses superior propagation characteristics—it can travel long distances and, crucially, penetrate physical obstacles like building walls, trees, and dense urban infrastructure.
Elon Musk himself confirmed the strategic importance of this acquisition, describing it as "the final, critical piece of the puzzle" required to facilitate comprehensive, nationwide mobile coverage across the United States. By integrating this spectrum into its existing satellite constellation, SpaceX is moving beyond simple "satellite-to-satellite" data relay and toward a direct-to-cell (D2C) model that threatens to bypass traditional cell towers entirely.
Chronology of a Disruption
To understand the scale of this threat, one must trace the evolution of SpaceX’s relationship with the telecom industry:

- 2019–2021: The Niche Phase. SpaceX launches the first batches of Starlink satellites. The narrative is focused solely on "bridging the digital divide," targeting isolated communities, ships, and aircraft. Major telcos, including T-Mobile, Verizon, and AT&T, largely view these developments as non-threatening.
- 2022: The Partnership Pivot. T-Mobile and SpaceX announce a collaboration, "Coverage Above and Beyond." The goal is to use Starlink satellites to provide text messaging and limited connectivity in dead zones. At this stage, the industry remains convinced that satellite connectivity is too slow and latent to replace terrestrial 5G.
- 2023: Testing and Regulatory Filings. SpaceX begins filing for FCC permits to test direct-to-cellular connectivity using standard mobile handsets. The company demonstrates that it can beam data directly to unmodified smartphones.
- 2024: The Acquisition. SpaceX moves from a collaborative partner to an infrastructure owner. By acquiring low-band spectrum, the company gains the legal and technical authority to broadcast signals that any standard phone can receive without the need for a terrestrial partner.
- Late 2024 (Present): The Market Shock. Global telecom stocks begin to plummet as analysts realize that SpaceX intends to build a standalone, global, space-based mobile carrier that operates independently of existing national network operators.
Supporting Data: Why the Market is Worried
The fear among traditional telecom operators is grounded in the inherent limitations of their business models compared to the scalability of Starlink.
1. The Cost of Infrastructure
Traditional mobile operators must spend billions annually on capital expenditures (CAPEX) to build, maintain, and upgrade terrestrial cell towers. This is a labor-intensive, geographically constrained process. In contrast, SpaceX leverages the reusable Falcon 9 launch architecture to deploy satellites at a fraction of the cost, achieving global coverage without the need to secure thousands of individual land-use permits.
2. The Physics of Coverage
Terrestrial networks are "cell-based," requiring a dense web of towers to ensure handoffs as a user moves. If a user is in a rural valley or a remote mountainous region, the cost to deploy a tower is often higher than the lifetime revenue that the user provides. SpaceX’s satellite network treats the entire planet as a single, unified cell.
3. The "Unmodified Handset" Advantage
Previously, satellite phones required bulky, specialized hardware. SpaceX’s technical breakthrough involves beam-forming and advanced processing on its satellites that allow them to "talk" to the existing LTE/5G chips in standard iPhones and Android devices. This removes the barrier to entry for the consumer, who no longer needs a new device to access the Starlink network.
Official Responses and Regulatory Hurdles
The industry’s response has been a mix of skepticism and frantic lobbying. Representatives from major mobile carriers have long argued that satellite-to-cell technology is fundamentally inferior to terrestrial networks due to latency issues and the difficulty of signal penetration through thick concrete or subterranean structures.
However, the regulatory environment is beginning to shift. The Federal Communications Commission (FCC) in the United States is currently evaluating the implications of SpaceX’s new spectrum holdings. While SpaceX claims that its service will "democratize access to information," competitors are expected to argue that the consolidation of space-based spectrum by a single entity creates an anti-competitive monopoly.

In Europe, the reaction has been more muted but equally concerned. Regulators in the EU are watching the US developments closely, fearing that if domestic carriers lose their competitive edge, the continent’s telecommunications infrastructure could become entirely reliant on a US-based private entity.
Long-Term Implications: The End of the "Cellular" Era?
The implications of this shift are profound and reach far beyond the stock market.
The Death of the Dead Zone
The most immediate impact will be the functional elimination of "no-service" areas. For global travelers, hikers, and residents of rural areas, the promise of continuous, seamless connectivity is an immense boon. However, this also undermines the competitive advantage of regional telcos that relied on their local coverage superiority to retain customers.

Pricing Pressure
If SpaceX enters the market as a retail carrier, it will likely utilize a disruptive pricing model. By leveraging its low-cost satellite operations, SpaceX could offer flat-rate global roaming, potentially undercutting the exorbitant roaming fees currently charged by traditional carriers. This could force a global "race to the bottom" in pricing, which would be excellent for consumers but devastating for the margins of traditional telecom companies.
National Security Concerns
The transition to space-based communication also raises complex national security questions. If a significant percentage of a nation’s mobile traffic is routed through a private, non-sovereign constellation, the government loses the ability to exert control over that infrastructure. This is a point of contention that will likely be debated in legislative chambers for years to come.
The Future of the "Telco"
For traditional companies like Deutsche Telekom, the path forward is uncertain. They must either pivot toward becoming "service providers" that resell satellite capacity or invest heavily in terrestrial technologies that Starlink cannot match—such as high-capacity local 6G nodes for ultra-dense urban environments. The era of the "all-in-one" carrier is ending; the future will likely be divided between massive space-based broad-coverage providers and niche, high-performance urban infrastructure providers.

Conclusion
Elon Musk has once again proven his ability to look at an established industry, identify its inherent inefficiencies, and apply a technology—in this case, low-earth-orbit satellite networking—that renders existing business models obsolete. The decline in telecommunications stock prices is not a temporary market fluctuation; it is a fundamental revaluation of the industry’s future.
As SpaceX moves forward with its plans to integrate its newly acquired spectrum into the Starlink constellation, the telecommunications giants of the world are finding themselves in a position they have never faced before: fighting for relevance against an opponent that is quite literally above them. The sky is no longer the limit; it is the battlefield.