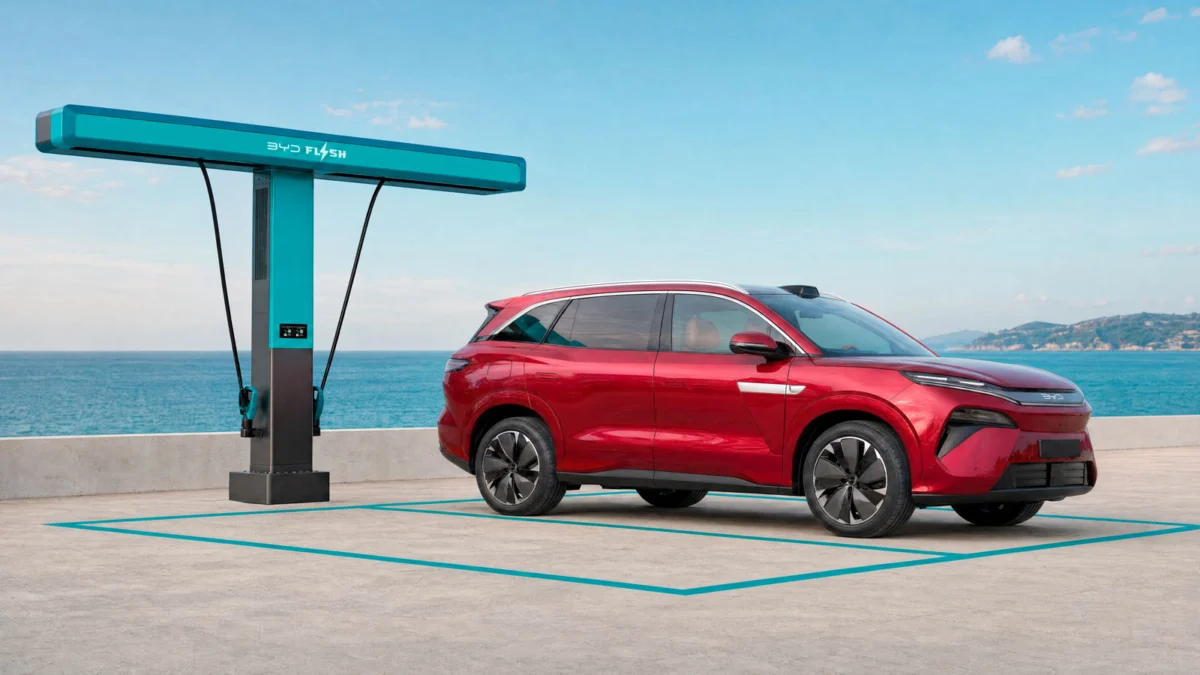
In a landmark shift for global trade relations and the automotive sector, the European Commission has unveiled a stringent regulatory framework aimed at curbing the influx of Chinese-manufactured hybrid and plug-in hybrid electric vehicles (PHEVs) into the European Union. Starting next year, the EU will implement a hard cap, limiting imports from China to 350,000 hybrid units annually.
This measure, set to remain in effect for an initial duration of four years, represents a calculated effort to stabilize the European automotive market, protect domestic manufacturers, and address the growing trade imbalance between Brussels and Beijing. While the regulation allows for a modest annual growth rate of six percent in import volume, the cap is significantly below current market trends, signaling a pivotal cooling-off period for the rapid expansion of Chinese brands in the European space.
The Core Facts: A Regulatory Hard Stop
The decision, finalized last week following high-stakes negotiations in Beijing, serves as a defensive mechanism against the rapid market penetration of Chinese automotive technology. Under the new mandate:
- Annual Import Limit: Starting January 1, 2025, Chinese hybrid and plug-in hybrid exports to the EU will be capped at 350,000 units.
- Duration: The policy will be enforced for a four-year term, with a built-in annual escalation clause of six percent.
- Scope: The regulation specifically targets hybrid and plug-in hybrid vehicles, which combine internal combustion engines with battery-electric propulsion.
- Legal Standing: Both the European Commission and Chinese authorities have stated that the agreement is fully compliant with World Trade Organization (WTO) protocols, avoiding the need for protracted litigation.
Chronology: From Negotiation to Consensus
The path to this agreement was paved with months of escalating tension and intensive diplomatic shuttle-diplomacy.
Early 2024: The Build-Up of Friction
Throughout the first half of the year, European automotive giants—most notably those based in Germany—expressed growing alarm over the "dumping" of affordable, tech-heavy Chinese hybrids. With the EU’s green transition accelerating, Chinese firms utilized their supply chain dominance to gain a foothold in Europe’s most profitable segment.
Late Summer 2024: The Reality of Market Dominance
Data from August confirmed that hybrids and PHEVs had become the single largest segment of the European market, accounting for over 44 percent of new vehicle registrations. As European manufacturers struggled with high energy costs and supply chain bottlenecks, the share of Chinese-made hybrids in the EU reached approximately 12 percent.
The October Summit: The Breakthrough
The turning point occurred last week in Beijing. EU Trade Commissioner Maroš Šefčovič met with China’s Minister of Commerce, Wang Wentao. The meeting was widely expected to be the precursor to a trade war. However, in an unprecedented move, the Chinese delegation agreed to voluntary export restraints. According to Šefčovič, this marks the first time Beijing has agreed to curb its export volumes without waiting for a formal, adversarial trade dispute to escalate into a full-blown economic conflict.
Supporting Data: Why the EU Acted
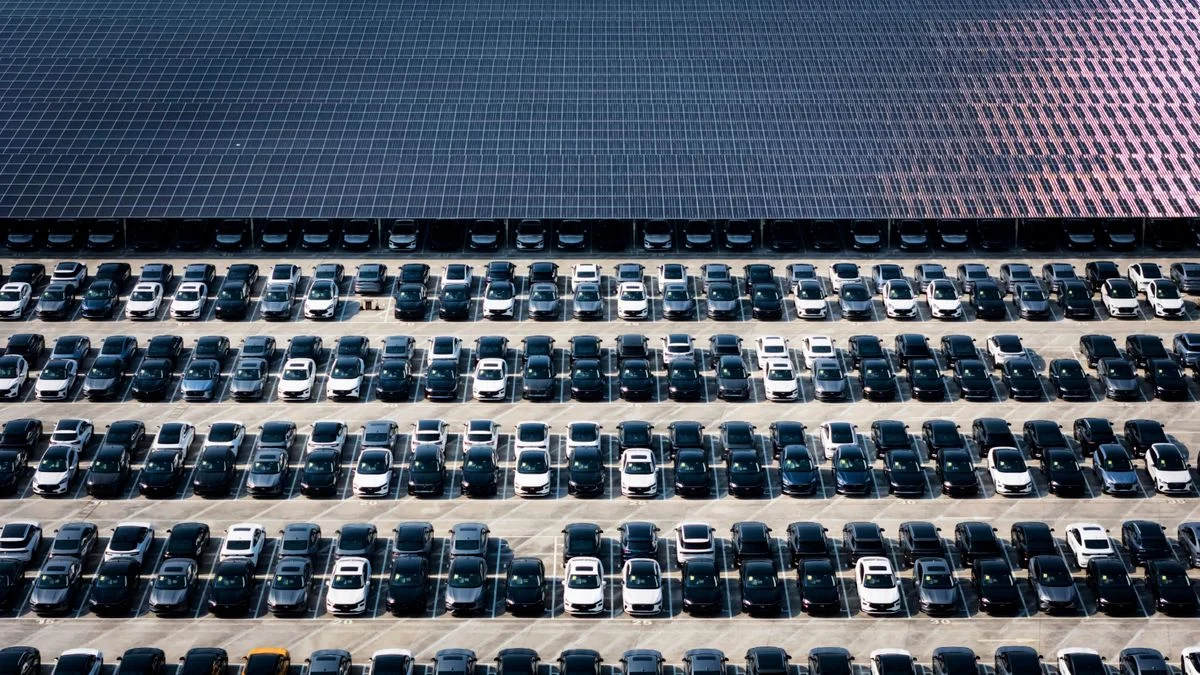
To understand the severity of the intervention, one must look at the raw statistics. Brussels estimates that by the end of 2024, total imports of hybrid vehicles from China will reach approximately 800,000 units.
By limiting this to 350,000 in 2025, the Commission is effectively slashing the import volume by more than 50 percent compared to current projections. For a segment that has been the primary growth engine for Chinese exporters in Europe, this represents a significant strategic setback.
Market Share Dynamics
Currently, Chinese manufacturers command roughly 12 percent of the EU hybrid market. Analysts suggest that the new quota will force a contraction of this share to approximately six percent by the end of the first year of implementation. This is not merely an economic policy; it is a structural redesign of the European transport landscape intended to give domestic manufacturers—such as Volkswagen, BMW, and Stellantis—the breathing room required to optimize their own hybrid product portfolios.
Official Responses and Diplomatic Nuance
The tone emanating from Brussels and Beijing has been surprisingly measured.
The European Perspective: Commissioner Šefčovič highlighted the necessity of "fair competition" and "level playing fields." He emphasized that the EU remains open to trade, but that the speed of the influx of Chinese vehicles threatened to hollow out the European industrial base—a base that currently employs millions of workers in high-skilled manufacturing roles.
The Beijing Perspective: For the Chinese Ministry of Commerce, the agreement is a strategic concession. By agreeing to the quotas, Beijing avoids the imposition of aggressive, punitive tariffs that could have been far more damaging in the long run. By keeping the dialogue within the WTO framework, China maintains its status as a reliable trading partner while ensuring that it retains a foothold in the European market, albeit a restricted one.
Implications for the Industry
For German and European Automakers
The immediate effect of this policy will be a reprieve from the intense price wars that have dominated the hybrid sector. German manufacturers, which have long relied on the "premium" hybrid segment, have found themselves squeezed by Chinese entrants offering similar technology at significantly lower price points. The quota will likely allow European firms to maintain higher margins on their hybrid models, providing the capital necessary to fund the transition to full battery-electric vehicles (BEVs).
For the Consumer
European consumers may face a shift in market availability. With the supply of imported Chinese hybrids capped, the range of available models may narrow. This could lead to a stabilization—or even a slight increase—in the prices of hybrid vehicles, as the competitive pressure from low-cost Chinese imports is artificially dampened.
For Global Trade Relations
The most significant long-term implication is the normalization of "managed trade." By opting for quotas rather than tariffs, the EU and China have established a precedent for handling trade disputes in the green technology sector. This "managed growth" model may become the blueprint for future interactions involving other sectors, such as solar panels, wind turbines, and battery storage solutions.
Future Outlook: A Four-Year Horizon
The four-year timeline is critical. The European Commission is essentially providing the European automotive industry with a "protected incubation period."
During these four years, the EU expects its domestic manufacturers to:
- Scale Up Production: Achieve economies of scale that reduce the cost of European-made hybrids.
- Innovate: Close the technology gap regarding software integration and battery efficiency, where Chinese firms currently hold a competitive advantage.
- Supply Chain Independence: Build out a more resilient European supply chain for raw materials and battery components, reducing reliance on China.
Whether these measures will ultimately prove successful remains a point of contention among economists. Critics argue that protectionism often leads to complacency, warning that shielding domestic giants from competition might hinder the very innovation the EU seeks to foster. Conversely, proponents argue that without this intervention, the European automotive sector—a cornerstone of the continent’s economy—would have been irrevocably compromised by an unsustainable influx of foreign subsidized vehicles.
As the industry moves toward 2025, the automotive sector remains at a crossroads. The EU’s move to cap imports is not just a trade policy; it is a statement of intent: that the green transition in Europe will be a transition led, and to a significant extent manufactured, by Europe itself. The next four years will determine whether this strategy secures the future of the European car industry or creates a fragmented market characterized by higher costs and limited consumer choice.